Nephros Beats Estimates, But Slowing Core Programmatic Growth Leaves Its Third-Quarter Results Looking Less Convincing
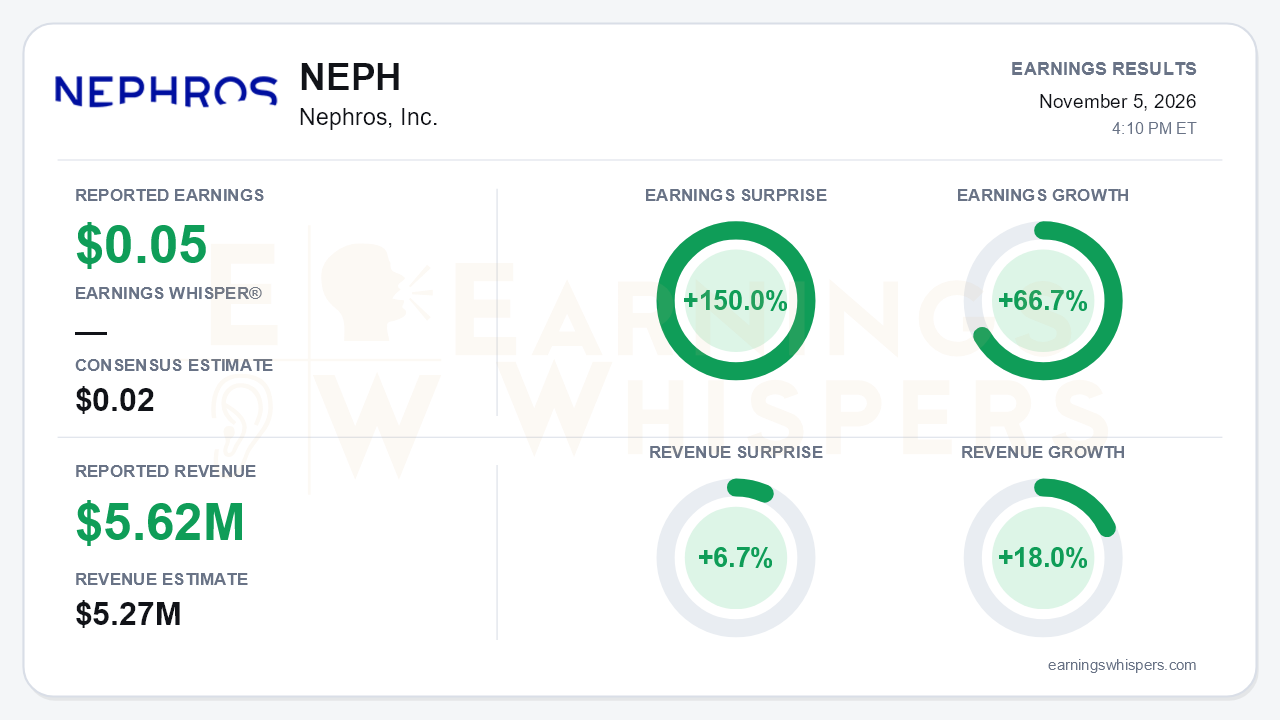
Nephros (NASDAQ: NEPH) delivered a clean headline beat for the third quarter. Earnings were $0.05 per share against a $0.02 consensus, a 150.0% surprise. Revenue of $5.62 million topped the $5.27 million estimate by 6.7%. Earnings grew 66.7% year over year and revenue rose 18.0%. The quality of the beat deserves scrutiny, however. The metric management treats as the core health indicator, programmatic revenue, grew only about 8% year over year. That compares with roughly 23% in the first quarter and double digits in the second. That is the central tension: the top line still looks strong, but the recurring engine beneath it is slowing, and more of the growth came from emergency response sales the company itself flags as outside its control.
The income statement shows real operating leverage on a small base. Gross profit rose to $3.29 million from $2.92 million. Total operating expenses grew just 7%, with SG&A up 9% on headcount and professional fees and R&D essentially flat. As a result, operating income climbed to $501,000 from $314,000. GAAP net income was $512,000, or $0.05 per diluted share, versus $337,000, or $0.03. Adjusted EBITDA was $558,000 versus $418,000. Because the absolute numbers are tiny, the percentage surprise and growth figures overstate how much the quarter changed. Sequentially, the picture is weaker. Revenue fell from the record $6.0 million in the second quarter, and net income and adjusted EBITDA were well below the second quarter's $1.2 million and $1.3 million. Those second-quarter figures were inflated by the roughly $600,000 IEEPA tariff refund.
Margins are where the underlying trend is least encouraging. Third-quarter gross margin was 58%, down from 61% a year ago. It is essentially unchanged from 57% in the first quarter and 58% in the fourth quarter of 2025. Stripping out the refund, the second quarter's 67% reported margin was about nine points lighter, so margin has not recovered despite the tariff rate falling from 15% to 10%. Management attributed the pressure to several factors:
- remaining tariffs and freight costs;
- euro strength raising product costs;
- a growing mix of lower-margin service and commercial revenue.
The refund is non-recurring. Investors should therefore treat the high-50s as the operating baseline until proven otherwise.
The call preserved a credible, if slower, growth story built on breadth. Active customer sites reached a record 1,766, up from 1,724 in the second quarter and 1,676 in the first. That reflects 31 net additions and an improvement after a flat start to the year. Healthcare accounted for about 64% of new sites and commercial and industrial for about 17%. Management described partner-channel deals with enterprise and franchise customers as building slowly. Emergency response revenue surged on Legionella attention in New York City. The Nephros Water Institute's education push is meant to feed a pipeline that includes PFAS, micro- and nanoplastics, sterile processing and eyewash applications. Management framed 2027 around a larger recurring base and broader markets but offered no formal financial guidance. That leaves investors to judge on their own whether 8% programmatic growth is a trough or a new run rate.
The balance sheet adds a quieter caution. Cash slipped to $4.5 million from $4.7 million at the end of the second quarter and $5.4 million at year-end, even though the company was profitable. The reason is working capital. Inventory rose to $4.95 million from $3.23 million at year-end, and receivables climbed to $3.58 million from $2.41 million. The company remains debt-free, so this is not a liquidity problem. Still, profits are not yet converting into cash.
The market had already turned skeptical heading into the report. Investor sentiment, measured on the snapshot taken the day before the release, deteriorated meaningfully from -0.39 to -0.71. The shares closed that day at $3.25, down 14.5% from the $3.80 open after the August report. They had given back most of the post-report spike to $4.87 on August 19 and sat about 33% below that high. The stock was trading 11.1% below its 200-day moving average and only 8% above its October 6 low of $3.01. The Earnings Whispers price and AVWAP trend readings remain negative, though momentum has turned positive. Bears have legitimate ammunition in the programmatic slowdown and stalled margins. A beat this size against a deeply pessimistic setup could still matter in the short term.
The bottom line is that Nephros beat comfortably and kept growing its installed base, but the third quarter was steady rather than accelerating. Core programmatic growth slowed sharply, emergency response revenue did more of the work, and gross margin remains stuck near 58% once the one-time tariff refund is excluded. With no guidance and cash drifting lower on inventory build, the next quarter needs to show programmatic growth re-accelerating before the slowdown looks temporary rather than structural.
Read our earnings preview for Nephros, Inc.: https://www.earningswhispers.com/article/NEPH/22534
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-29 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-20 | |
| Jul-06 | |
| Jun-18 | |
| Jun-16 | |
| May-07 | |
| Apr-30 | |
| Apr-16 | |
| Apr-01 |
