IonQ Beats And Raises Again, But SkyWater-Fueled Scale Arrives With Deeper Operating Losses
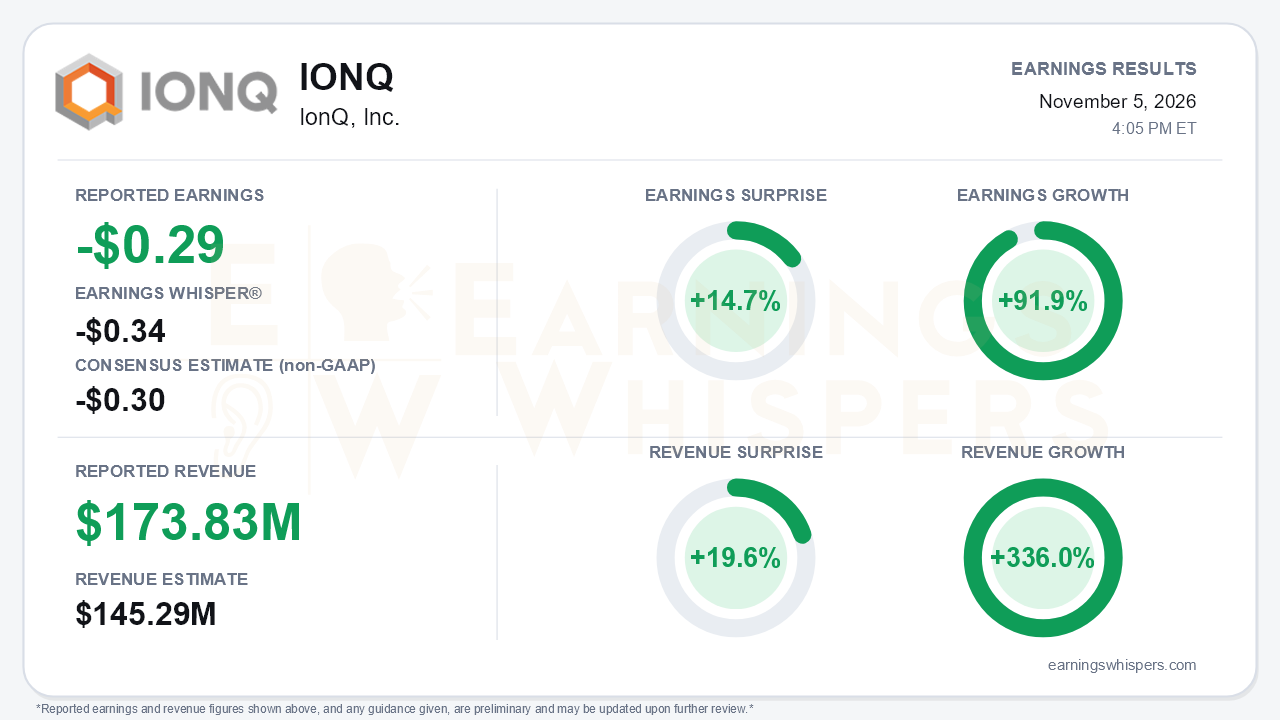
IonQ delivered another beat-and-raise quarter. The adjusted loss of $0.29 per share was narrower than the $0.30 consensus and well ahead of the $0.34 Earnings Whisper number, a 14.7% surprise. Revenue of $173.83 million topped the $145.29 million consensus by 19.6% and grew 336.0% year over year. Full-year revenue guidance rose again, to $505-$515 million from the $450-$460 million outlined at September's Investor Day. The central tension is that the top line is scaling dramatically while the cost of that scale keeps rising. Much of the revenue leap is acquired, and the core loss trajectory has not yet turned.
The quality of the beat deserves scrutiny. Revenue more than doubled from $80.1 million in the second quarter, but $83.5 million came from SkyWater Foundry Services, which contributed only two months after closing at the end of July. The organic IonQ Platform segment still grew an impressive 127% to $90.3 million, driven by Tempo deployments and sensing and space deliveries. The GAAP picture is noisier. Net income attributable to IonQ was $564.0 million, or $1.42 per basic share, but that came entirely from an $896 million non-cash gain on warrant liabilities. Strip that out and the operating loss widened to $433 million from $169 million a year earlier. Cost of revenue consumed roughly 78% of sales, up from about 53% a year ago, a reflection of the lower-margin foundry mix. Earnings Whispers calculates year-over-year earnings growth of 91.9%, although the release's own reconciliation shows the adjusted loss compares with a $0.17 loss in the year-ago quarter.
The call preserved a credible and broadening growth story.
- **Backlog:** Remaining performance obligations more than doubled to $1.2 billion, with $689 million attributable to the IonQ segment. That figure was helped by roughly $290 million of new signings, about $180 million of which was in compute.
- **Mix:** Multi-product deals rose to 40% of segment revenue.
- **Quantum computing:** Management lifted its expected quantum computing revenue growth for the year to more than 110%, up from roughly 100% last quarter.
- **Superion 256:** 2027 capacity is sold out, and orders are filling into 2028.
- **Tone:** Management's emphasis shifted from integration toward scale and, notably, a path to profitability through pricing, site consolidation and compensation alignment.
Not every metric moved the right way. International mix fell to about 35% of the IonQ segment from roughly 50% in the second quarter.
The catalyst slate is the strongest the company has assembled. IonQ is the only trapped-ion company advanced to DARPA's Quantum Benchmarking Initiative Stage C, with a potential program value of up to $300 million. NVIDIA will install a Superion 256 as the first on-premise quantum computer at its Accelerated Quantum Research Center. New contracts include a $33 million SDT deal and a $28 million DARPA atomic-clock award. The Elisity acquisition adds zero-trust security software and roughly 100 enterprise customers. On the foundry side, SkyWater signed Qolab, extended its work with D-Wave and grew non-IonQ quantum revenue more than 30%.
Bears have legitimate ammunition, however.
- **Widening losses:** Adjusted EBITDA has worsened every quarter this year, from -$96.8 million in Q1 to -$120.3 million in Q2 and -$133.6 million in Q3, and no combined margin or EBITDA targets were offered.
- **Cash burn:** Operating cash burn reached $570 million through nine months.
- **Dilution:** The October $2.0 billion equity raise lifted pro forma liquidity to $3.7 billion, but it extends the dilution pattern.
- **Execution:** Integrating SkyWater and several other acquisitions adds risk.
- **Capacity:** The Superion constraint caps near-term upside.
The market setup is more complicated than the surprise implies. Investor sentiment improved from 0.02 to 0.09 ahead of the report, which is more positive but still close to neutral. That reads as cautious rather than enthusiastic. Price action has been decidedly harsh. Shares closed at $29.54 on November 4, down 28.6% from the $41.37 open after the August report and 29.3% below the 200-day moving average of $41.78. The stock entered earnings just 5.8% above its inter-earnings low of $27.93, set November 2, and 38.4% below its August 13 high of $47.95. The Earnings Whispers trend readings are mixed. Sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that IonQ's fundamental narrative strengthened materially this quarter. Revenue, backlog, guidance and strategic validation from DARPA and NVIDIA all stepped up, and the organic platform business is still more than doubling. Yet that growth is partly bought, gross margins have compressed with the foundry mix, and adjusted losses are still widening. The stock enters this report near its quarterly lows rather than its highs, so expectations are lower. For the story to hold, investors need evidence that management's new profitability talk shows up in narrowing EBITDA losses, not just in larger revenue figures.
Read our earnings preview for IonQ, Inc.: https://www.earningswhispers.com/article/IONQ/22314
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 5 hours |
Quantum Computing Stocks: IonQ, Quantinuum Q3 Results, Guidance Top Views
IONQ -10.53%
Investor's Business Daily
|
| 6 hours | |
| 15 hours | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 |
