Solventum Falls Short Of The Whisper As ERP Reversal Masks Steady ~4% Underlying Growth And A Third Guidance Raise
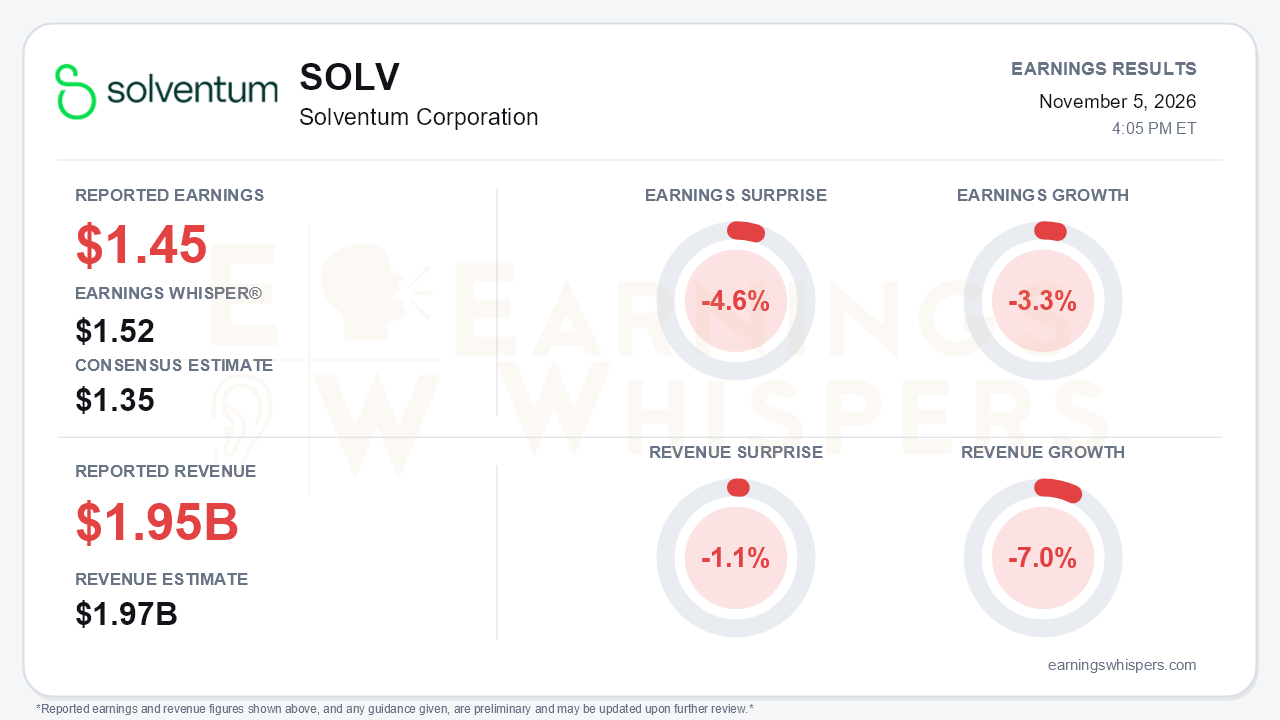
Solventum's third quarter is a case where the headline and the underlying business point in different directions. The company reported adjusted earnings of $1.45 per share on revenue of $1.949 billion. That cleared the $1.35 consensus but fell 4.6% short of the $1.52 Earnings Whisper number. Revenue missed the $1.97 billion consensus by 1.1%. Earnings fell 3.3% from a year ago and revenue dropped 7.0%. That is a sharp deceleration from the 20.9% adjusted EPS growth the company posted through the first nine months. Most of that deceleration was self-inflicted and telegraphed in advance. Customers placed roughly $125 million of advance orders in Q2 ahead of the final ERP cutover, and their reversal cut 630 basis points from Q3 organic growth. Reported organic sales fell 2.8% as a result. Stripping out that timing, management put normalized organic growth at about 4%, matching Q1 and Q2. The real story is consistency, not contraction.
The quality of the quarter is better than the top line implies, with caveats.
- **Gross margin improved.** Adjusted gross margin expanded to 57.1% from 55.8%, driven by portfolio optimization, mix and savings programs that more than offset inflation and tariffs.
- **Operating margin slipped.** Adjusted operating margin dipped 70 basis points to 19.9%, which the company attributed to the order reversal. On the call, management estimated the reversal cost about $0.35 per share and put operating margin excluding timing at roughly 22.3%.
- **GAAP results were heavy with charges.** The company posted a GAAP loss of $0.07 per share against $7.22 a year ago, when the purification and filtration sale produced a $1.5 billion gain. This quarter absorbed $157 million of separation costs and $50 million of restructuring.
- **Segments were uneven.** Dental Solutions fell 7.4% organically, and its segment margin compressed to 20.1% from 25.7%. Infection Prevention declined 5.7%. Advanced Wound Care grew reported sales 8.9% thanks to Acera. Health Information Systems grew 4.4% with a 41.7% margin.
The call was fundamentally a de-risking event. The final Americas ERP cutover is complete. Roughly 90% of 3M transition service agreements have been exited, up from about 70% last quarter, and the manufacturing footprint has been cut to 21 plants from 67. Management also renegotiated its 3M supply agreement, eliminating a roughly 100-basis-point gross margin step-up that had been scheduled for April 2027. That headwind had been flagged as a risk at the start of the year. Management expressed confidence in 2027 margin expansion even against a roughly 120-basis-point tariff-refund comparison. Growth drivers also contributed:
- Acera posted a record $35 million quarter, up 35%.
- A new 510(k) clearance allows Restrata to be used alongside V.A.C. Therapy.
- Clarity composite veneers are in limited launch ahead of a full rollout in early 2027.
Guidance moved higher again. Full-year adjusted EPS is now $7.20 to $7.30, up from $7.10 to $7.20, and this is the third raise from an original $6.40 to $6.60. Organic growth is now expected toward the high end of 2.5% to 3.0%, or about 4% excluding SKU exits. Operating margin is expected near the top of 22.2% to 22.7%. The raise, however, was in line with estimates rather than ahead of them.
Bears still have legitimate ammunition:
- **Free cash flow.** The guide was held at $200 million to $300 million despite a Q3 boosted by an IEEPA tariff refund.
- **Q4 outlook.** Implied Q4 organic growth sits slightly below the year-to-date normalized run rate.
- **Decelerating pockets.** HIS growth slowed from 5.4% to 4.4%, and Acera decelerated from 48% growth.
- **HIS separation.** The planned separation will dilute operating margin for the remaining company by roughly 400 basis points annualized, and the EPS hit has not been quantified.
- **Balance sheet.** Cash fell to $451 million from $878 million after $403 million in year-to-date buybacks, and $507 million of debt is now current. Repurchases slowed to about $50 million in Q3.
Investor sentiment remained positive but softened, slipping from 0.18 to 0.13 heading into the report. Shares were essentially flat at $89.35, down 0.2% from the open after the August report. They had traded in a wide range in between. The stock set a 52-week high of $94.16 on September 1, then slid to $80.76 on October 30 before rebounding about 10.6% into the print. That leaves shares about 5% below the quarter's high, with the market having already round-tripped a good deal of optimism. The trend readings are mixed: momentum is positive while the AVWAP trend remains negative.
The bottom line is that Solventum's Q3 looks worse on paper than it was in practice. Normalized growth held near 4%, gross margins expanded, the riskiest separation milestones are largely behind it, and a known 2027 margin headwind has been removed. But a whisper miss, a guidance raise that only matched expectations, and an unquantified HIS dilution give investors reason to wait for the March 2027 Investor Day before pricing in the next leg of the story.
Read our earnings preview for Solventum Corporation: https://www.earningswhispers.com/article/SOLV/22384
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-19 | |
| Oct-15 | |
| Sep-02 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 | |
| Jul-28 | |
| Jul-21 |
