Shoulder Innovations Beats On The Bottom Line And Raises Again, But Sharp Growth Deceleration Shifts The Debate
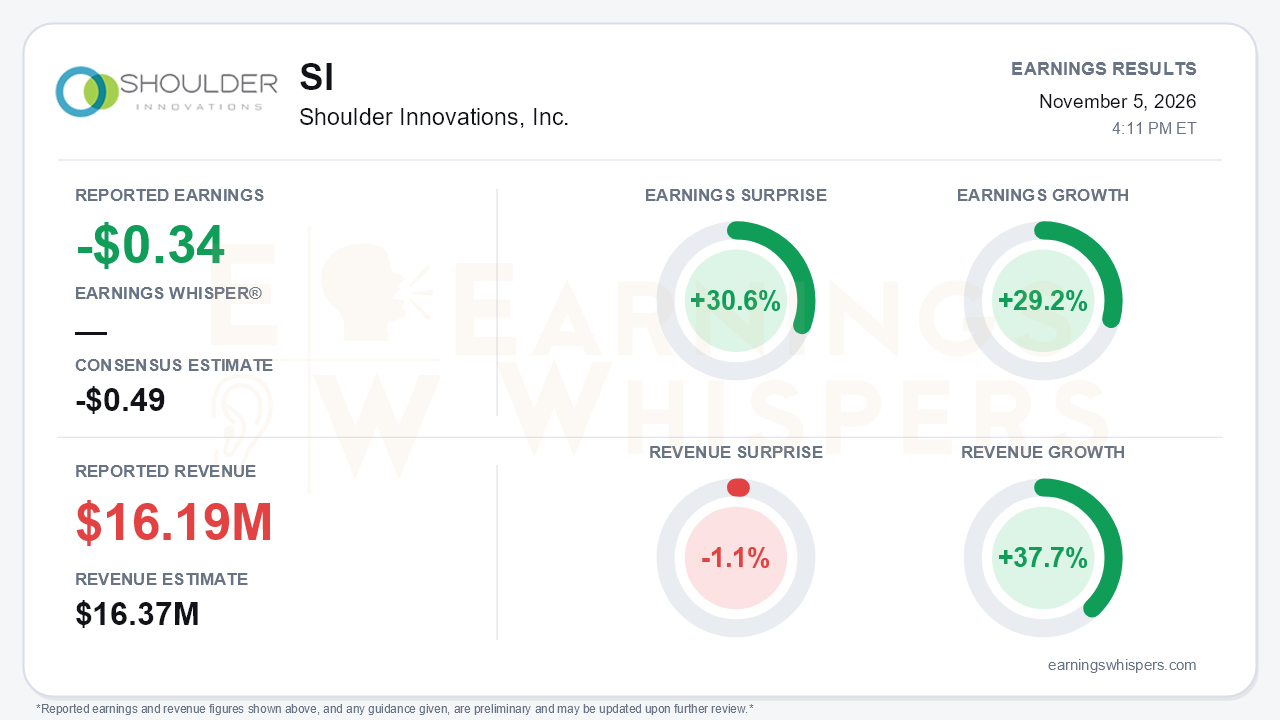
Shoulder Innovations (NYSE: SI) delivered the headline investors usually reward: a third-quarter loss of $0.34 per share, 30.6% better than the -$0.49 consensus, and a third straight increase to full-year revenue guidance. Earnings improved 29.2% from a year ago. The top line tells a less comfortable story. Revenue of $16.19 million rose 37.7% but missed consensus by 1.1%. It was also down sequentially from $17.2 million in the second quarter, and growth decelerated sharply from 65% in Q1 and 56% in Q2. That is the central tension. The margin and cost story is improving, while the volume engine that justified the growth premium slowed noticeably.
The quality of the EPS beat deserves scrutiny. GAAP operating loss was essentially unchanged at $7.6 million versus the year-ago quarter, as higher gross profit was absorbed by a 14% rise in SG&A and a 107% jump in R&D tied largely to the InSet Neo robotic platform. The narrower net loss of $7.0 million, versus $8.7 million, reflects two non-operating factors: the absence of prior-year fair-value charges on convertible notes and $574,000 of interest income on IPO proceeds. The per-share comparison is further flattered by a weighted share count of 20.8 million, up from 13.6 million. The genuine operating improvement shows up elsewhere. Gross margin expanded for a fourth consecutive quarter to 78.5%, up from 78.3% in Q2 and 76.2% a year ago, helped by a 2% rise in average selling price to $7,616 and cost reductions. Adjusted EBITDA loss narrowed to $5.5 million from $8.0 million in Q2. SG&A also fell sequentially to $17.1 million from $20.1 million, aided by lower legal costs.
The call explained the volume slowdown but did not fully dispel it. Implant systems rose 34% to 2,126, versus roughly 50% growth and 2,238 units in Q2. Management attributed the softness to more pronounced summer seasonality among tenured core surgeons than in Q3 2025, even as new surgeon additions ran ahead of plan. Other signals were less reassuring:
- **Pricing:** Management flagged a growing ambulatory surgery center mix that brings modestly lower pricing and more sophisticated purchasing.
- **Market health:** Management gave a guarded answer when asked about the health of the reconstruction market and declined to call it.
- **Guidance:** The latest raise was only $1 million at each end, to $68 million to $70 million. That compares with a $2 million to $3 million step-up earlier in the year, and the new range was merely in line with estimates. With year-to-date growth at 52%, the full-year guide implies Q4 revenue of roughly $17.9 million to $19.9 million, or about 24% to 38% growth. At the low end, that is another meaningful step down.
The product pipeline remains the strongest part of the bull argument. InSet Go completed its first cases on schedule, and the N-22 humeral head received FDA clearance. The ALM Ortho complex-revision partnership treated its first patients, with more meaningful revenue expected in 2027. The Catalyst OrthoScience patent settlement removes a legal overhang and its expense. Management said InSet Neo development is running ahead of internal plans, with an FDA submission still targeted for the first half of 2027. Favorable CMS final rules and a registry now near 900 patients add support. Bears have legitimate ammunition as well. The Inset Clutch limited release slipped from Q3 2026 to Q1 2027. Q4 cash burn is now expected to rise moderately, and SG&A as a percentage of revenue is guided higher, reversing the Q2 call's expectation of a Q4 decline. Cash and marketable securities stood at $92.3 million, down from $99 million at the end of Q2 and about $124 million at year-end 2025. That remains ample but is a figure investors will track as robotics spending ramps.
Investor expectations had already soured before the print. Earnings Whispers sentiment swung from a positive 0.48 after the prior report to a negative 0.63 heading into this one, a substantial reversal. Price action tracked that shift unevenly. Shares peaked at $23.32 in mid-August, then slid to $16.56 by late September. They rebounded to $21.01 ahead of the report, still 8.2% below the opening price after the August release and nearly 10% below the quarter's high. The market setup is therefore more complicated than the EPS surprise implies. A stock that recovered roughly 27% off its low entered the report with skeptical sentiment, and this quarter's growth data offer that skepticism some fresh support.
The bottom line is that Shoulder Innovations is executing well on margins, cost control and product cadence, but the story has shifted from hypergrowth to decelerating growth. The EPS beat leaned heavily on non-operating items and a larger share base, revenue slipped sequentially and missed, and the guidance raise was modest. Q4 will test whether the Q3 slowdown was seasonal or the start of a lower growth trajectory, along with the progress of the 2027 product catalysts.
Read our earnings preview for Shoulder Innovations, Inc.: https://www.earningswhispers.com/article/SI/22379
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-24 | |
| Oct-15 | |
| Oct-08 | |
| Sep-10 | |
| Sep-09 | |
| Sep-08 | |
| Sep-01 | |
| Aug-14 | |
| Aug-12 | |
| Aug-10 | |
| Aug-07 |
