Sweetgreen Beats As October Comps Turn Positive, But The Margin Repair Is Still Ahead Of A Stock That Already Doubled
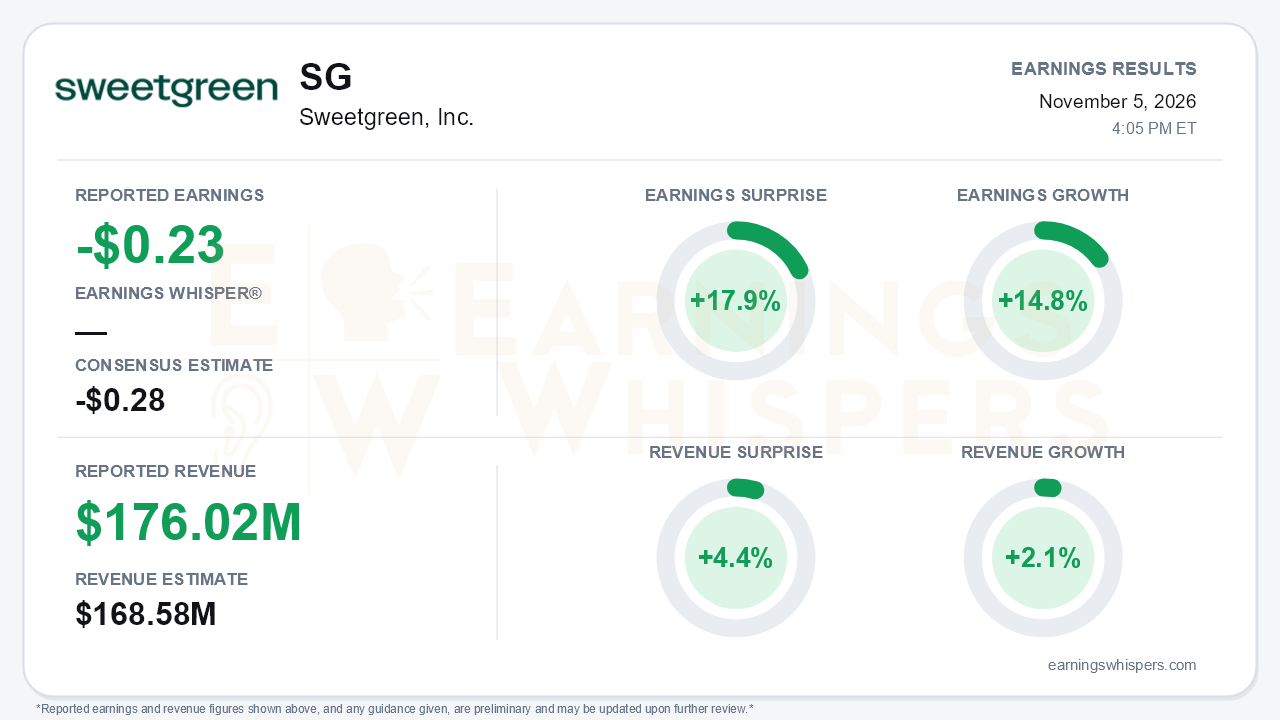
Sweetgreen's third quarter was a beat on the numbers, but the real news was the turn in traffic. The company reported a loss of $0.23 per share on the Earnings Whispers basis, against a consensus of -$0.28. That is a 17.9% surprise and a 14.8% improvement from a year ago. The GAAP net loss was $0.26 per share, down from $0.31. Revenue rose 2.1% to $176.0 million and beat expectations by 4.4%. More important, management said comparable sales improved through the quarter and turned positive in October, at roughly +5% with about +4% transaction growth. It also guided the fourth quarter to about +4% comps, its first positive quarterly comp outlook in the past year of calls. That is the central tension. The top line is inflecting, while the profit line has not yet followed.
The quality of the beat deserves scrutiny. Most of the year-over-year improvement in the GAAP loss came from below the restaurant level:
- General and administrative expense fell to $27.6 million from $30.9 million, largely on $2.5 million less stock-based compensation.
- Impairment and closure costs were roughly halved.
Restaurant operations moved the other way. Same-store sales fell 6.4%, with traffic down 4.9% and mix down 2.1% as customers traded into lower-priced wraps. Restaurant-level margin dropped 270 basis points to 10.4%. Labor rose to 30.5% of sales and other operating costs climbed to 19.9%. Adjusted EBITDA worsened to a $6.8 million loss from $4.4 million. Average unit volume slid to $2.47 million from $2.77 million.
The balance sheet also needs a careful read. Year-to-date GAAP net income of $68.8 million is almost entirely the $160.5 million gain from the Spyce sale, part of it paid in $86.4 million of Wonder preferred stock. Operating cash burn widened to $28.5 million year to date. Cash fell to $119.8 million from $142.6 million in the second quarter.
The call did preserve a credible recovery story. Management framed the third-quarter traffic decline largely around the cyclosporiasis outbreak, which it said cost about 500 basis points. On that view, October's rebound reflects demand returning rather than price. Supporting signals included:
- price-value complaints at a three-year low;
- loyalty redemptions up 50% after the September app relaunch;
- food costs improving to 28.8% from 29.8% in the second quarter.
Full-year guidance was raised from the reduced second-quarter outlook:
- comps to about -5.5%, from -8% to -7%;
- restaurant-level margin to 11.0%-11.5%, from 10.5%-11.0%;
- adjusted EBITDA to a loss of $20 million to $23 million, from $23 million to $27 million.
Management also put numbers on its 2027 margin levers: about 150 basis points of food-cost savings, roughly 200 basis points of labor opportunity over time, and an underlying margin baseline near 14%. Near-term catalysts include a plates relaunch aimed at dinner, which is about a third of sales, a Create Your Own pricing test likely to roll out in early 2027, and new hires for a chief people officer and an executive chef. The tone was markedly more confident.
Bears still have legitimate ammunition. Even raised, fiscal 2026 targets sit far below the original outlook. That guide called for comps of -4% to -2%, a 14.2%-14.7% restaurant margin and positive adjusted EBITDA. Unit growth was cut again, to about 10 net new restaurants this year from roughly 15 originally, with 2027 openings expected at about half that level. Margin pressures are also building:
- The new head coach pay program, worth more than $200,000 for top leaders, is a roughly 25-basis-point margin drag in 2027.
- The fourth quarter carries about 60 basis points of one-time costs.
- The 3% September price increase and Create Your Own pricing could test hard-won value perception, or dilute margin if traffic fails to offset.
The market setup is more complicated than the surprise implies. Investor sentiment swung decisively, from -0.30 before the August report to +0.14 now, a shift from clearly negative to modestly positive. The stock has moved even more forcefully. Shares opened at $5.43 after the prior report, set their inter-earnings low of $5.00 that same day, and rallied 117% to $11.80. That left them just 1.3% below a 52-week high of $11.95 set on November 2. Price and AVWAP trend readings are positive, though momentum has softened. In short, investors bought the October inflection before management confirmed it.
The bottom line is that Sweetgreen delivered what turnaround skeptics were not positioned for: positive traffic, a positive fourth-quarter comp guide and raised full-year targets. The quarter itself still showed shrinking restaurant margins, a wider EBITDA loss, ongoing cash burn and a slower growth pipeline. With the stock having more than doubled into the report, the next test is whether positive comps turn into the margin recovery management has quantified for 2027.
Read our earnings preview for Sweetgreen, Inc.: https://www.earningswhispers.com/article/SG/22378
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 |
Sweetgreen Sees Milder Same-Store Sales Decline Following Rebound From Cyclospora Outbreak
SG
The Wall Street Journal
|
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-27 | |
| Oct-23 | |
| Oct-22 | |
| Oct-20 | |
| Oct-12 | |
| Oct-08 | |
| Oct-08 | |
| Oct-02 |
