RenovoRx Posts First $1 Million Quarter And Misses On EPS As Sequential Growth Slows And Q4 Targets Get Harder
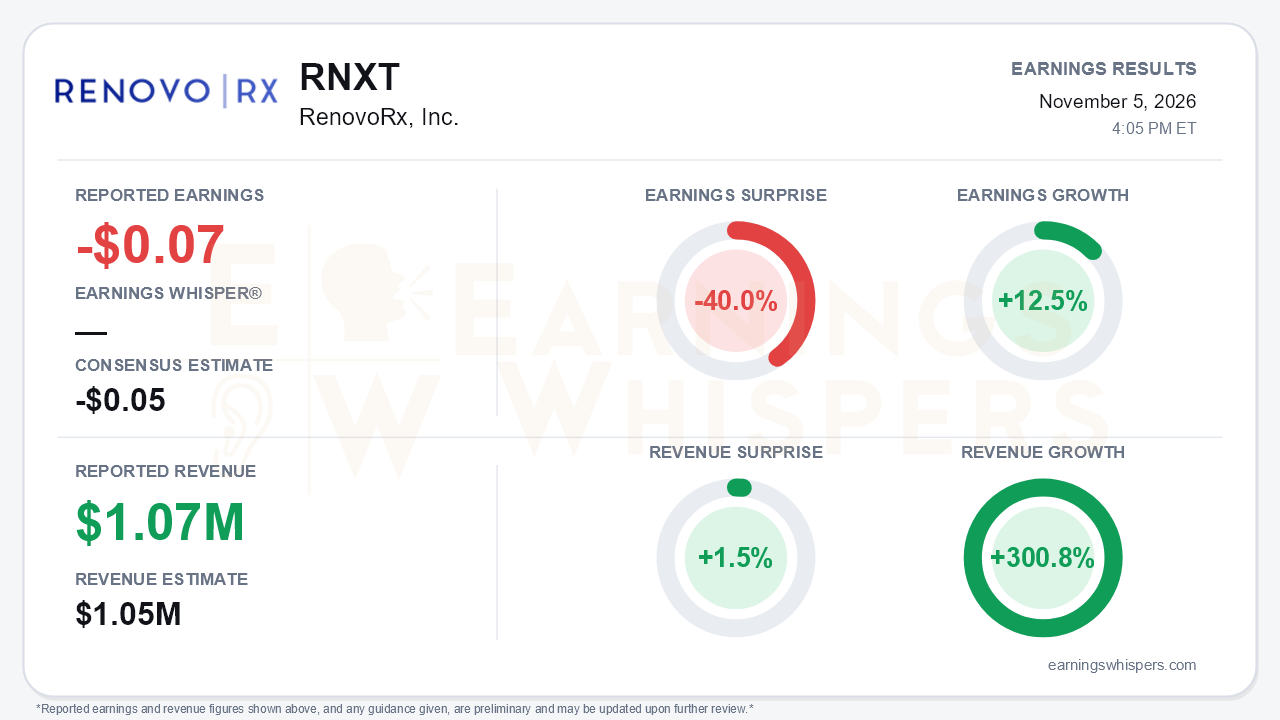
RenovoRx (NASDAQ: RNXT) delivered its first million-dollar quarter, but the more important story is the shape of the growth curve. Third-quarter revenue reached a record $1.07 million, up 300.8% year over year and 1.5% above the $1.05 million consensus. The company reported a loss of $0.07 per share against a consensus estimate of a $0.05 loss, a 40.0% earnings miss, although Earnings Whispers calculates earnings growth of 12.5% versus the prior year. Management reaffirmed full-year revenue guidance of $3.75 million to $4.25 million. The headline growth rate is spectacular, but sequential momentum is fading quickly, and that is the central tension in the report.
The quality of the quarter deserves scrutiny on both the revenue and cost lines. Revenue rose only about 17% from the second quarter's $909,000. Sequential growth was roughly 136% in Q1 and 61% in Q2, so the curve is bending sharply. Reported gross margin slipped to 82.4% from about 84% in Q2, 85.1% in Q1, and 88% in Q4 2025. The company attributed the dip to converting three TIGeR-PaC trial devices at one site to commercial use at zero gross margin, with underlying margin closer to 85%. Management expects more of these conversions, so reported margins may stay diluted. On the expense side, R&D fell to $1.2 million from $1.7 million as trial enrollment wound down, while SG&A climbed to $2.9 million from $1.7 million to fund the commercial build. Operating loss was essentially flat year over year at $3.2 million and modestly better than Q2's $3.4 million. The GAAP net loss widened to $3.6 million, partly because of a $487,000 non-cash warrant-liability charge. GAAP loss per share held at $0.08 only because the weighted share count rose about 32%.
The call offered a credible commercial narrative with softer edges. Active cancer center customers rose to 26 from 21, after rising from 16 to 21 the prior quarter, and the total funnel grew to more than 65 centers from 63. However, the pipeline beyond active sites was essentially flat at 40-plus versus 42. Center additions have run at a steady five per quarter, yet the year-end target of 36 requires about ten in Q4. Management's wording shifted from "meet or exceed" last quarter to "remain confident in ability to meet." Reaffirmed guidance, combined with nine-month revenue of $2.54 million, implies Q4 revenue of roughly $1.2 million to $1.7 million. That is a reacceleration the Q3 trajectory does not yet demonstrate, and management did not explicitly say Q4 revenue would exceed Q3, as it had done for forward quarters on prior calls. The sales organization is now fully staffed, with a VP and five regional managers. That removes a hiring excuse but also raises the bar for productivity.
The forward catalysts are real, if mostly longer-dated. TIGeR-PaC reached full enrollment in August, with top-line overall survival data expected in the second half of 2027. The first patient was treated in the University of Vermont's neoadjuvant investigator-initiated trial, which pushes TAMP upstream of locally advanced disease. A sarcoma case marked the first commercial use outside pancreatic cancer. Two peer-reviewed publications and a new dual-occlusion catheter patent allowance round out the evidence base. Management also framed new pancreatic cancer therapies, such as RAS inhibitors, as complementary to local delivery rather than competitive. Bears have legitimate ammunition on funding, though. Cash rose to $10.4 million only because of $3.5 million in warrant exercises. The company guided to a runway into the second half of 2027, which overlaps the pivotal readout. In addition, the $5 million quarterly break-even run rate and Q4 2027 break-even target discussed last quarter were not repeated.
Investor expectations had warmed considerably before the report. Earnings Whispers sentiment swung from slightly negative at -0.08 to a clearly positive +0.36. Price action tells a more complicated story. Shares closed at $1.31 ahead of the release, up 17.0% from the $1.12 open after the August report. However, they sit 49.4% below the $2.59 52-week high set on September 2, and only 20.2% above the October 14 low of $1.09. Most of the late-summer spike has been surrendered. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive, while AVWAP remains negative, consistent with a stock that has not held its gains.
The bottom line is that RenovoRx is executing on adoption, with record revenue, steady center additions, and an expanding clinical footprint. However, the quarter showed decelerating sequential growth, diluted margins, an earnings miss, and softer language on year-end targets. Fourth-quarter center activations and revenue now carry outsized weight. Without a visible reacceleration, the improved sentiment and guidance reaffirmation rest on a commercial ramp that is losing speed while the cash runway and the TIGeR-PaC readout converge in 2027.
Read our earnings preview for RenovoRx, Inc.: https://www.earningswhispers.com/article/RNXT/22374
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-28 | |
| Oct-22 | |
| Oct-07 | |
| Oct-01 | |
| Sep-02 | |
| Sep-02 | |
| Aug-25 | |
| Aug-21 | |
| Aug-20 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 |
