BRC Group's Babcock & Wilcox Loss Turns Q3 Into A Liquidity Test As Core Earnings Stall
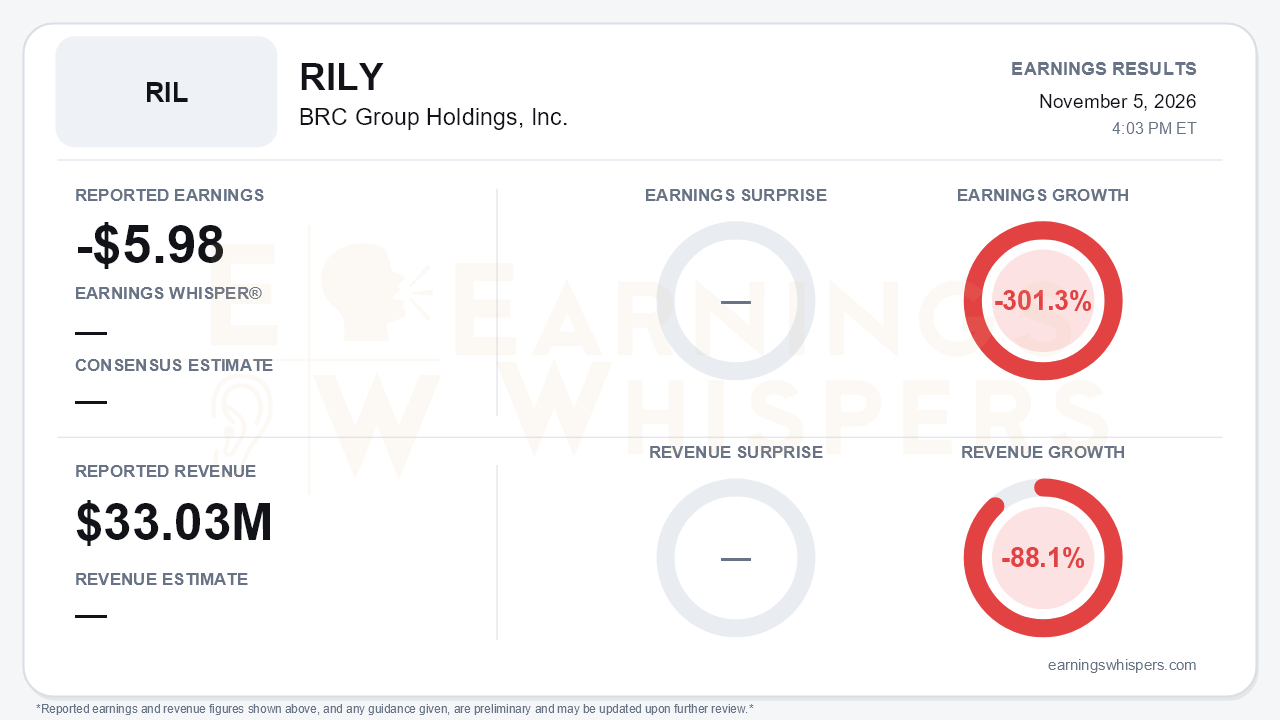
BRC Group Holdings (NASDAQ: RILY) reported a loss of $5.98 per share from continuing operations for the September quarter, on total revenue of $33.03 million. Earnings fell 301.3% from a year ago and revenue dropped 88.1%. Including discontinued operations, the GAAP diluted loss was $6.04 per share, or $243.0 million available to common shareholders. That compares with $2.97 per share of continuing-operations profit a year earlier and net income of $18.5 million in the second quarter. No consensus estimate was available, so this is not a beat-or-miss story. It is a balance-sheet story. A $226.7 million pre-tax loss on the Babcock & Wilcox stake erased the momentum management was touting three months ago. That shifted the investor debate from earnings recovery to near-term liquidity.
The headline loss is mostly mark-to-market, but the operating results offer limited cover. Operating Revenues, which strip out investment swings, fell to $161.3 million from $244.1 million a year ago. Operating Adjusted EBITDA collapsed to $2.9 million, against $54.9 million in the prior-year quarter, $66 million in Q2 and $34.6 million in Q1. The company attributes $17.4 million of the drop to reversing a Q2 unrealized gain on structured equity financings and a net markdown of the SpaceX carried interest. Even adding that back, core profitability fell well below recent run rates.
Management calls the year-to-date figure of $103.3 million, up from $93.2 million, "on plan." However, that total leans on carried-interest gains that have now partially reversed. A $14.6 million impairment on GA Group and continuing material weaknesses add to the sense that the quality of reported earnings deserves scrutiny.
The call showed a business split in two:
- **Financial businesses weakened.** Capital Markets posted a $120.0 million segment loss on $125.7 million of trading losses. Client capital raised slid to about $4.5 billion from $8.5 billion in Q2 and roughly $10 billion in Q1. ATM and underwriting fees fell $28.9 million year over year as small-cap issuance dried up.
- **Bright spots in banking and wealth were too small to offset that.** M&A and advisory fees rose $6.3 million, and sole/lead-managed volume is up 20% year to date. Wealth advisory fees grew 11% and AUM reached $12.8 billion. Even so, the Wealth segment swung to a $3.7 million loss, and the advisor count slipped to 181 from 190 in Q1.
- **Communications kept improving profits on shrinking sales.** Combined segment income rose to $13.2 million in the quarter even as revenue declined in all four units. Management says the group is tracking ahead of budget.
- **Consumer Products went the wrong way.** Targus's loss widened to $4.3 million, and the earlier near-break-even framing was dropped.
The deleveraging narrative now comes with a major caveat. Total debt fell $291.7 million year to date to $1.14 billion, and net debt of $562.3 million is still 10% below year-end. But net debt nearly doubled from $285 million at Q2, because the investment portfolio that offsets borrowings shrank. Cash fell to $145.7 million, with Babcock & Wilcox still carried at $160.3 million.
The call laid out a fourth-quarter funding gap:
- **Needs:** more than $200 million, mainly the $164 million of Riley G notes due December 31 plus the Sangoma equity contribution.
- **Resources:** roughly $180 million of pro forma cash.
- **The bridge:** management is relying on up to about $50 million of expected balance-sheet realizations, including SpaceX share deliveries.
The GA Group sale helps only modestly. Most of the $62.3 million went to repaying Oaktree, and an incremental $26.5 million term loan was added, for $36.5 million of net liquidity. Beyond year-end, roughly $800 million of 2028 maturities have no defined refinancing plan.
The forward catalysts are real but carry their own risks. Sangoma, at a $203.7 million enterprise value, is expected by management to more than double communications revenue and add $35-40 million of EBITDA including synergies, with a close targeted for early 2027. It also brings $140.8 million of incremental debt at the telecom subsidiaries and roughly 4% shareholder dilution. That dilution comes on top of a share count that has already climbed to 40.2 million from 30.6 million at year-end. Other potential supports include:
- full ownership of B. Riley Securities and its integration with Wealth;
- $5-10 million of guided 2027 professional-fee savings;
- a $92 million venture book with possible 2027-28 realizations.
Management's tone shifted from Q2's momentum and deleveraging message to defending liquidity and calling the platform "made for difficult markets."
No investor sentiment or current price data was available for this review. The shares opened at $7.06 after the August report. In the near term, the market reaction will likely hinge less on the Q3 loss than on whether the December note maturity is met cleanly through the planned realizations.
The bottom line is that BRC Group's quarter was defined by investment-portfolio risk rather than operations. The operating core also failed to provide a cushion. Communications cost discipline and the Sangoma deal preserve a credible cash-flow story, and debt is lower than at year-end. However, collapsing capital-markets activity, a renewed Babcock & Wilcox concentration hit, and a funding plan that depends on asset sales give bears legitimate ammunition. Until the December maturity is behind it and the 2028 refinancing path is clearer, liquidity rather than earnings power is the variable that matters.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-22 | |
| Oct-20 | |
| Oct-12 | |
| Sep-28 | |
| Sep-28 | |
| Sep-28 | |
| Aug-28 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 |
