Rigel Misses On EPS As VEPPANU Launch Spending Compresses Margins, While TAVALISSE Slowdown Clouds A Strong Debut
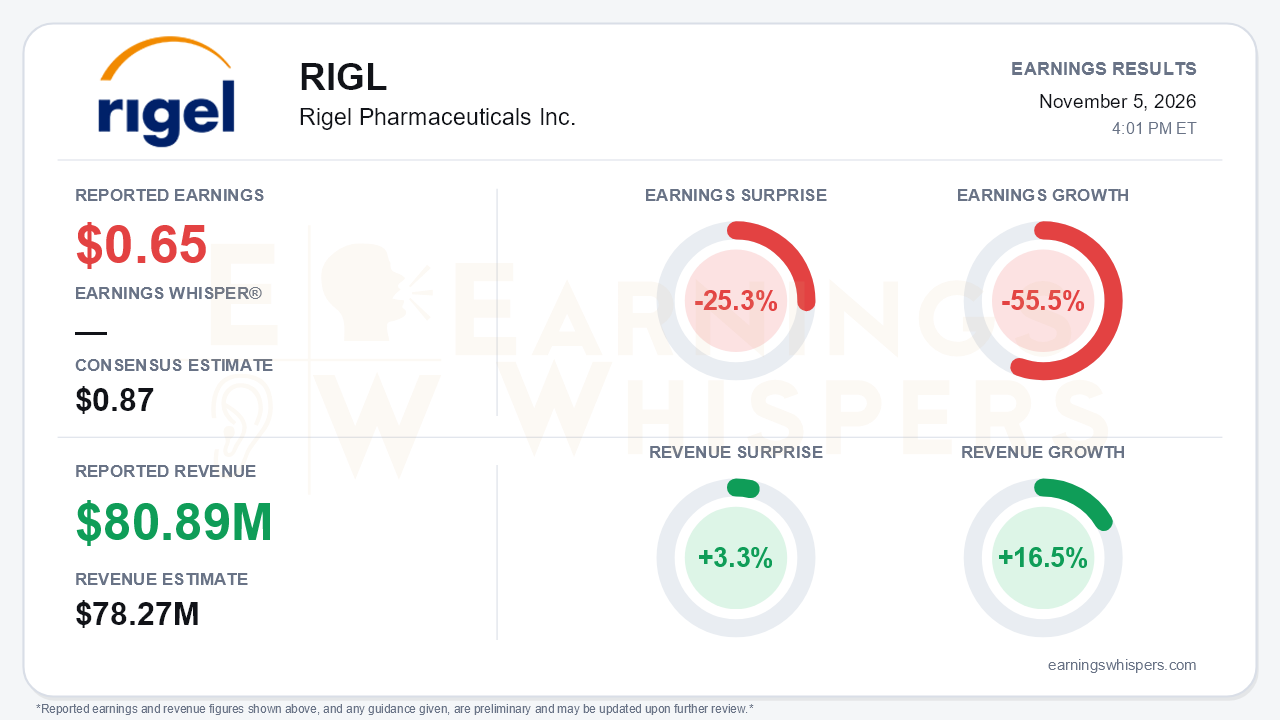
Rigel Pharmaceuticals delivered a quarter in which revenue beat but earnings missed, and the gap between the two explains the quarter. Third-quarter earnings of $0.65 per diluted share missed the $0.87 consensus by 25.3% and fell 55.5% from a year ago. Revenue of $80.89 million beat the $78.27 million consensus by 3.3% and grew 16.5% year over year. The top line got a lift from the debut of VEPPANU (vepdegestrant), but the cost of building that franchise landed squarely on the bottom line. Meanwhile, the legacy portfolio that funds the effort is losing momentum. That is the central tension: a promising launch layered on top of a base business that is decelerating.
The quality of the earnings decline deserves some nuance. Total costs and expenses jumped to $63.8 million from $41.0 million a year ago.
- Research and development more than doubled to $18.3 million on R289 and vepdegestrant programs.
- Cost of product sales more than doubled to $10.8 million, reflecting royalties and amortization.
- SG&A rose to $34.7 million on launch spending.
Pretax income fell to $17.4 million from $27.6 million. Part of the steep EPS decline, however, reflects taxes rather than operations. The prior-year quarter carried a small tax benefit, while this quarter booked a $4.2 million provision. Sequentially, net income slipped to $13.2 million from $17.3 million in the second quarter. Contract revenue also dipped to $8.6 million from $11.7 million, as the prior quarter included a $4 million milestone. Management still expects positive net income for full-year 2026.
The call made clear that the growth engine is changing hands. Net product sales hit a record $72.3 million, up 13%, and up from $67.0 million in Q2 and $54.9 million in Q1. Beneath that, the drivers diverged:
- **TAVALISSE:** Growth decelerated sharply to 3% ($46.0 million), from 18% in Q2 and 31% in Q1, and sales declined sequentially. This was the case even though management described a record demand quarter.
- **GAVRETO:** Sales fell 11% to $9.8 million.
- **REZLIDHIA:** The bright spot in the base business, up 20% to $9.9 million, with demand up roughly 10% sequentially.
Against that backdrop, VEPPANU's early metrics were strong:
- $6.6 million in roughly six weeks, which management characterized as mostly demand rather than stocking.
- More than 100 patients and clinics shipped, with most early patients refilling.
- An 88% prior-authorization approval rate and a four-day median time to fill.
- 70-80% of business coming from community settings.
Management's tone shifted from deal-making aspiration to execution confidence. It went as far as calling VEPPANU potentially the company's largest product.
Guidance reflects the same split. Total 2026 revenue guidance was narrowed upward to $290-295 million from $285-295 million, the second consecutive step-up from the original $275-290 million. That improvement, however, comes from contract revenue, now about $35 million versus about $30 million previously. Net product sales guidance excluding VEPPANU was trimmed at the top to $255-260 million from $255-265 million, a range held since the start of the year, with management citing gross-to-net and inventory variables. Investors also lose visibility:
- VEPPANU will not be guided until 2027.
- Detailed launch metrics will no longer be disclosed.
That makes the next several quarters harder to underwrite just as the launch becomes the core of the thesis.
The balance sheet and pipeline add both catalysts and risks. Cash and short-term investments stood at $99.3 million at quarter end, down from $155.0 million at year-end 2025 after the $70 million VEPPANU upfront. Further milestones and up to $40 million in development contributions are still owed. On the pipeline side:
- R289, the dual IRAK1/4 inhibitor, gets an ASH oral presentation on December 12 featuring first dose-expansion efficacy data in lower-risk MDS.
- Recommended Phase 2 dose selection is expected by year-end, with a registrational trial targeted for 2027.
- Registrational design has not yet been aligned with the FDA.
- The heavily pretreated patient population complicates comparisons with the roughly 40% transfusion-independence rates of luspatercept and imetelstat.
The market had been leaning into the story ahead of the print. Shares rose 20.7% from the $42.48 open after the prior report to $51.29. That left the stock 2.5% below a 52-week high of $52.61 set October 30 and about 34% above the inter-earnings low hit the morning after the August report. Price, momentum, and AVWAP trend readings were all positive. Investor sentiment improved meaningfully, from -0.44 to -0.24, but remained negative. That combination suggests a stock that ran on launch optimism while a skeptical base remained unconvinced. Entering near the top of its range, the shares carry less cushion for an EPS miss and softer base-business guidance.
The bottom line is that Rigel's quarter was better than the earnings miss implies but less clean than the revenue beat suggests. VEPPANU's launch metrics are genuinely encouraging, and the margin compression is largely deliberate investment. However, TAVALISSE's abrupt deceleration, a trimmed base-product outlook, reduced launch disclosure, and a thinner cash cushion give bears legitimate ammunition. With the stock near its highs, the December R289 data and evidence that VEPPANU can offset slowing legacy products now carry most of the weight.
Read our earnings preview for Rigel Pharmaceuticals Inc.: https://www.earningswhispers.com/article/RIGL/22464
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-29 | |
| Oct-29 | |
| Oct-19 | |
| Oct-15 |
Big Pharma Is Pouring Billions Into a New Class of 'Protein Degrader' Drugs
RIGL
The Wall Street Journal
|
| Oct-02 | |
| Sep-02 | |
| Aug-14 | |
| Aug-13 | |
| Aug-04 | |
| Aug-04 | |
| Jul-28 |
