Xponential Fitness Misses As Comps Slide To -7.5% And Unit-Growth Guidance Is Cut For A Third Time
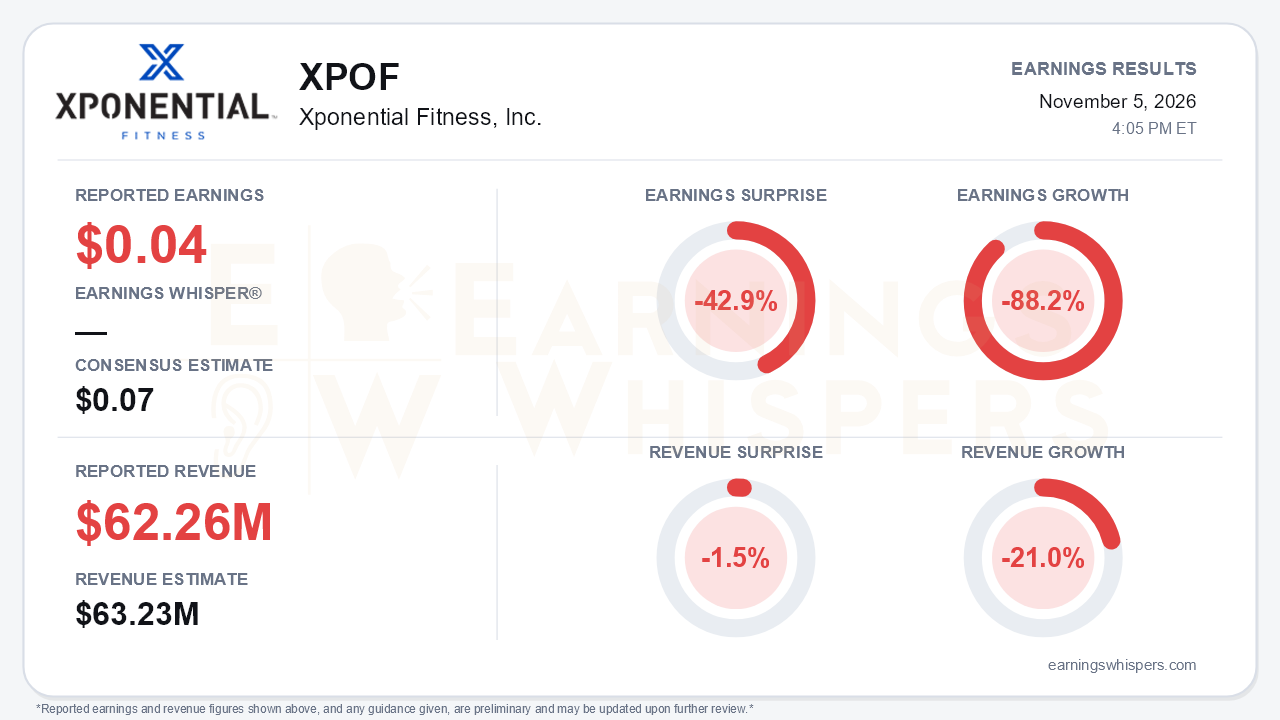
Xponential Fitness reported adjusted earnings of $0.04 per share for the third quarter, missing the $0.07 consensus by 42.9% and falling 88.2% from a year ago. Revenue of $62.26 million declined 21.0% and came in 1.5% below the $63.23 million consensus. The central takeaway is that the problems are no longer confined to the transition costs and legal cleanup of the past year. They are now showing up in the core studio base. Same-store sales worsened for a third straight quarter, North America system-wide sales turned negative, and the unit-growth outlook was cut again. A swing to GAAP profitability and a reaffirmed revenue range do not change that trajectory.
The quality of the quarter deserves scrutiny. GAAP net income was $4.9 million, or $0.10 per share, versus a loss of $6.7 million a year earlier. That improvement owes much to items outside the operating story. The prior-year quarter carried a $17.6 million impairment that did not recur. This quarter also included $3.8 million of acquisition and transaction income tied to changes in contingent consideration. The adjusted figures tell the more honest story. Adjusted net income collapsed to $2.2 million from $19.3 million, and adjusted EBITDA fell 27% to $24.3 million.
The revenue decline was broad:
- Franchise revenue fell 16% on lower termination-related territory revenue, weaker royalties and the 2025 brand divestitures.
- Equipment revenue dropped 42% because fewer studios opened.
- Merchandise revenue nearly disappeared after the shift to an outsourced model.
Costs moved the wrong way at the same time. SG&A rose 14% on financial transaction and legal fees. Quarterly interest expense climbed to $15.2 million from $12.9 million, consuming most of the $19.5 million in operating income.
The call made the deterioration in the base business explicit. Total same-store sales fell 7.5%, compared with declines of 6.8% in Q2 and 6.2% in Q1. Club Pilates, the flagship brand, slipped to -5.6% from -5.0% and roughly -4%. The original plan called for only low-single-digit declines. Run-rate AUV dropped to $634,000 from $668,000. North America system-wide sales fell 2% to $424.3 million after being flat in Q2 and up 2% in Q1. Management also cited industry credit-card data pointing to a third-quarter slowdown in boutique fitness relative to the first half, which makes this harder to dismiss as purely company-specific execution.
The development pipeline is the more troubling longer-term signal. Net new studio guidance was cut to 124-130, from roughly 150 last quarter and 150-170 originally. Management cited tougher real estate for small strip-center sites and stricter site selection. Contractually obligated North America licenses fell to 618, down from more than 690 in Q2 and more than 780 in Q1. That keeps the reiterated goal of more than 2,000 Club Pilates locations within five years looking aspirational.
The adjusted EBITDA outlook was trimmed at the top to $91-$94 million, versus $91-$97 million in Q2 and an original $100-$110 million. Revenue guidance of $250-$260 million and system-wide sales guidance of $1.70-$1.75 billion were held, but only after being cut last quarter.
There are genuine green shoots, though they are early:
- The redesigned Club Pilates website, launched in late September, drove a double-digit percentage lift in lead submissions and first-class conversion.
- AI-driven SEO content, a restructured Meta-based local marketing platform and an influencer platform are now live, and the website overhaul moves to Pure Barre next.
- International development is a relative bright spot, with 19 net adds in the quarter and 58 licenses sold, up from 53 in Q2.
- Legal cash drag is fading. Only about $3.4 million of franchisee settlement payments remain for Q4, versus $11.4 million expected for the second half as of the Q2 call.
- New CFO Jennifer Rue is launching a cost-structure review.
The balance sheet limits the margin for error. Cash stood at $27.2 million against $521.1 million of long-term debt, nine-month operating cash flow was negative $21.1 million, and the $10 million revolver draw remains outstanding despite earlier plans to repay it. The strategic alternatives review, which could include a sale, continues with no update.
Investor sentiment barely moved. It remained firmly negative, edging from -0.51 to -0.48 ahead of the report. Shares closed at $4.53 on the eve of the release, down 8.5% from the open following the August report. The inter-earnings range was violent: the stock peaked at $5.78 in late August, then fell to a 52-week low of $3.57 on September 18. It entered the print 27% above that low and nearly 22% below the high. Price, momentum and AVWAP trend readings are all negative, consistent with a stock the market has been treating cautiously and one where the strategic review likely provides some speculative support.
The bottom line is that Xponential's quarter offered encouraging digital marketing data and a shrinking legal overhang, but the core metrics that drive franchisor economics — comps, AUV, system-wide sales and the license pipeline — all weakened again. Until those trends stabilize, the investment case rests less on the operating turnaround and more on the outcome of the strategic review and the company's ability to manage a heavily levered balance sheet.
Read our earnings preview for Xponential Fitness, Inc.: https://www.earningswhispers.com/article/XPOF/22417
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-28 | |
| Oct-22 | |
| Oct-12 | |
| Sep-16 | |
| Sep-08 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-23 | |
| Jul-15 | |
| Jul-15 | |
| May-28 |
