Wynn Resorts Misses Badly As Las Vegas Margins Slide And Macau Demand Cools; Management Leans On October And 2027 Pacing
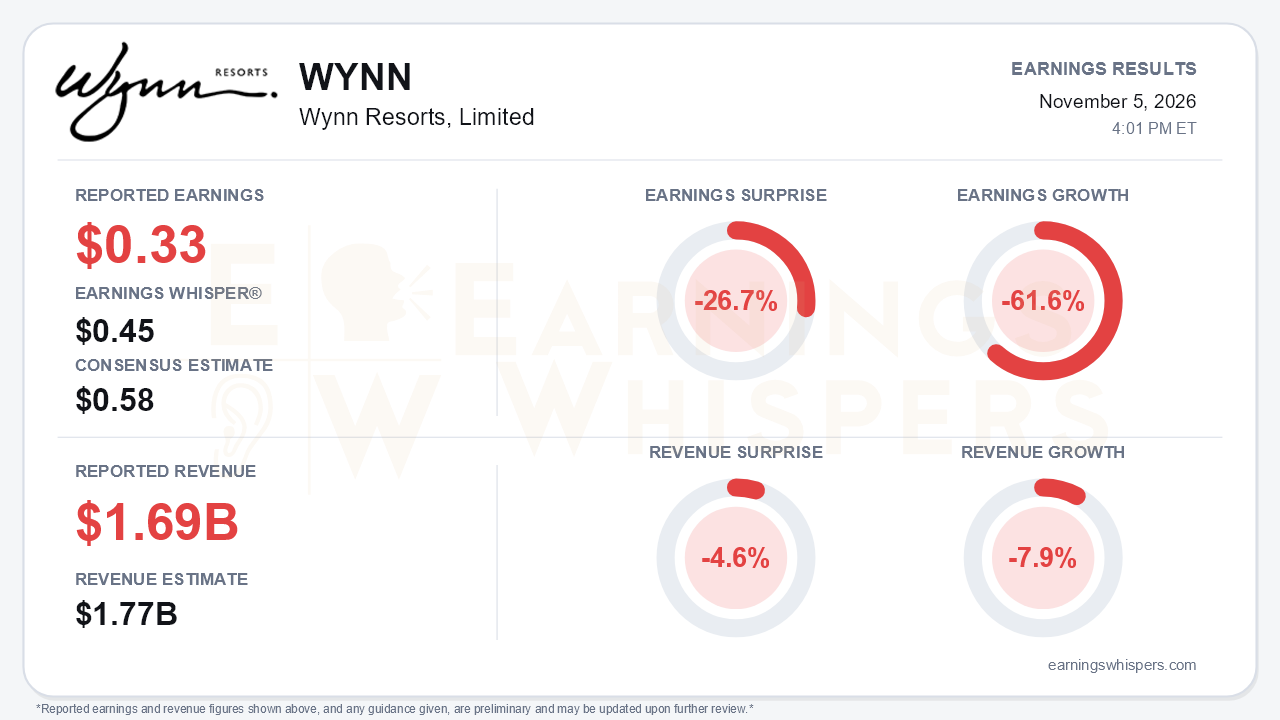
Wynn Resorts delivered a clear third-quarter miss. Adjusted earnings were $0.33 per share against a $0.58 consensus and a $0.45 Earnings Whisper number, a 26.7% shortfall. Revenue of $1.689 billion missed the $1.77 billion consensus by 4.6%. Earnings fell 61.6% year over year and revenue declined 7.9%, a sharp reversal from a nine-month period in which revenue was still running ahead of 2025. Every operating market posted lower revenue and lower Adjusted Property EBITDAR. Consolidated EBITDAR fell to $464.2 million from $570.1 million. On a GAAP basis, diluted EPS dropped to $0.17 from $0.85, weighed down by $22.0 million of property charges. Management attributed part of the shortfall to bad luck, and part of it was. The central tension is that luck explains only part of the miss.
Las Vegas shows that distinction most clearly. Table hold of 18.9% fell well below the property's expected 22% to 26% range. Management put the cost of low hold at roughly $24 million, versus $3.6 million in the second quarter. Even after adjusting for hold, Las Vegas EBITDA fell about 10% year over year. The sequential trend is the bigger concern:
- First quarter: $232.5 million at a 35.1% margin
- Second quarter: $215.2 million at a 33.5% margin
- Third quarter: $158.8 million at a 27.6% margin
Table drop also declined 9.1% from a year earlier. Room pricing held up better, with ADR up 3.4% and RevPAR up 3.2%, and daily operating costs rose only 0.4% year over year. Cost discipline and rate resilience are genuine positives, but they could not offset weaker casino volume.
Macau is where the quality of the quarter deserves the most scrutiny. Wynn Palace and Wynn Macau both ran VIP hold above their 3.1% to 3.4% expected ranges. Management cited roughly $12 million of net hold benefit for the segment. Despite that, Macau EBITDA slid to $255.3 million at a 27.8% margin, down from $297 million at 29.6% in the second quarter. Underlying volumes explain the decline:
- Mass table drop at Wynn Palace fell 12.9% year over year.
- Mass win stayed nearly flat only because Palace mass hold jumped to 25.8% from 22.6%.
- Management described September as soft and said October volumes faded late in the month.
That is a marked change from the 19% and 5% mass-drop growth cited on the first- and second-quarter calls. Analysts also raised questions about Chinese tax policy and capital controls. In Boston, a strike kept about 1,300 workers out in September, and EBITDAR fell 14.1% year over year. A tentative labor framework is now out for ratification, but management has not yet quantified how a new contract will affect operating costs.
The call's tone shifted noticeably. CEO Craig Billings opened by calling it "a complicated quarter with more headwinds than tailwinds" and spent much of the Q&A rebutting bearish narratives. That is a far cry from the record-setting framing of earlier calls this year. Management still made a credible case for the forward story:
- **Las Vegas near-term:** October drop, ADR and RevPAR all rose year over year, and Formula 1 weekend is pacing ahead of prior years.
- **Las Vegas 2027:** Group and convention bookings are running ahead of both 2026 and 2025 in room nights and rate.
- **Macau:** Construction began on the Theater/Events Center and the Enclave, with 2026 expansion capex held at $350 million to $400 million.
- **Wynn Al Marjan Island:** The UAE project remains on track for a September 2027 opening, with costs described as substantially locked. Remaining equity needs have narrowed to $465 million to $590 million.
Bears still have legitimate ammunition. Regional conflict is slowing ancillary hotel development near Al Marjan, and a decision on the resort's opening format has been deferred to around February. Total liquidity was flat at $4.0 billion, down from $4.7 billion two quarters earlier. Debt stands at $10.73 billion. The September refinancing replaced 5.25% notes due 2027 with 6.875% notes due 2035, extending maturities at a higher cost. Buybacks slowed to $58.1 million from $75 million. The repurchases were made at an average price of $92.61, above the current share price. Wynn Macau did raise its interim dividend to $150 million from $125 million.
The market had already priced in much of this. Shares fell 19.3% from the $102.09 open after the August report to $82.38 heading into earnings. Along the way, the stock dropped from an inter-earnings high of $109.24 to a 52-week low of $70.79 on October 28. Shares enter the report about 16% above that low, recovering somewhat but still in the lower half of the range. Investor sentiment remained negative and weakened modestly, from -0.07 to -0.11. That suggests rising caution rather than capitulation. The price trend and AVWAP readings remain negative, consistent with a stock that has been sold steadily since summer.
The bottom line is that Wynn's miss was not just a hold story. Las Vegas margins have compressed for three straight quarters, Macau earnings fell despite favorable VIP luck, and Boston absorbed a strike with costs still unquantified. Management's case now rests on October trends, 2027 group pace and the Al Marjan opening. That case is plausible, but it is forward-looking. Investors will want evidence that Macau mass volumes stabilize and that hold-adjusted Las Vegas earnings stop declining.
Read our earnings preview for Wynn Resorts, Limited: https://www.earningswhispers.com/article/WYNN/22416
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-06 | |
| Sep-25 | |
| Sep-25 | |
| Sep-23 | |
| Sep-10 | |
| Sep-10 | |
| Aug-31 | |
| Aug-27 | |
| Aug-07 |
