Compass Squeezes Record Q3 Profit From Anywhere Synergies, But An Organic Revenue Decline Guide Shifts Focus To Demand
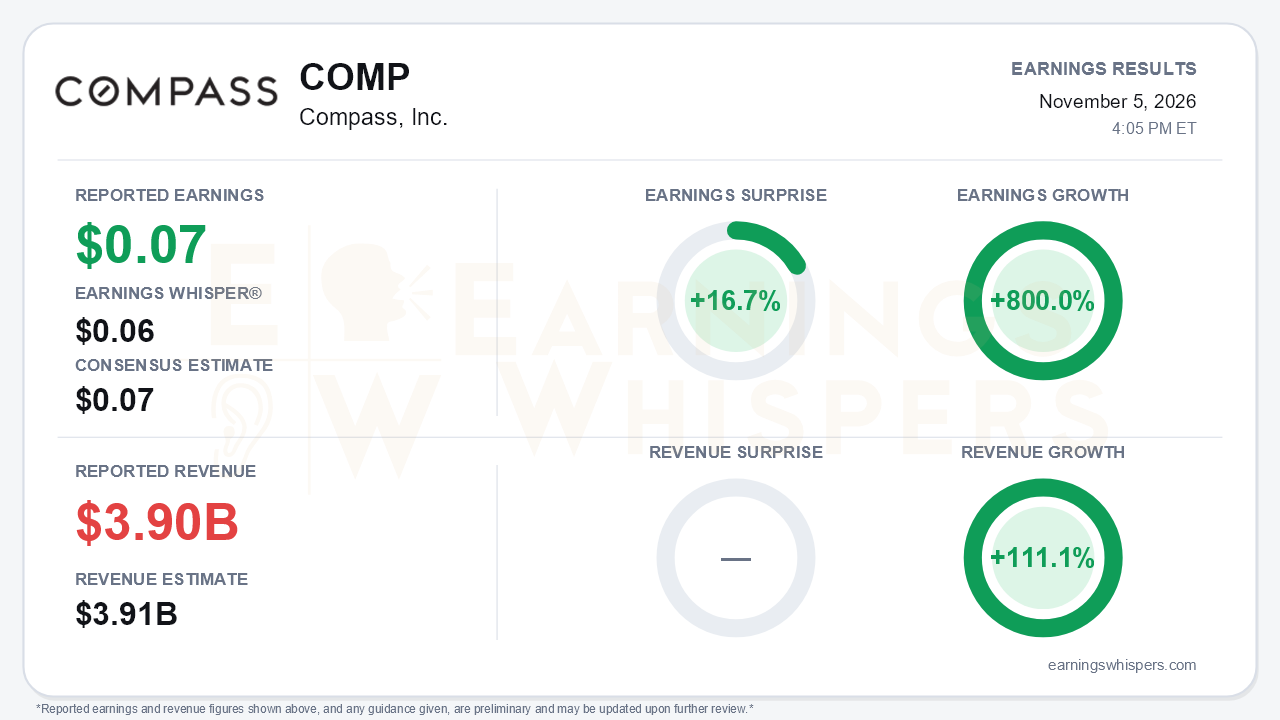
Compass delivered the profit quarter its merger thesis promised, but it also showed that the housing market is starting to work against it. The company earned $0.07 per share on revenue of $3.897 billion. That matched the $0.07 consensus and topped the $0.06 Earnings Whisper number, a 16.7% beat. Revenue came in 0.3% below the $3.91 billion consensus. Year over year, earnings grew 800.0%, a swing from a $0.01 loss to a profit, and revenue grew 111.1%. Both comparisons are inflated by the Anywhere acquisition. The more honest growth figure is the 11.6% pro forma revenue increase, which slowed from roughly 14% in Q2. That is the central tension. Cost discipline produced record earnings and cash just as the top line rolled over, and management's Q4 outlook implies organic revenue falls about 4.5%.
The quality of the profit deserves credit. GAAP net income of $62 million was the first positive third quarter in company history, and unlike the year-to-date figure it was not propped up by taxes. Q3 carried only a $4 million tax benefit, against $400 million for the nine months. Adjusted EBITDA of $306 million cleared the top of the $275-305 million guidance range, and the adjusted EBITDA margin widened to 7.9% from 5.1%. Non-GAAP operating expenses fell sequentially to $676 million from $699 million. Free cash flow reached a record $240 million, up from $180 million in Q2. Cash climbed to $841 million, and net leverage dropped to 2.7x from 3.3x in Q2 and 4.4x when the deal was announced. Two caveats apply:
- The diluted share count rose to roughly 863 million from 566 million.
- Quarterly interest expense jumped to $41 million from $2 million, so the per-share leverage is less dramatic than the dollar figures.
Beneath the headline, operating momentum slowed sharply:
- Organic brokerage GTV growth fell to 7.5% from 16% in Q2.
- Brokerage transactions slipped 0.3%, after rising 7.4% in Q2.
- Franchise GTV growth slowed to 2.3% from 11.7%, and organic franchise transactions fell 3.6%.
- Organic gross agent additions eased to 2,734 from 2,816 in Q2 and 3,503 in Q1.
- Agent retention dipped to 95.1% from 95.5%.
Management's argument is relative. Brokerage GTV beat NAR market data by 680 basis points and transactions beat it by about 150 basis points, extending a long streak of market outperformance. That case is credible. But outperforming a weakening market still means growth is decelerating.
The outlook is where bears have legitimate ammunition. CEO Robert Reffkin acknowledged the market has softened in recent weeks. On the call, management cited 30-year mortgage rates near 7.6% and national pending sales down 15% year over year in the four weeks to October 30, the weakest October pending data in five years. Q4 revenue guidance of $3.15-3.35 billion sits below estimates. Q4 adjusted EBITDA guidance of $100-130 million implies a full-year total of $830-860 million, at or slightly below the roughly $850 million consensus referenced last quarter. Looking to 2027, management flagged two pressures. Synergy actions will slow to about $70 million, back-end weighted, as the work shifts to systems integration. There is also a roughly $120 million operating-expense wraparound headwind.
The offsets are real but mostly self-help:
- Actioned net cost synergies rose to $360 million, above the $330 million target set in Q2, and full-year opex guidance was lowered to $2.71-2.73 billion.
- The two Guaranteed Rate mortgage joint ventures are merging under OriginPoint, which management expects to become a top-10 retail lender.
- The Home platform had 33,950 agents onboarded by October, with about 85,000 expected by year end and a franchise rollout starting in early 2027.
- Recruiting pipeline additions are up 39%.
- The company plans to redeem its $500 million of 9.75% notes when they become callable in Q2 2027, which would cut interest costs meaningfully.
The market setup was already cautious heading into the print. Shares closed at $10.04 the day before the report, down 21.3% from the $12.75 open after the August release. They had peaked at $13.60 in mid-August and bottomed at $8.42 on October 14. That left the stock 26% below its quarter high, 19% above its low, and only 1.8% above its 200-day moving average of $9.86. Investor sentiment slid from 0.16 to essentially neutral at 0.005, so the earlier optimism had largely drained away before the report. The Earnings Whispers trend signals were mostly negative, with sequential growth and price trends deteriorating, though momentum was positive.
The bottom line is that Compass proved it can turn the Anywhere merger into real earnings and cash, and the balance sheet is repairing faster than expected. But the quarter's growth engine stalled, and Q4 guidance points to an organic revenue decline as rates climb. With synergy gains slowing next year, the bull case increasingly depends on demand, which management cannot control. A stock sitting just above its 200-day average with neutral sentiment shows investors are unwilling to pay ahead for that recovery.
Read our earnings preview for Compass, Inc.: https://www.earningswhispers.com/article/COMP/22264
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| 7 hours | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-26 | |
| Oct-23 |
