Cable One Misses Badly As Subscriber Inflection Is Overshadowed By Shrinking Cash Flow, MBI Uncertainty And Explicit Chapter 11 Language
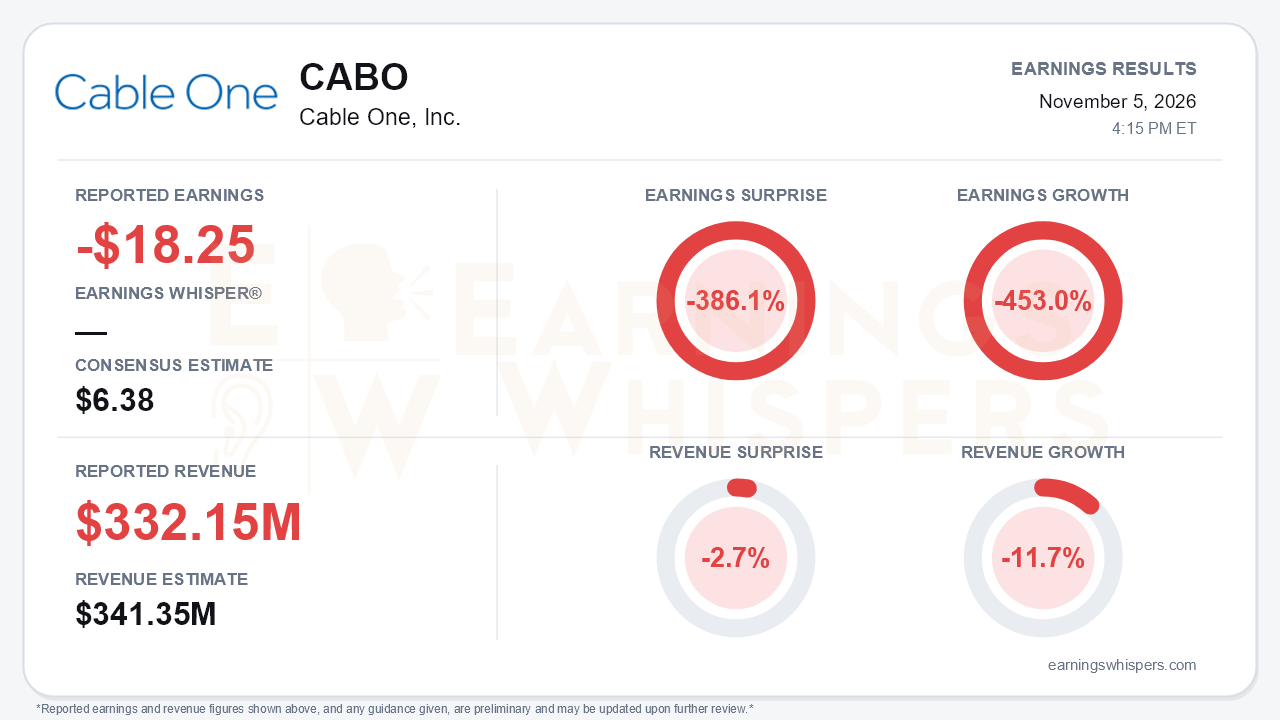
Cable One delivered the best customer-trend quarter it has posted in nearly two years, and it may not matter. The broadband operator reported a loss of $18.25 per share for the third quarter, against a consensus estimate of $6.38 in earnings. That is a 386.1% miss and a 453.0% year-over-year decline in earnings. Revenue of $332.15 million fell 11.7% and missed the $341.35 million consensus by 2.7%. On a GAAP basis the damage was far larger: a net loss of $431.8 million, or $75.66 per diluted share, compared with net income of $86.5 million a year earlier. The central tension is that operating volumes are finally improving just as the balance sheet has become the dominant story, and the company itself now says Chapter 11 is a possible outcome if refinancing fails.
Much of the GAAP loss is non-cash, but the charges themselves are a warning. A third-quarter stock-price collapse triggered $412.1 million of franchise and goodwill impairments. The quarter also carried a $39.7 million after-tax fair-value loss on the put option to acquire the rest of MBI and a $20.0 million after-tax impairment of the MBI equity stake. Stockholders' equity swung to a deficit of $86.3 million from $1.43 billion at year-end. Stripping out those items does not rescue the quarter:
- Adjusted EBITDA fell 20.8% to $159.8 million.
- Adjusted EBITDA margin compressed to 48.1% from 53.7%.
- Operating cash flow dropped 40.8%.
- Adjusted EBITDA less capex fell 37.1% to $81.9 million as capex rose to $77.9 million.
The sequential trend is the real problem. Revenue has slid from $363.7 million in the fourth quarter of 2025 to $353.0 million, $348.9 million and now $332.2 million. EBITDA margin has stepped down each quarter from 53.3%. Cash generation has fallen from $119.9 million to $81.9 million over the same span.
The call preserved a credible operating story, though it is a volume story bought with price.
- **Subscribers:** Broadband net losses narrowed to roughly 7,500 from about 17,100 in the second quarter, the best result in seven quarters. Connects were the strongest in 12 quarters.
- **Sales channels:** Door-to-door and digital channels accounted for about 44% of connects, up from 38% in the second quarter and 27% a year ago.
- **Business services:** Sold revenue rose 17% sequentially, with enterprise up 26% and carrier up 21%, the best since 2023.
- **Pricing:** Residential data ARPU fell about $2 sequentially to $78.48, down 4.5% year over year. That reversed the second quarter's gain and undercut the first-quarter expectation that ARPU would be broadly stable for the year.
- **Revenue decline:** Residential data revenue fell 10.3%, an acceleration from declines of 7.3% in the second quarter and 5.1% in the first.
Management's tone was more encouraged than the 'not yet showing up in results' framing of earlier in the year. Still, the numbers show that gross-add momentum is coming at the expense of revenue per customer, against elevated promotions from AT&T and Starlink.
Cost actions offer some offset. SG&A fell 18.4%, advertising sales were outsourced as of July 1, and management launched an early-retirement program and an AI-driven productivity push alongside a new COO and operations bench. Operating expense still rose 2.8% on software and contract labor.
The forward risks are concentrated in the capital structure, and bears have legitimate ammunition. Cable One drew a net $500 million on its revolver, lifting gross debt to $3.55 billion and leaving just $200 million undrawn. That draw is the main source of the $674.8 million cash balance. The release states plainly that existing liquidity will be insufficient to meet the debt coming due:
- MBI's $916.2 million of term loans maturing in November 2027, if that deal closes
- The $1.25 billion revolver in February 2028
- $345 million of convertible notes in March 2028
- A $694.3 million term loan in May 2028
The MBI acquisition, framed earlier as closing in early fourth quarter, is now subject to a temporary restraining order tied to CoBank litigation, and management is 'evaluating next steps.' The company intends to tie any MBI payment to a financing that addresses its maturities and warns that failing to close could expose it to damages claims.
The market had already priced in severe distress before the print. Shares stood at $5.26 ahead of the report, down 86.9% from the $40.26 open after the August release and roughly 90% below the 200-day moving average of $55.53. The stock set a 52-week low of $4.36 on October 27 and has bounced about 21% from that level. It remains near the bottom of a range that peaked at $42.22 the day after the last report. Investor sentiment improved from -0.59 to -0.48, so expectations are less negative but still firmly pessimistic. The Earnings Whispers trend readings are predominantly negative, with sequential growth, momentum and AVWAP all deteriorating.
The bottom line is that Cable One's operating turnaround is real at the subscriber level but has not reached revenue, margins or cash flow, which all worsened sequentially again. With the stock already down nearly 90%, the investment question has shifted from broadband execution to whether management can refinance roughly $3 billion of 2027-2028 obligations, and resolve MBI, on terms that leave meaningful value for equity holders.
Read our earnings preview for Cable One, Inc.: https://www.earningswhispers.com/article/CABO/22438
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 5 hours | |
| 6 hours | |
| Nov-03 | |
| Oct-28 | |
| Oct-28 | |
| Oct-12 | |
| Oct-02 | |
| Sep-25 | |
| Sep-24 | |
| Sep-11 | |
| Sep-02 | |
| Aug-19 | |
| Aug-14 | |
| Aug-07 |
