Array Technologies Misses As Margins Crack And Guidance Falls, Yet Record Backlog And Shoals Merger Reshape The Story
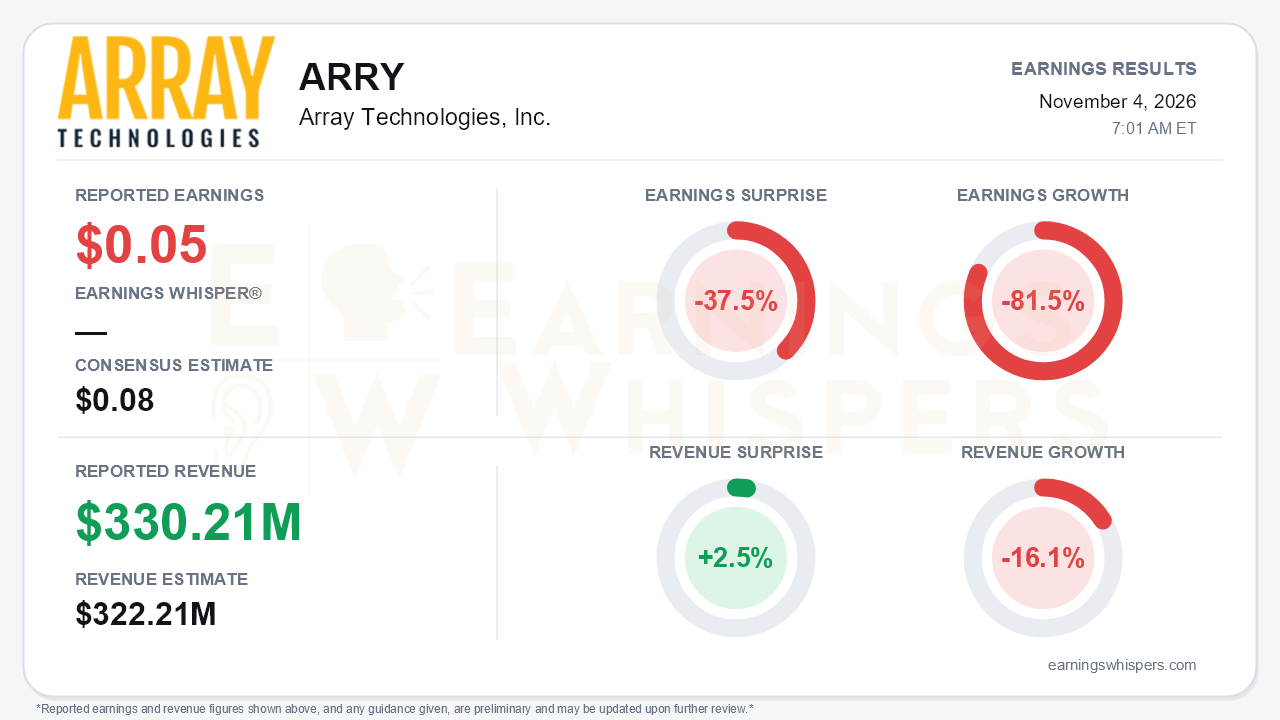
Array Technologies delivered a quarter in which the standalone results matter less than the deal announced alongside them. On an Earnings Whispers-normalized basis, the company earned $0.05 per share, missing the $0.08 consensus by 37.5%. Earnings fell 81.5% from a year ago. Revenue of $330.21 million beat expectations by 2.5% but fell 16.1% year over year. The company's own adjusted figure was $0.06, and on a GAAP basis Array posted a net loss to common stockholders of $0.05 per share, compared with a $0.12 profit a year earlier. That is the central tension. Bookings hit a fourth straight record even as margins, EBITDA, cash flow and full-year guidance all moved the wrong way. Management then answered with a stock-for-stock merger with Shoals Technologies that leaves Array holders with roughly 35% of the combined company.
The quality of the miss deserves scrutiny. Adjusted gross margin collapsed to 22.8%, down from 30.8% in Q2, 30.7% in Q1 and 28.1% a year ago. About 330 basis points of that decline came from a reserve against a long-dated 45X rebate owed by a supplier, shown as a $10.9 million provision on certain non-trade receivables. Even adding that back leaves margin well below first-half levels. Adjusted EBITDA fell to $32.1 million at a 10% margin, versus $63 million in Q2 and $72.2 million a year earlier. Free cash flow turned slightly negative at -$1.1 million. Cash dropped to $143 million from $244 million at year-end, largely because of the $161 million AWM acquisition. GAAP operating income also got help from a $10.3 million favorable change in contingent consideration, which flattered the bottom line rather than reflecting operations.
The demand picture tells a different story. The orderbook reached $2.6 billion, up 42% year over year and up from $2.5 billion in Q2 and $2.2 billion at the end of 2025. Array has booked more than $400 million of new orders for five consecutive quarters. That lifted trailing twelve-month orders above $1.8 billion and book-to-bill to 1.6x. New products now make up about 60% of the backlog, up from roughly 50% earlier in the year, which suggests the Atlas foundation-to-tracker push and the new 60-degree tracker are gaining traction. AWM, closed August 31, added about $9 million in its first month. Management said it was accretive and opens a path into battery storage and data center markets.
The problem is converting that demand into revenue. The press release cut full-year 2026 guidance across the board:
- Revenue: $1.34 billion to $1.40 billion, down from $1.4 billion to $1.5 billion.
- Adjusted EBITDA: $190 million to $210 million, down from $210 million to $230 million.
- Adjusted EPS: $0.57 to $0.69, down from $0.68 to $0.75.
Adjusted gross margin guidance now sits at roughly 27%, the bottom of the 27-28% range set in Q2. Management blamed delivery timing rather than weaker demand. Even so, the fourth-quarter revenue outlook of $445 million to $505 million requires a steep step-up from $330 million. Notably, the standalone guide was not addressed on the joint call, so investors are left to underwrite a back-end-loaded year with little discussion.
The Shoals merger is now the dominant catalyst, and it cuts both ways. Under the deal terms, each SHLS share converts into 1.6931 ARRY shares, with closing expected in Q1 2027. Management offered a preliminary combined 2027 outlook of $2.2 billion to $2.4 billion in revenue and $410 million to $480 million in adjusted EBITDA, including synergies. Other selling points include:
- Synergies of $35 million in year one, rising to more than $100 million by year three.
- A plan to cut the costly Series A preferred by more than 60%, saving roughly $100 million in distributions over five years.
- Access to Shoals' tax assets to lower cash taxes.
- A cross-sell opportunity sized at $2.5 billion, since only about 20% of projects use both companies' products.
Bears have legitimate ammunition, however. Kevin Hostetler moves to an advisory role while Shoals CEO Brandon Moss takes over. Pro forma leverage of 2.6x net debt to EBITDA is higher than Array's standalone 2.1x, and an analyst flagged pro forma cash of about $30 million as thin. Two-thirds of the synergy target depends on commercial cross-selling rather than cost cuts.
Investors were already leaning skeptical. Earnings Whispers sentiment weakened from -0.19 to -0.34, a meaningful deterioration within negative territory. Shares at $5.33 are down 14.9% from the $6.26 open after the August report and sit 21.8% below the 200-day moving average of $6.82. The trend readings are mixed, with price and AVWAP negative while momentum is positive.
The bottom line is that Array's standalone quarter was weak: an earnings miss, a margin break, negative free cash flow and lowered guidance. The record $2.6 billion backlog keeps the demand case intact, but the investment question has changed. Array holders are no longer simply betting on a tracker recovery. They are betting on a Shoals-led integration, synergy delivery and balance-sheet repair, with only about a 35% share of the result.
Read our earnings preview for Array Technologies, Inc.: https://www.earningswhispers.com/article/ARRY/22239
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-04 |
Array Technologies to merge with Shoals in $1 billion deal, combining solar suppliers
ARRY +14.87%
Albuquerque Journal, N.M.
|
| Nov-04 | |
| Oct-28 | |
| Oct-14 | |
| Sep-29 | |
| Sep-18 | |
| Sep-18 | |
| Sep-09 |
Array Technologies opens new Albuquerque plant amid volatile solar market
ARRY
Albuquerque Journal, N.M.
|
| Sep-09 | |
| Aug-31 | |
| Aug-27 | |
| Aug-26 | |
| Aug-24 | |
| Aug-21 |
