Amphastar Beats Handily On BAQSIMI Repair, But Margin Erosion And IMS Drag Temper The Record Quarter
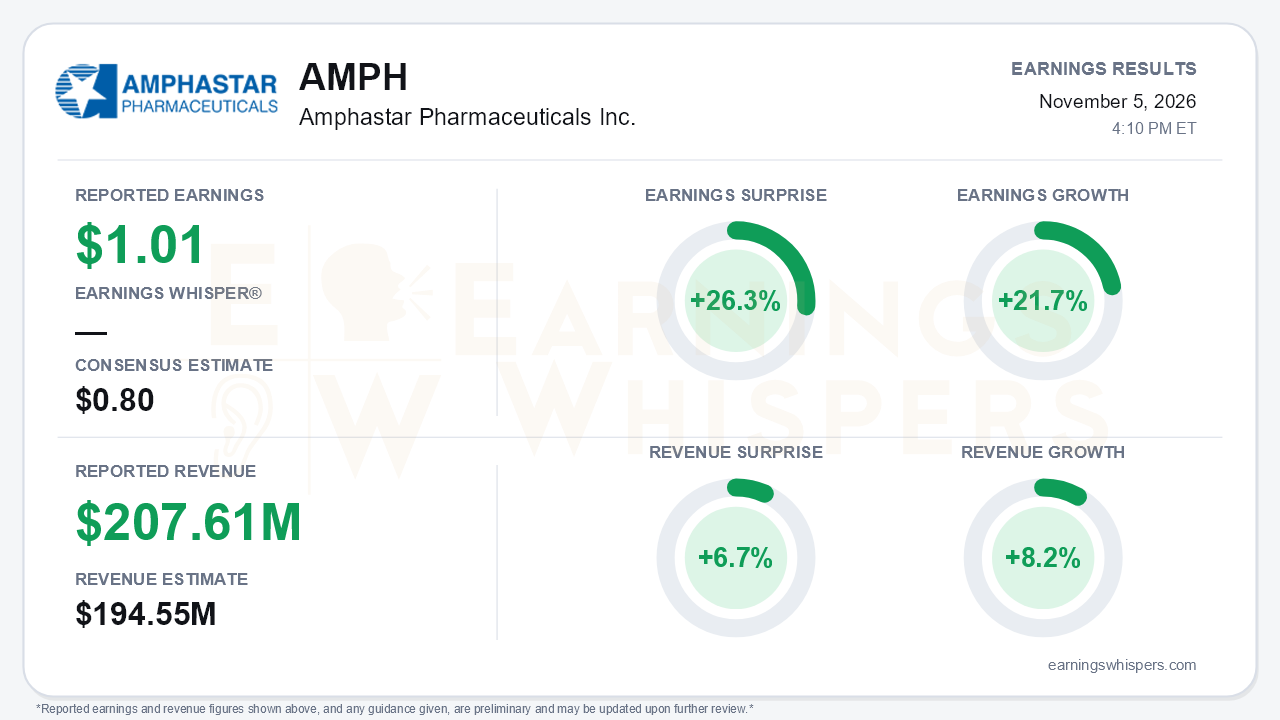
Amphastar Pharmaceuticals delivered a clean beat on both lines in the third quarter. Earnings Whispers-normalized EPS was $1.01, ahead of the $0.80 consensus by 26.3% and up 21.7% year over year. Revenue was a record $207.61 million, 6.7% above the $194.55 million estimate and up 8.2%. The company's own figures were $0.87 in GAAP EPS, up from $0.37, and $1.14 in adjusted EPS, up from $0.93. Either way, the quarter marked a sharp sequential acceleration: revenue rose from $171.2 million in Q1 to $183.9 million in Q2 and then jumped 13% sequentially. The central story is that BAQSIMI's pricing problem is largely fixed. The central tension is that gross margin is moving the wrong way just as the top line recovers.
The quality of the beat deserves scrutiny. Revenue grew 8%, but gross profit rose only 1%, to $99.6 million, and gross margin fell to 48.0% from 51.4% a year ago and 51% in Q2. The GAAP earnings jump owes a great deal to easy comparisons. Last year's quarter absorbed a $23.1 million litigation provision and a $5.3 million licensing payment, so G&A fell 57% this year. A roughly 9% decline in diluted share count, to 43.4 million, also flattered per-share results. Year to date, adjusted EPS of $2.45 still trails the $2.52 earned in the first nine months of 2025. Operating cash flow slipped to $43.3 million from $51.3 million in Q2, even as receivables climbed. This was a strong quarter, but not an unambiguous inflection in profitability.
The operating improvement beneath the headline is real, and it is concentrated in the branded franchises. BAQSIMI hit a record $58.8 million, up 10%. That compares with declines of 3% in Q2 and 15% in Q1. The 340B duplicate-discount headwind shrank to $2.2 million from $8.1 million in Q2, and management said the fix is approaching its roughly 80% resolution target. Primatene MIST also set a record at $31.5 million, up 9%, helped by a second-quarter price increase and growing in-store units. Lidocaine rose 29% on a competitor shortage that management expects to persist into 2027. New launches are holding:
- teriparatide contributed $6.4 million;
- API sales contributed $6.2 million;
- ipratropium added $6.6 million, though that was down from $8.4 million in Q2 after second-quarter channel loading.
The weaker side is just as identifiable. Remediation at the IMS facility, which is operating under an FDA warning letter, cut epinephrine sales 19% to $15.3 million and lowered output of other IMS products. Remediation costs were about $3 million in the quarter, and management now expects them to run somewhat above the previously cited $2-3 million per quarter for another two to three quarters. The fourth-quarter outlook includes a modest IMS sales slowdown, although a $12.5 million backorder offers some recovery potential if releases improve. Glucagon fell 37% on competition. Management also conceded that BAQSIMI net pricing will not return to historical levels. It said gross margin recovery depends on new volume such as insulin aspart, which still has no firm 2027 launch date and faces three to four entrenched competitors. Filings for AMP005 and AMP017 slipped to the second half of 2027, and the GLP-1 program was framed as a limited opportunity. Guidance was essentially reaffirmed rather than raised. On the positive side, the board added $50 million to the buyback, and AMP104, a next-generation low-GWP Primatene formulation, joined the proprietary pipeline.
The market had already moved ahead of much of this. Shares rose 24.6% from the $22.48 open after the August report to $28.02. That left the stock about 25.7% above its 200-day moving average and within 2% of its inter-earnings high of $28.57, set the day before the release. Shares had rallied more than 43% off the August low of $19.55. Investor sentiment remained negative but improved meaningfully, rising from -0.46 to -0.22. Earnings Whispers price and AVWAP trend readings are positive, while sequential-growth and momentum readings are neutral, a mix consistent with a rally that has outpaced fundamental confirmation.
The setup is therefore more complicated than the surprise implies. Turnaround skeptics were not positioned for BAQSIMI's rebound, and the improving sentiment reflects that. Bears still have legitimate ammunition, however: margin compression, a remediation bill that is growing rather than shrinking, delayed pipeline filings, and a growth outlook that management held rather than lifted.
The bottom line is that Amphastar resolved its most visible problem, BAQSIMI pricing, and paired it with record revenue and a sizable beat. The quarter also exposed a margin structure under pressure from pricing erosion and IMS costs that will not clear quickly. With the stock entering the report near its quarterly high, the next leg likely depends less on the top line than on evidence that gross margin can stabilize and IMS output can recover.
Read our earnings preview for Amphastar Pharmaceuticals Inc.: https://www.earningswhispers.com/article/AMPH/22456
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-29 | |
| Sep-01 | |
| Aug-06 | |
| Aug-06 | |
| Jul-29 | |
| Jun-29 | |
| May-27 | |
| May-07 | |
| May-07 | |
| May-06 | |
| Apr-30 |
