Allogene Misses On A Wider Loss As ALPHA3 Enrollment Accelerates But Interim-Data Expectations Cool
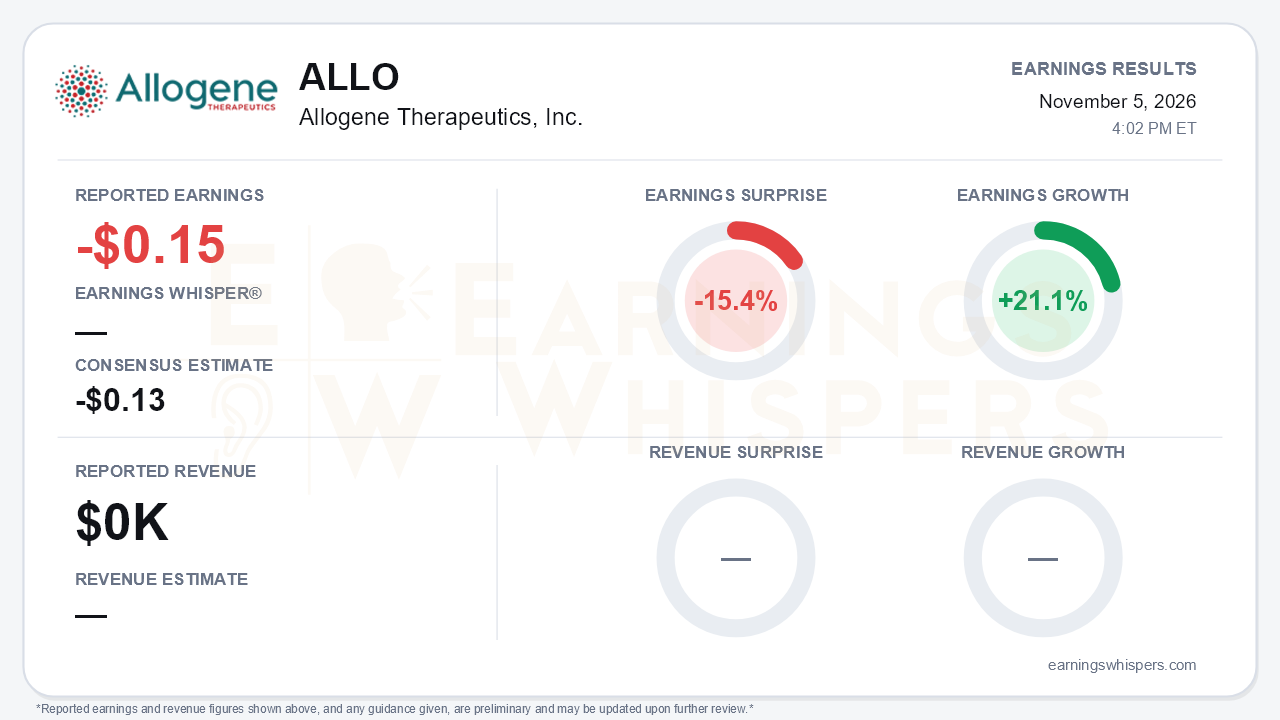
Allogene Therapeutics reported a third-quarter loss of $0.15 per share, missing the consensus estimate of a $0.13 loss by 15.4%. There was no revenue. On a per-share basis, earnings improved 21.1% from a year ago, when the company lost $0.19 per share. That apparent improvement is mostly a share-count story. The central tension of the quarter is that ALPHA3 is executing better operationally, while management has become more cautious about the mid-2027 readout that investors are counting on. The stock has already been punished heavily.
The quality of the year-over-year improvement deserves scrutiny. Net loss actually widened to $50.4 million from $41.4 million. Total operating expenses rose to $54.8 million from $44.9 million, driven by research and development spending that climbed to $41.9 million from $31.2 million. General and administrative expense edged down to $12.9 million. The narrower per-share loss reflects a weighted-average share count that rose to roughly 346 million from 222 million, largely a consequence of the roughly $200 million raise completed in April. That financing left the company with $388.9 million in cash and investments, up from $258.3 million at year-end. The release reaffirmed a runway into 2029 and unchanged 2026 guidance of roughly $165 million in cash operating expenses and $225 million in GAAP operating expenses. Notably, none of those figures were discussed on the conference call itself. Investors got the reaffirmation in writing but no fresh financial color from management, on a call where the CFO was departing.
Operationally, the call delivered genuine progress on cema-cel's pivotal ALPHA3 trial, which management described as "in a great place."
- **Productivity:** Per-site productivity improved.
- **Asia-Pacific:** Sites in Korea and Australia have been screening and enrolling briskly since mid-summer.
- **Screening and sites:** MRD screening is increasing, and more community practices are coming online in the coming weeks.
- **Site build-out:** The network grew from more than 60 sites at the end of 2025 to 80 in July, with about 100 targeted by year-end.
- **Timelines:** The interim event-free survival update remains slated for mid-2027 and enrollment completion for year-end 2027, consistent across four consecutive calls. Management said it does not expect to adjust that timeline.
The hiring of Kite veteran Rocio Manghani to lead market access signals early commercial groundwork. So does the planned ASH physician survey and investor event focused on community-based CAR T adoption.
The tone around the interim readout shifted, however, and bears have legitimate ammunition. Management stressed that only a small amount of statistical alpha is allocated to the interim look. It also noted that the data monitoring committee could recommend continuing blinded to protect the trial's registrational integrity. That is a meaningfully more guarded posture than in the first quarter, when then-CEO Chang said the probability of interim success had "gone up quite a bit."
The competitive picture has also tightened. Management acknowledged that epcoritamab plus R-CHOP produced a better-than-expected frontline hazard ratio below roughly 0.5, a development that could shrink the MRD-positive pool. Management still argues the impact on its addressable market is limited.
Leadership turnover is another concern. A CEO transition earlier this year has now been followed by CFO Geoff Parker's retirement on November 6, with no permanent successor named.
The nearest catalyst is ALLO-329. An expanded RESOLUTION dataset will be presented at ACR on November 9, covering three dose levels and three conditioning approaches, including no lymphodepletion. Management reports no high-grade toxicities or IEC-HS to date, and scleroderma is emerging as the lead enrolling indication. Analysts, however, have flagged two serious adverse events at dose level 2. Lupus and myositis enrollment trails scleroderma, in an autoimmune CAR T field that is increasingly crowded. A strong showing on lymphodepletion-free activity would be a differentiator. A messy safety read would compound the stock's problems.
The market setup is harsher than the fundamentals alone suggest. In the pre-report snapshot, shares stood at $1.19, down 44.1% from the $2.13 opening after the August report. The stock was about 39.5% below its 200-day moving average of $1.97 and sat just 11.2% above the inter-earnings low of $1.07 set on November 2, after peaking at $2.23 in mid-August. Investor sentiment nonetheless remained positive and modestly strengthened, rising from 0.66 to 0.73. That suggests the investor base still leans constructive despite the price collapse. Most Earnings Whispers trend readings remain negative, with price, sequential growth and AVWAP trends all weak, though momentum is a positive outlier.
The bottom line is that Allogene delivered a reaffirmation quarter with a wider dollar loss behind a dilution-flattered per-share improvement. ALPHA3 enrollment is clearly gaining traction, and the balance sheet provides runway into 2029. But management's softer framing of the 2027 interim analysis, stronger frontline competition and back-to-back executive departures give skeptics reasons to stay cautious. For a stock trading near its lows despite positive sentiment, the ACR data on November 9 is the next real test of whether the platform story can regain credibility.
Read our earnings preview for Allogene Therapeutics, Inc.: https://www.earningswhispers.com/article/ALLO/22455
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-29 | |
| Oct-29 | |
| Oct-26 | |
| Sep-15 | |
| Sep-02 | |
| Sep-02 | |
| Aug-31 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 |
