Doximity Beats Its Own Guide And Raises Again, But Eroding Retention Metrics Put The AI Reacceleration Story On Trial
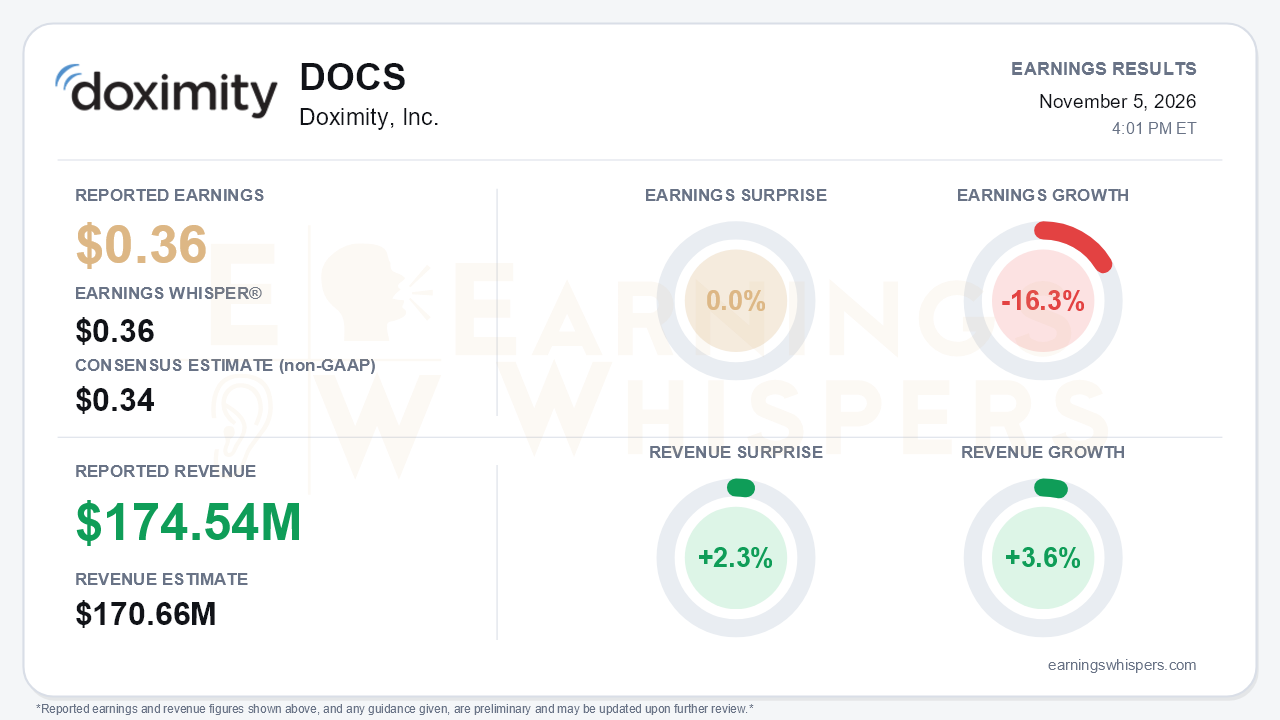
Doximity (NYSE: DOCS) delivered a second straight beat-and-raise, but the quarter is better read as a bet on what comes next than a clean win on what just happened. Non-GAAP EPS of $0.36 matched the Earnings Whisper number and topped the $0.34 consensus. Revenue of $174.54 million beat the $170.66 million consensus by 2.3%. The weaker part is growth. Earnings fell 16.3% year over year. Revenue grew just 3.6%, a clear deceleration from roughly 7% in the prior quarter, which management attributed to a tough comparison. Doximity raised its fiscal 2027 revenue outlook again, and that is the reason the report reads better than the growth rates.
The quality of the quarter deserves scrutiny because Doximity is visibly trading margin for an AI buildout. Adjusted EBITDA of $88.9 million cleared the company's own $80.5 million to $81.5 million guide. Even so, EBITDA fell 12% year over year, and the margin compressed to 51% from 60%.
On a GAAP basis the damage was steeper:
- Net income nearly halved to $34.7 million from $62.1 million.
- Diluted EPS dropped to $0.18 from $0.31.
- The causes were cost of revenue rising more than 50%, stock-based compensation climbing to $40.6 million from $29.5 million, and a sharply higher tax provision.
- Non-GAAP gross margin slid to 87.8% from 91.9% a year ago as AI compute scaled.
- Aggressive buybacks, including $54 million this quarter, cut the diluted share count to 187.8 million from 200.7 million and cushioned the per-share decline.
Cash generation held up well. Free cash flow of $91.3 million was essentially flat year over year and rebounded from about $40 million in the first quarter.
The call preserved a credible growth story, and the evidence is mostly about leading indicators:
- **AI Search:** moved from a handful of deals two quarters ago to eight-figure bookings, with 16 of the top 20 pharma companies signed and three more in contracting.
- **Workflow adoption:** active prescriber growth accelerated to 34% from just above 30% last quarter.
- **Health systems:** systems buying the AI suite rose to 190 from 165 in Q1 and 140 two quarters ago.
- **Unit economics:** cost of revenue grew at less than half the rate of prompt volume, versus roughly one-to-one in Q1. That suggests the gross-margin hit may be moderating.
- **Pharma demand:** management described the environment as "more stable," an improvement from "tight" last quarter and "soft" before that.
- **Outlook:** management guided third- and fourth-quarter growth to about 6%, framing that as the beginnings of reacceleration.
Bears have legitimate ammunition, however. Net revenue retention fell to 103% from 107% in Q1, 109% the quarter before, and 112% before that. Top-20 customer retention slid to 106% from 112%. Customers generating more than $500,000 in trailing revenue declined to 124 from 127. Management hinted it may retire these retention and customer-count metrics. Skeptics will reasonably read that as moving the goalposts just as the numbers trough.
The AI Search revenue ramp is also explicitly gradual through calendar 2027. It is gated by months-long medical-legal review cycles, and management acknowledged limited fourth-quarter visibility until pharma upfronts close.
The guidance is supportive but not unambiguous:
- **Revenue:** fiscal-year guidance rose to $678 million to $683 million, from $671 million to $681 million last quarter and $664 million to $676 million at the start of the year.
- **Fiscal-year EBITDA:** the range narrowed to $317 million to $325 million. That is up slightly at the midpoint versus last quarter but still below the original $323 million to $335 million outlook.
- **Third quarter:** revenue guidance of $195 million to $196 million and EBITDA of $102.5 million to $103.5 million imply a roughly 53% margin.
Upcoming catalysts include auction-based AI Search purchasing set to pilot around the turn of the calendar year, third-party API access to the clinical intelligence layer, the UpToDate content partnership, and the DoseCheck launch.
Investor expectations shifted meaningfully into the report. Earnings Whispers sentiment swung from -0.20 after the prior quarter to +0.28, a substantial move from mildly negative to moderately positive. The stock's path has been volatile. Shares opened at $38.87 after the August report and touched $40.00 that day, then collapsed to $23.95 by August 17. They have since recovered nearly 45% off that low to $34.67, still 10.8% below the post-report open and about 13% under the quarter's high. At the same time, the stock sits 36% above its 200-day moving average, and the Earnings Whispers trend signals for price, momentum, and sequential growth are mostly positive. That means DOCS entered this report having already priced in a good deal of renewed optimism. The bar is therefore higher than an in-line EPS print alone implies.
The bottom line is that Doximity's near-term financials are weak: decelerating growth, sharply lower GAAP profit, compressing gross margins, and retention metrics still falling. Yet raised guidance, improving AI unit economics, and fast-growing AI Search bookings give management a plausible reacceleration narrative for the second half. Sentiment has already pivoted toward that narrative. The next test is whether projected 6% growth materializes and whether retention stabilizes, rather than simply disappearing from the scorecard.
Read our earnings preview for Doximity, Inc.: https://www.earningswhispers.com/article/DOCS/22275
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours | |
| 21 hours | |
| Oct-29 | |
| Oct-28 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-13 | |
| Oct-05 |
