Dropbox Beats On Buyback-Driven EPS And Raises Again, But A Flat 2027 Revenue Preview Leaves The AI Pivot Carrying The Story
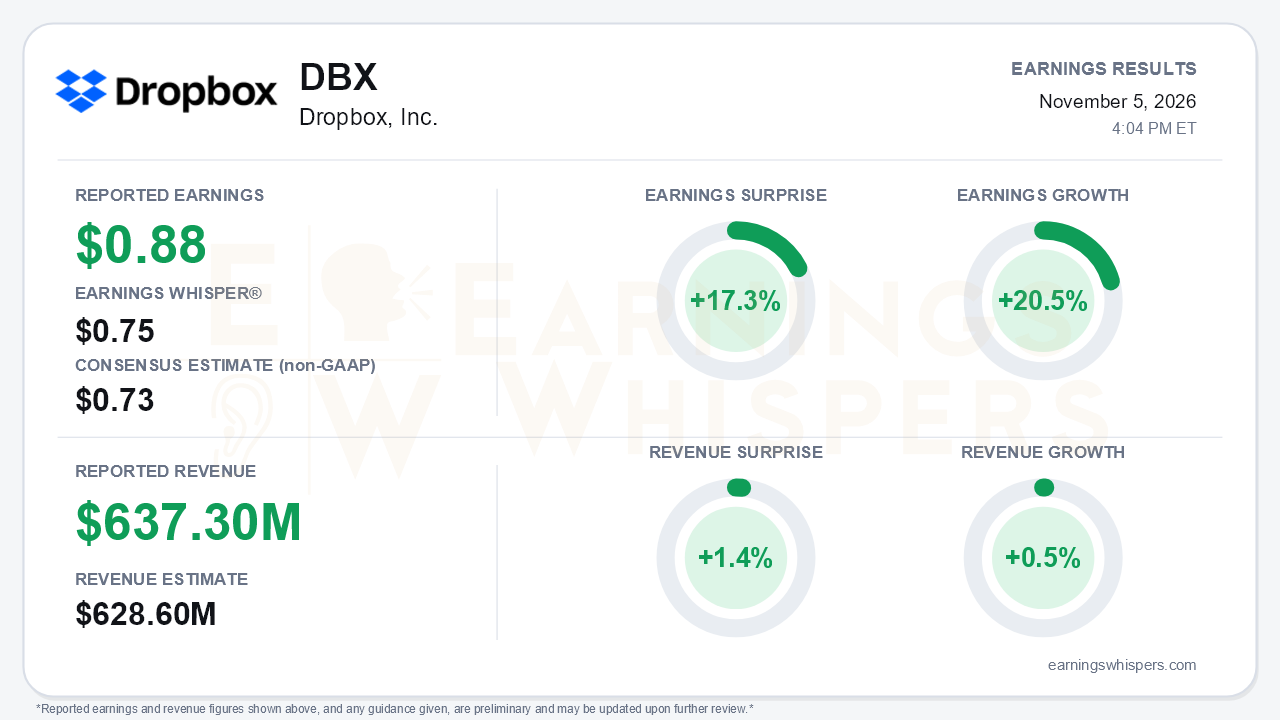
Dropbox delivered another clean beat and raise in the third quarter. Non-GAAP earnings of $0.88 per share topped the $0.73 consensus by 17.3% and cleared the $0.75 Earnings Whisper number. Earnings grew 20.5% year over year. Revenue of $637.3 million beat the $628.6 million consensus by 1.4%, yet grew just 0.5%. That gap is the central tension. Per-share earnings are rising at a healthy clip, while the underlying business is barely growing. Management's preliminary 2027 view implies roughly flat revenue excluding Tigris, so the company is now asking investors to underwrite a new AI infrastructure strategy to restart the top line.
The quality of the EPS beat deserves scrutiny. Non-GAAP net income was essentially unchanged at $197.8 million versus $196.7 million a year ago. Nearly all of the per-share growth came from a 40 million drop in the diluted share count, to 225.1 million from 265.1 million, after heavy repurchases. Those buybacks were partly debt-funded:
- Term loans now total roughly $2.6 billion.
- Net interest expense jumped to $51.2 million from $20.3 million.
- GAAP net income fell to $116.1 million from $123.8 million.
- Operating cash flow dropped to $259.2 million from $302.1 million.
Operating performance itself was genuinely solid. Non-GAAP operating margin reached 42.2%, against a 38.5% guide and 41.1% a year ago. Non-GAAP gross margin of 81.8% turned positive year over year, up about 40 basis points, after declines in the first two quarters as infrastructure efficiencies offset AI compute costs.
The call showed incremental demand improvement inside a stagnant total:
- Revenue excluding the now fully wound-down FormSwift grew 1.0%, but only 0.2% in constant currency.
- Teams self-serve drove the beat, and North America managed sales had its strongest quarter in two years.
- Net paying-user additions slowed to about 20,000 (roughly 60,000 excluding FormSwift) from 96,000 in Q2.
- Average revenue per paying user slipped to $138.76 from $139.07 on Simple plan mix.
- Total ARR fell about $10 million sequentially to $2.555 billion, although ARR excluding FormSwift rose $4.7 million.
The guidance trajectory remains the strongest evidence of execution. Full-year revenue guidance has now risen on every call, to $2.528-$2.531 billion. The operating margin target moved up to about 40.5%, and unlevered free cash flow guidance rose to at least $1.075 billion.
The forward story changed materially. Dropbox launched DBX Agent Cloud, an S3-compatible object storage business aimed at AI developers. It also agreed to buy Tigris Data for about $350 million in cash, expected to close in the fourth quarter. Early AI engagement metrics are striking:
- AI integration connections reached 1.4 million, up from 150,000 at Q2.
- Weekly uploads from AI tools exceeded 2 million.
- The AI-powered Dropbox experience is reaching about 70,000 teams.
Monetization, however, remains gradual. Bears have legitimate ammunition:
- Tigris is unsized and carries a modest burn.
- The deal adds execution risk to a balance sheet already in a stockholders' deficit.
- Wider AI rollout could pressure gross margin.
- Q4 operating margin is guided to about 40%, below Q3, on deferred marketing.
A roughly 9% workforce reduction, with about $30 million in severance, underpins management's early call for about 150 basis points of operating margin expansion in 2027. But reinvestment in Tigris may absorb part of those savings.
Investors entered the print skeptical but less so than in August. Earnings Whispers sentiment improved from -0.36 to -0.27, still negative but trending better. The stock has been treated more kindly than sentiment suggests. At $36.10, shares were up 2.4% from the open after the prior report and about 24% above their 200-day moving average. They sat 5.5% below the 52-week high of $38.22 set on October 26, after rebounding 16% from a late-September low. Most Earnings Whispers trend readings are positive, with sequential growth neutral, which fits a stock rewarded for margins and capital return rather than growth.
The bottom line is that Dropbox keeps beating and raising by squeezing more profit and fewer shares out of a flat revenue base, and that playbook is nearing its limits as leverage rises and 2027 revenue looks flat. The Tigris deal and DBX Agent Cloud give the company a credible new growth narrative, but for now it is a narrative rather than revenue. The next several quarters need to show AI engagement converting into paying users and ARR.
Read our earnings preview for Dropbox, Inc.: https://www.earningswhispers.com/article/DBX/22272
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-28 | |
| Oct-15 | |
| Oct-06 | |
| Sep-29 | |
| Sep-29 | |
| Sep-29 | |
| Sep-24 | |
| Sep-24 |
