Innodata Beats Handily, But A Tax-Aided EPS Gain, Sharp Margin Reset And $12 Million Q4 Hole Complicate The Record Quarter
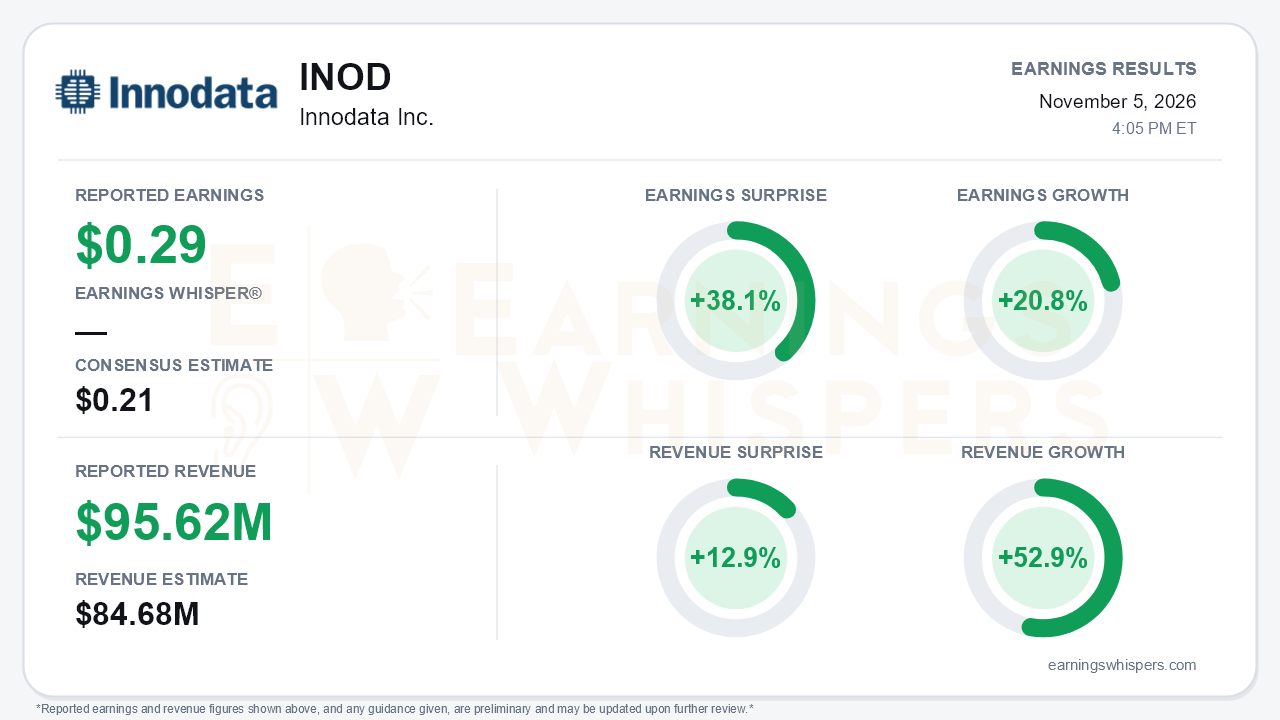
Innodata delivered a clear beat at the top and bottom lines, but this was not a clean quarter. Earnings of $0.29 per share topped the $0.21 consensus by 38.1% and grew 20.8% year over year. Revenue of $95.62 million beat the $84.68 million estimate by 12.9% and rose 52.9%. Management framed the beat more generously, saying EPS beat consensus by roughly 70% and revenue by about $12.3 million, or 15%, against a lower $83.3 million revenue estimate. That gap reflects different consensus baselines, but either way the company outran expectations. The central tension is that revenue momentum is broadening while profitability is moving the other way, and the earnings gain leans heavily on a tax line rather than operating leverage.
The quality of the beat deserves scrutiny. Pre-tax income actually fell to $10.0 million from $12.2 million a year ago. Net income rose to $10.3 million only because the company recorded a $340,000 tax benefit against a $3.8 million provision last year. GAAP gross margin slipped to 37% from 41%, and adjusted gross margin fell to 40% from 44%. Selling and administrative expense nearly doubled to $26.9 million, partly because stock-based compensation jumped to $6.8 million from $2.7 million. Adjusted EBITDA grew just 9% to $17.7 million, a sharp deceleration from the 92% growth posted in Q2.
Sequentially the reset is starker:
- Adjusted gross margin fell to 40% from 49% in Q2 and 47% in Q1.
- Adjusted EBITDA margin dropped to about 19% from 27.5%.
- EPS fell from $0.41.
- Revenue grew only 4% quarter over quarter.
Management characterized the 40% gross margin as back at target, and signaled it will keep prioritizing lower-margin, capability-building programs. In other words, investors should not assume Q2's margin profile was the new baseline.
The call did preserve a credible growth story, and it was more diversified than before. New CEO Rahul Singhal, on his first call, sounded highly confident and laid out six growth drivers.
- **A new largest customer.** A big-tech customer that was under 5% of revenue a year ago became the largest in Q3. It signed a $29 million pre-training program in the quarter and roughly $18 million more in Q4.
- **Hyperscaler expansion.** A hyperscaler that generated about $3.1 million over the trailing twelve months is now forecast to exceed $20 million in 2027 after five program wins.
- **New customers.** Five new logos were added in Q3.
- **Physical AI.** The newly launched motion capture lab supports physical AI pilots, one of which management says could yield about $7 million in 2027 if successful.
- **Trust and safety.** Statements of work total roughly $6 million plus a $2.5 million verbal commitment.
- **Federal.** A verbal $5 million-per-year, five-year federal win is expected to sign by year-end.
The balance sheet supports the push. Cash net of customer prepayments rose to $153.7 million from $134.4 million at Q2, with no debt.
The risk side is concrete, though. The historically largest customer ended a program in mid-October, opening a roughly $12 million Q4 revenue hole. Management expects new programs to replace it in Q1 but would not confirm the timing. That gap explains why full-year guidance moved only from 40%+ to 42%+ growth, a modest raise that reads as broadly in line rather than a major upside revision. Concentration also persists, now split between two customers of comparable scale rather than one. Several of the most exciting drivers remain verbal wins, pilots or forecasts rather than booked revenue.
The market had already turned decisively skeptical heading into the print. Shares opened at $67.88 after the August report and spiked to an inter-earnings high of $79.44 the next day. They then fell to $43.30 as of the pre-report snapshot, down 36.2% and 45.5% below that high. The stock sits just 6% above its November 2 low of $40.86 and roughly 29% below its 200-day moving average. Investor sentiment moved from roughly neutral at -0.06 to a clearly negative -0.44. Expectations had reset materially lower, which sets a lower bar but also signals deep doubts about margin durability and customer volatility. Earnings Whispers trend readings are split: sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that Innodata proved its demand engine is broadening, beat expectations comfortably and nudged guidance higher. However, the headline EPS gain was flattered by taxes, margins have reset sharply and a $12 million Q4 air gap leaves near-term growth dependent on unconfirmed replacement programs. Bulls have a richer pipeline and a diversified customer base to point to. Bears have legitimate ammunition in decelerating EBITDA growth, and the stock's steep slide and souring sentiment show which concern the market has been weighting.
Read our earnings preview for Innodata Inc.: https://www.earningswhispers.com/article/INOD/22312
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-15 | |
| Sep-30 | |
| Sep-22 | |
| Sep-15 | |
| Sep-04 | |
| Sep-01 | |
| Aug-07 | |
| Aug-06 | |
| Aug-04 | |
| Jul-15 |
