Inogen's Reset Quarter: U.S. Growth Returns, But An International Reversal And Lower Guidance Hit A Stock Priced For Better News
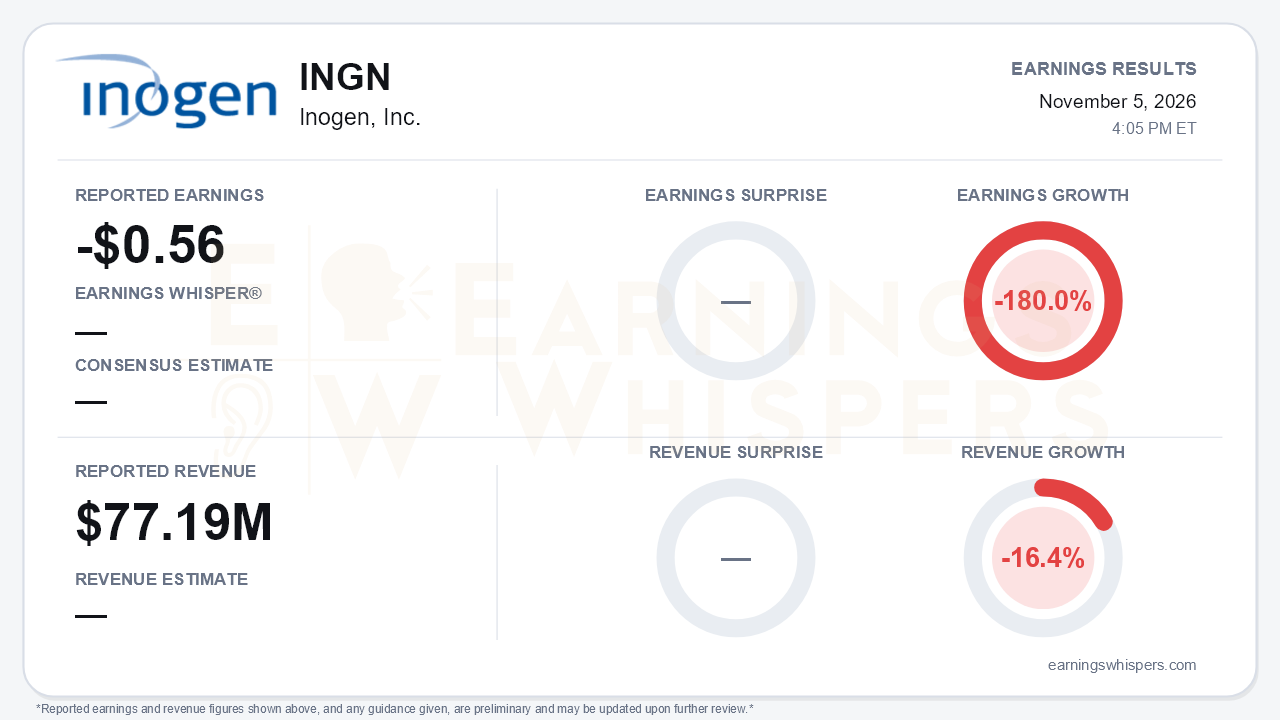
Inogen's third quarter was a reset, not a recovery. The company reported a GAAP loss of $0.56 per share from continuing operations on revenue of $77.19 million. No consensus estimate or Earnings Whisper was available, so there is no surprise to measure. By Earnings Whispers' measures, earnings fell 180.0% year over year and revenue fell 16.4%.
That revenue decline needs context. The company now reports the divested U.S. oxygen rental business as discontinued operations and has recast prior periods. On that like-for-like basis, the release shows revenue down 2.4%, or 3.2% in constant currency. The larger supplied decline reflects the comparison to the prior-year base before the rental business was stripped out. Either way, the top line shrank, and the outlook was cut. Earnings Whispers characterizes the guidance as below estimates.
The quality of the loss deserves scrutiny in both directions:
- **Non-cash charge:** Most of the GAAP damage came from a $10.6 million goodwill impairment, worth $0.40 per share. It was triggered by Inogen's market capitalization falling below book equity.
- **Adjusted results still weakened:** Stripping out the impairment, amortization, stock compensation, restructuring costs and proxy-defense expenses leaves an adjusted loss of $0.02 per share, against adjusted earnings of $0.04 a year ago.
- **Margin compression:** Adjusted gross margin slipped to 44.2% from 45.6% in the second quarter and 45.9% a year earlier. Lower-margin mix as international sales fell more than offset ongoing manufacturing cost gains.
- **Cash burn:** Operating cash flow swung to roughly negative $4.5 million from positive $2.9 million in the prior quarter, driven by a working-capital build. Receivables have risen sharply since year-end. Cash ended at $97.7 million, still with no debt.
The central tension is a geographic split. U.S. sales grew 3.8% to $42.2 million, the first year-over-year gain since the fourth quarter of 2024. That follows a 2% decline in the second quarter. New products Voxy and Aurora contributed about 250 basis points of growth, up from about 100 basis points, and management expects U.S. growth to accelerate in the fourth quarter.
International, however, unraveled. Sales fell 9% to $34.9 million after rising 15% in the prior quarter, ending a ten-quarter run of double-digit growth. Management cited European capital-spending and inventory softness and expects it to persist into the fourth quarter. Portable concentrator unit growth slowed accordingly, to about 6% from more than 12% in the second quarter and more than 20% at the end of 2025.
Guidance and disclosure both moved the wrong way. Full-year revenue guidance has now been cut repeatedly:
- $366-373 million at the start of the year;
- $355-361 million in the second quarter;
- $298-301 million from continuing operations now.
The fourth-quarter guide of $65-68 million sits below the roughly $68.6 million ex-rental base from a year ago. Management also dropped the adjusted EBITDA target of about $4 million, which it had raised just last quarter, in favor of an adjusted net loss of $7-8 million. That substitution reduces comparability with prior targets.
The tone of the call compounded the reset:
- New CEO Andy Reding, COO since July, replaced Kevin Smith and said results "are not where they need to be."
- The call included no live Q&A.
- The long-term framework of high-single-digit growth and a 10%-plus adjusted EBITDA margin was not reiterated.
The offsetting catalysts are mostly self-help and capital allocation:
- **Cost cuts:** A new $20 million annualized savings program targets $10 million by year-end. Combined with the rental exit, management targets more than $40 million in annualized operating-expense savings versus the prior run rate.
- **Divestiture proceeds:** The rental sale brings up to $24.8 million in cash, expected in the first half of 2027.
- **Buyback:** The authorization rose to $45 million. The company has repurchased 1.8 million shares for $11.2 million year to date.
- **Governance:** The board plans to propose declassification and elimination of supermajority votes in 2027. Read alongside the proxy-defense costs, this suggests responsiveness to shareholder pressure.
- **Expansion:** Management also flagged a push into Asia Pacific and Latin America.
The market setup is more complicated than the fundamentals alone imply. Investor sentiment rose sharply into the report, from 0.35 to 0.69. Shares had climbed 22.5% since the open after the August report, to $7.22. That left them 15.7% above the 200-day moving average and just 3% below an inter-earnings high of $7.44, set the day before the release. The stock had rallied 43% off a 52-week low of $5.05 hit in late September. In other words, Inogen entered the print near the top of its range, with enthusiasm building. The quarter itself delivered lower guidance, compressed margins and a withdrawn profitability metric. The stock's positive AVWAP reading reflects that pre-report buying rather than anything in the results.
The bottom line is that Inogen traded a growth narrative for a restructuring narrative this quarter. The U.S. turn and new-product traction are genuine, and the cost program and buyback give the new CEO tools. But international reversed, margins and cash flow weakened, and guidance fell again, while long-term targets went unmentioned. Bears have legitimate ammunition, particularly with expectations elevated going in. The next few quarters must show whether cost savings and U.S. momentum can outrun European softness.
Read our earnings preview for Inogen, Inc.: https://www.earningswhispers.com/article/INGN/22311
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-15 | |
| Oct-01 |
Inogen sharpens business focus with $25m oxygen rental unit divestment
INGN +13.47%
Medical Device Network
|
| Sep-30 | |
| Sep-28 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-16 | |
| May-07 | |
| May-07 | |
| Apr-23 |
