Genpact's AI Engine Hits 30% Growth And Lifts EPS Guidance, But Flat Core Revenue And An ERP Cash Squeeze Temper The Beat
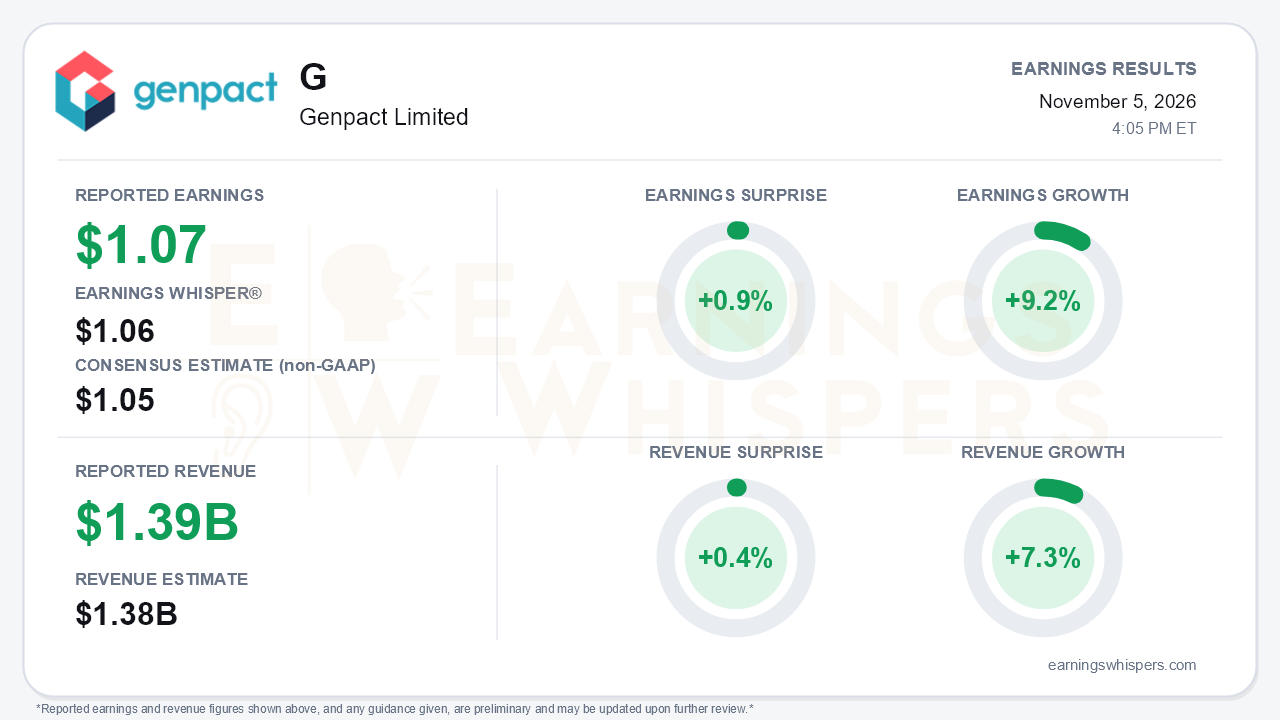
Genpact delivered a modest headline beat and a much stronger growth story underneath it. The company reported adjusted earnings of $1.07 per share on revenue of $1.385 billion, topping the $1.05 consensus by 0.9% and edging past the $1.06 Earnings Whisper number. Revenue beat the $1.38 billion consensus by 0.4%. Earnings grew 9.2% year over year by Earnings Whispers' measure, while Genpact cited 10.3% adjusted EPS growth against its own $0.97 prior-year figure. Revenue grew 7.3%, an acceleration from 6.7% in the first quarter and 7.1% in the second. The central tension is that the Advanced Technology Solutions segment is accelerating sharply while the larger Core Business Services base has stalled, and a weak cash quarter undercuts some of the earnings quality.
The quality of the beat deserves scrutiny. Gross margin was the standout at 38.0%, up 160 basis points year over year and well above the company's 36.6% guide, marking a 14th straight quarter of expansion. Little of that reached the adjusted operating line. SG&A rose about two points to 22.6% of revenue as Genpact keeps spending on Agentic Operations, so adjusted operating margin improved only to 17.8% from 17.7%. GAAP results were softer. Diluted EPS rose 7.2% to $0.89, net income grew just 4.0%, and net margin slipped to 10.9% from 11.3%. Stock-based compensation, which is excluded from adjusted figures, climbed to $31 million from $22 million. A diluted share count roughly 6.5 million lower than a year ago also flattered the per-share comparison.
The operating story is about mix. ATS revenue reached $405 million, up 30.3%, accelerating from 24.1% in Q2, 24% in Q1 and 15% in the fourth quarter of 2025. The segment now represents 29% of revenue, and management expects similar growth of roughly 30% in Q4. Core Business Services, at $980 million, was flat year over year after growing 1.9% in Q2 and 1.4% in Q1. It is guided down slightly in the fourth quarter, including a headwind of more than three points from deliberately exiting non-strategic work. Non-FTE revenue rose above 55% of the total, from 48% in Q1. That supports management's argument that revenue quality is improving even as the legacy base shrinks. High-tech and manufacturing slowed to 4.4% growth from 7.6% in Q2, a blemish worth monitoring.
Forward indicators strengthened, and management's tone turned more assertive, with executives describing "demand we cannot keep up with." Agentic bookings are now expected to exceed the $1 billion 2026 target "by a margin," which is more than five times the 2025 level. In Q2, management had said only that it was tracking to that figure. Genpact has signed 17 large deals year to date, already more than the 16 it signed in all of 2025. New wins include Woolworths, Nestlé and Volkswagen Financial Services Portugal. Full-year gross margin guidance rose to about 36.9% from 36.5%, and adjusted EPS growth guidance rose to at least 13%. That is the fourth consecutive increase in the EPS outlook. Revenue guidance, however, held at at least 7%, where it has sat since the year began, and adjusted operating margin guidance stayed at 17.7%. Management's preliminary 2027 view calls for similar revenue growth of about 7%, despite a modestly larger exit headwind. That outlook preserves a credible growth story without promising acceleration.
Bears have legitimate ammunition on cash. Q3 operating cash flow was only $93 million after $72 million in Q2, as an ERP implementation delayed invoicing and collections. Nine-month operating cash flow fell to $142 million from $526 million, and receivables swelled to $1.62 billion from $1.24 billion at year-end. Cash dropped to $499 million from $854 million. Part of that decline reflected $370 million of debt repayment and a $77.5 million earn-out payment, but the working-capital strain is real. Management also noted that agentic revenue remains minimal today, with longer ramps from booking to GAAP revenue. Q3 was also the first call for new CFO Sumita Pandit.
The market had already moved toward this story. Shares opened at $35.08 after the August report and stood at $40.78 entering this release, a 16.2% gain. The stock sat about 14.9% above its 200-day moving average and 2.7% below its inter-earnings high of $41.91, after rallying roughly 27% from a late-September low of $32.04. Investor sentiment swung from modestly negative (-0.14) to positive (+0.20), a meaningful shift in expectations. The Earnings Whispers trend readings are mostly positive, with momentum neutral. With shares near the top of their range, the bar for incremental upside is higher than the small headline beat implies.
The bottom line is that Genpact's pivot is visibly gaining traction, with 30% ATS growth, record bookings and a fourth straight EPS guidance increase. However, total growth remains anchored near 7% by a stagnant core business, margin gains are being reinvested, and ERP-related cash collection problems need to resolve before the earnings quality matches the narrative.
Read our earnings preview for Genpact Limited: https://www.earningswhispers.com/article/G/22291
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-28 | |
| Oct-19 | |
| Oct-16 | |
| Oct-15 | |
| Oct-14 | |
| Oct-08 | |
| Sep-15 | |
| Sep-10 | |
| Sep-08 | |
| Sep-03 |
