Mattel's Tariff-Aided Beat Can't Hide A Broad Guidance Cut As New Management Resets Expectations
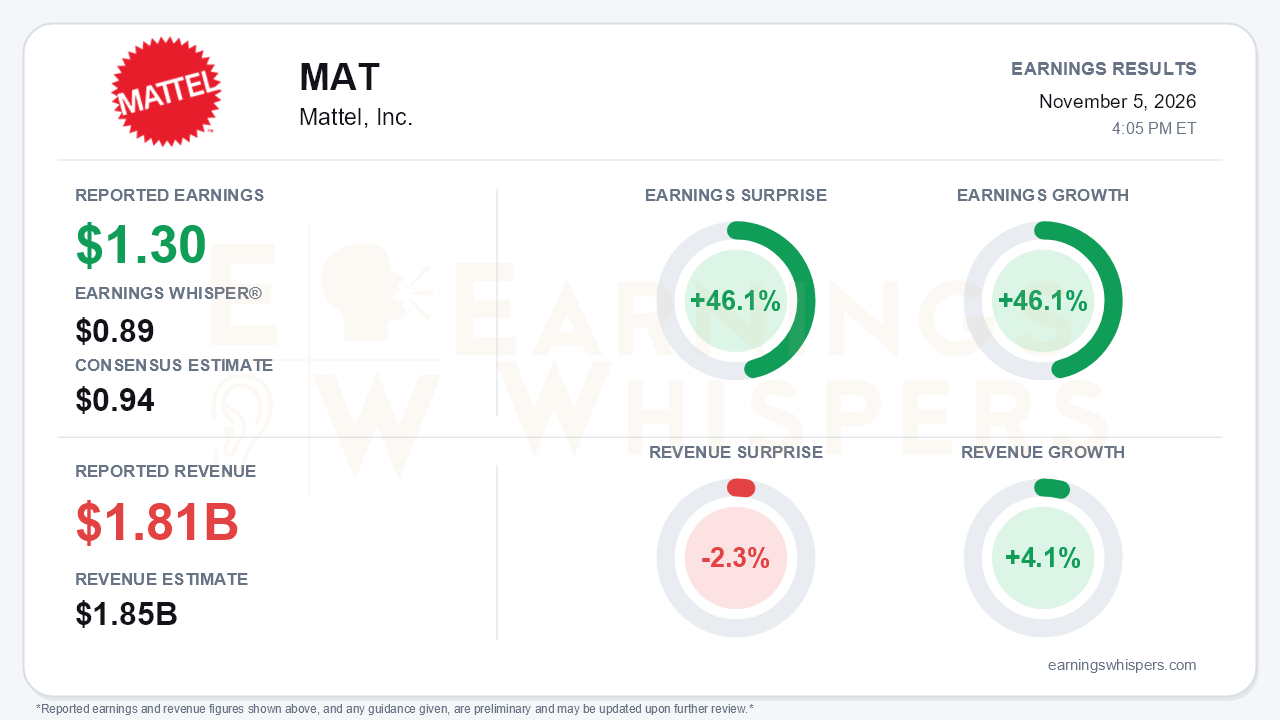
Mattel delivered a headline beat that the rest of the report undercut. Adjusted EPS of $1.30 cleared the $0.94 consensus and the $0.89 Earnings Whisper number by 46.1%, and earnings grew 46.1% year over year from $0.91. Revenue told a weaker story. Net sales of $1.807 billion rose 4.1% but missed the $1.85 billion consensus by 2.3%. New CEO Roger Lynch then cut full-year guidance on every line and declined to reaffirm the prior team's 2027 framework. That is the central tension: a strong-looking quarter was paired with a clear reset of forward expectations.
The quality of the beat deserves scrutiny. Adjusted gross margin jumped 480 basis points to 55.0%, but the company attributed the gain primarily to $88 million of tariff refunds. The call analysis puts the refunds' contribution at 490 basis points, which implies underlying gross margin slipped. Management said inflation and higher royalties more than offset cost savings, the Mattel163 contribution, and favorable currency. Other non-operational factors also helped:
- Share-based compensation swung to a $0.9 million credit from $22.3 million a year ago, reflecting forfeited awards tied to the former CEO's departure.
- The diluted share count fell about 10% to 286.8 million after heavy buybacks.
- The adjusted tax rate dropped two points to 22%.
Strip out these items and the quarter looks closer to modest top-line growth with flat-to-softer core profitability. Year-to-date adjusted EPS of $1.08 is exactly flat with last year, which better reflects the underlying earnings trajectory than the Q3 spike. Revenue growth also cooled to 4% from the 6% pace of the first nine months.
Beneath the headline, the brand mix remains lopsided.
- **Hot Wheels:** gross billings rose 7%, and management said the brand is on track for a ninth record year approaching $2 billion.
- **Growth areas:** Action figures and games grew double digits, helped by the newly consolidated Mattel163. Dolls rose 4% only because partner brands, notably KPop Demon Hunters, offset Barbie.
- **Barbie:** gross billings fell 9%. That is the more troubling detail, because the second-half plan built on new content, the Dreamhouse, and packaging was supposed to stabilize the brand.
- **Fisher-Price:** billings dropped 14%, and the infant, toddler and preschool category fell 16%.
- **Challenger categories:** excluding Mattel163, these declined, partly due to the lost Pokémon license.
Most importantly, management said point-of-sale trends decelerated late in Q3 and into Q4 across all major markets. That reverses the Q2 claim of positive year-to-date POS and continued top-line momentum.
The guidance cut is substantial, and it excludes all tariff refunds:
| Metric | Prior guidance | New guidance |
|---|---|---|
| Constant-currency sales growth | 3%–6% | 1%–4% |
| Adjusted gross margin | ~50% | ~48% |
| Adjusted operating income | $580–$630 million | $500–$570 million |
| Adjusted EPS | $1.27–$1.39 | $1.05–$1.20 |
The prior 2027 framework called for mid-to-high single-digit revenue growth, strong double-digit operating income growth, and a return to growth for Barbie. Management did not reaffirm it and deferred updated targets to February. The tone shifted from the prior regime's digital and entertainment narrative to Lynch's "clear-eyed" focus on core toys and return hurdles. That pivot raises open questions about digital and mobile gaming investments only months after the Mattel163 purchase.
Leadership turnover is extensive:
- Roger Lynch is the new CEO, and Peter Griffith is the new CFO.
- Steve Totzke returns as President and COO.
- President and Chief Commercial Officer Roberto Stanicki is departing for Netflix.
The balance sheet has also moved the wrong way. Net debt rose to $1.79 billion from $1.65 billion, and leverage increased to 2.7x from 2.5x. Trailing free cash flow improved to $440 million from $335 million in Q1, which provides some cushion.
The catalysts are now more about restructuring and optionality than near-term growth. Management plans an enterprise-wide efficiency and AI review, with plans due in February 2027. The Hot Wheels Netflix special reached No. 2 globally, and expanded Brick Shop capacity is under evaluation. Notably, management referenced external commentary and the board's openness to "actionable opportunities." The market is likely to read that as a possible strategic-interest angle.
That optionality likely helps explain the stock's path into the report. Shares hit a 52-week low of $12.40 on October 1, then rallied to $17.43 by mid-October. They entered earnings at $15.57, about 25.6% above the low but 10.7% below the quarterly high. The price is essentially unchanged from the $15.65 open after the August report and sits just 1.3% above the 200-day moving average. Investor sentiment improved meaningfully, from -0.50 to -0.21, but remains negative. Price and AVWAP trend readings are positive, reflecting the October rebound more than any fundamental improvement.
The bottom line is that Mattel's EPS beat was largely engineered by tariff refunds, a compensation reversal, and a shrinking share count. The operating signals point the other way: slowing POS, persistent Barbie and Fisher-Price declines, and lower underlying margins. A new management team has reset the bar with a guidance cut and a withdrawn 2027 outlook. Bears have legitimate ammunition, while the bull case increasingly rests on February's restructuring plan and any strategic interest rather than on the quarter itself.
Read our earnings preview for Mattel, Inc.: https://www.earningswhispers.com/article/MAT/22335
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-30 | |
| Oct-28 | |
| Oct-28 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 |
