Live Nation Beats On Record Attendance And Ticketmaster Raise, But Accounting Relief Flatters EPS And The Concerts Target Hinges On Q4
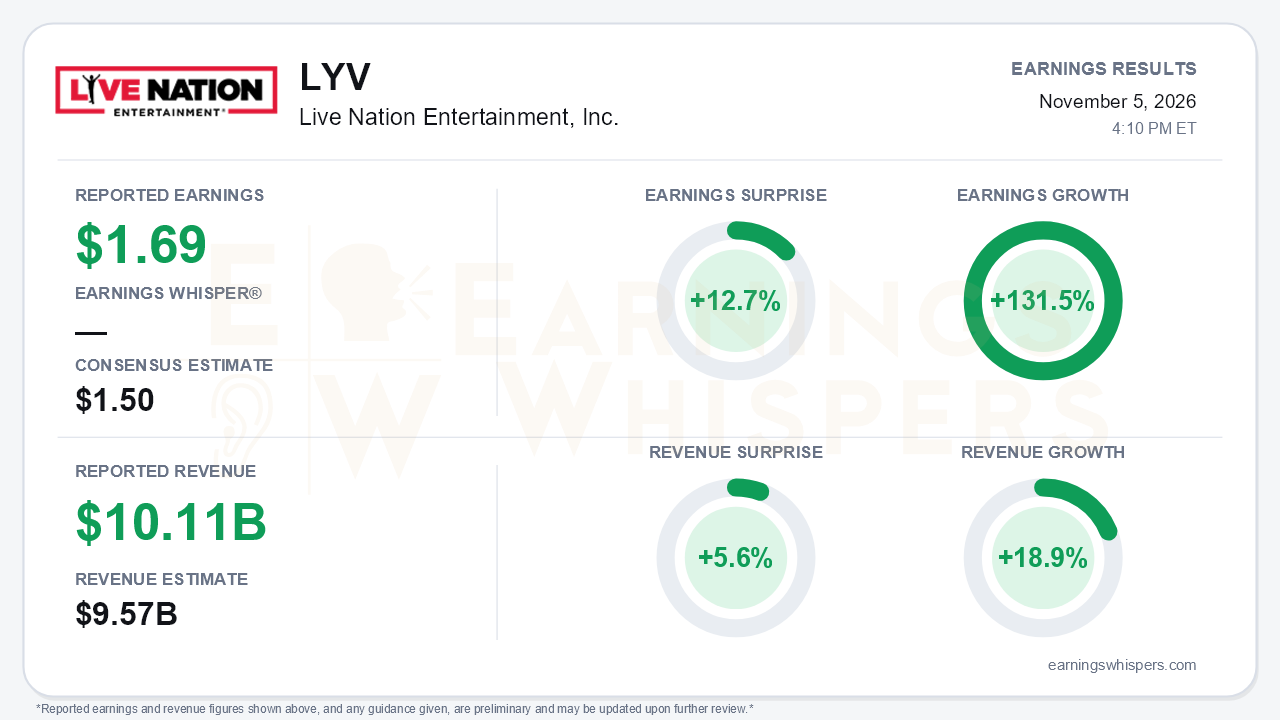
Live Nation Entertainment delivered a clean beat on both lines for the third quarter. Earnings of $1.69 per share topped the $1.50 consensus by 12.7%, and revenue of $10.105 billion beat the $9.57 billion estimate by 5.6%. Earnings grew 131.5% year over year and revenue rose 18.9%, driven by 61 million fans, up 19%, and international attendance up 29%. The operating story is strong and getting stronger. However, the headline EPS growth overstates how much more the business actually earned, and the full-year concerts commitment still depends on a demanding fourth quarter. That gap is the central tension.
The quality of the EPS beat deserves scrutiny. Net income attributable to Live Nation rose only about 4%, to $447.8 million from $431.5 million. The near-tripling in diluted EPS came mostly from below the operating line. Accretion of redeemable noncontrolling interests fell to $42.6 million from $259.9 million, which management attributes to continued strong performance at OCESA and other partners. Diluted EPS also reflects the convertible add-back and a share count of 256 million versus 235 million. The operating results were still solid. GAAP operating income rose 13% to $892 million, and adjusted operating income (AOI) rose 14% to $1.18 billion, with double-digit AOI growth in all three segments. Year-to-date GAAP operating income is down 25%, but that reflects the $450 million governmental investigations and litigation charge taken earlier in the year, which is excluded from AOI.
Growth clearly accelerated in the quarter:
- **Revenue:** Q3 revenue rose 19%, against 14% for the nine months.
- **Consolidated AOI:** Q3 AOI grew 14%, against 9% year to date.
- **Concerts AOI:** Q3 growth was 17%, up from just 4% through nine months.
Margins did not keep pace. Revenue outran AOI, so the consolidated AOI margin slipped to roughly 11.7% from about 12.2%. On the call, management did not repeat the margin-expansion message it flagged in the second quarter. Instead it pointed to three drags:
- a lower-margin stadium mix;
- pre-opening costs, cited at $50 million in 2026 versus $25 million in 2025;
- a double-digit rise in prepaid advertising expense that will be written off in the fourth quarter.
The call preserved a credible growth story elsewhere. Ticketmaster's AOI outlook has risen on every call this year, from "some growth" to mid-single digits and now high single digits. The expected secondary-ticketing headwind never materialized because sports resale offset weaker concert resale, and the company added more than 20 million net new client tickets, mostly international. Full-year fan guidance moved to nearly 180 million, about 3% above the prior outlook, and Venue Nation is tracking toward more than 75 million fans. Sell-through is running ahead of last year and cancellations below it. Management was emphatic that it sees no consumer pullback. October ticket sales rose more than 20%, and big 2027 on-sales for Harry Styles, Bruno Mars, Oasis and Metallica, along with double-digit growth in 2027 primary ticketing GTV, give an early read on next year.
Bears have legitimate ammunition on the concerts outlook and the balance sheet. Management reaffirmed rather than raised its double-digit full-year concerts AOI target. With the segment up only about 4% through nine months, hitting it requires the seasonal fourth-quarter loss to narrow by at least roughly $30 million, even as pre-opening costs and advertising write-offs land. Venue expansion is also consuming capital:
- Capex is heading toward nearly $1.1 billion.
- Cash paid for acquisitions reached $572 million year to date.
- The current portion of debt climbed to $1.86 billion.
- Several venue deals in Prague, Paris, Santiago and Copenhagen are still pending.
Cash generation provides some cushion. Year-to-date adjusted free cash flow rose 25% to $1.6 billion, with conversion from AOI improving to 69% from 60%. Management deferred multi-year venue, pre-opening and AI detail to next week's Investor Day, which becomes the next catalyst.
Investors came into the print cautious. Earnings Whispers sentiment, which runs from -1 to +1, was mildly negative after the last report and turned more negative, falling from -0.14 to -0.24. Price action has been similarly noncommittal. At $183.18 ahead of the release, shares were essentially unchanged since the open after the July report, down 0.9%. They sat 9.5% above the 200-day moving average and 3.2% below the $189.25 52-week high set in mid-August, after recovering about 11% from an October 1 low of $164.82. Momentum and AVWAP trend readings are positive, consistent with that rebound. The stock therefore entered earnings in the upper part of its range while sentiment soured, an uneasy combination for a report that is strong on volume but less convincing on margins.
The bottom line is that Live Nation's demand engine is running hotter than expected. Record attendance, a third straight Ticketmaster guidance raise and early 2027 visibility support management's goal of sustained double-digit growth. The headline EPS surge, though, is largely an accretion story rather than an earnings-power story, and margins are flat at best as stadium mix and venue build-out costs rise. Fourth-quarter concerts execution and the Investor Day venue roadmap will determine whether the top-line momentum turns into the margin progress that skeptics want to see.
Read our earnings preview for Live Nation Entertainment, Inc.: https://www.earningswhispers.com/article/LYV/22333
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-07 | |
| Oct-06 | |
| Sep-23 | |
| Sep-20 | |
| Sep-16 | |
| Sep-14 | |
| Sep-14 |
