AEye's Revenue Inflects 912% And It Issues First Guidance, But A Rising Burn Keeps The Balance Sheet In Focus
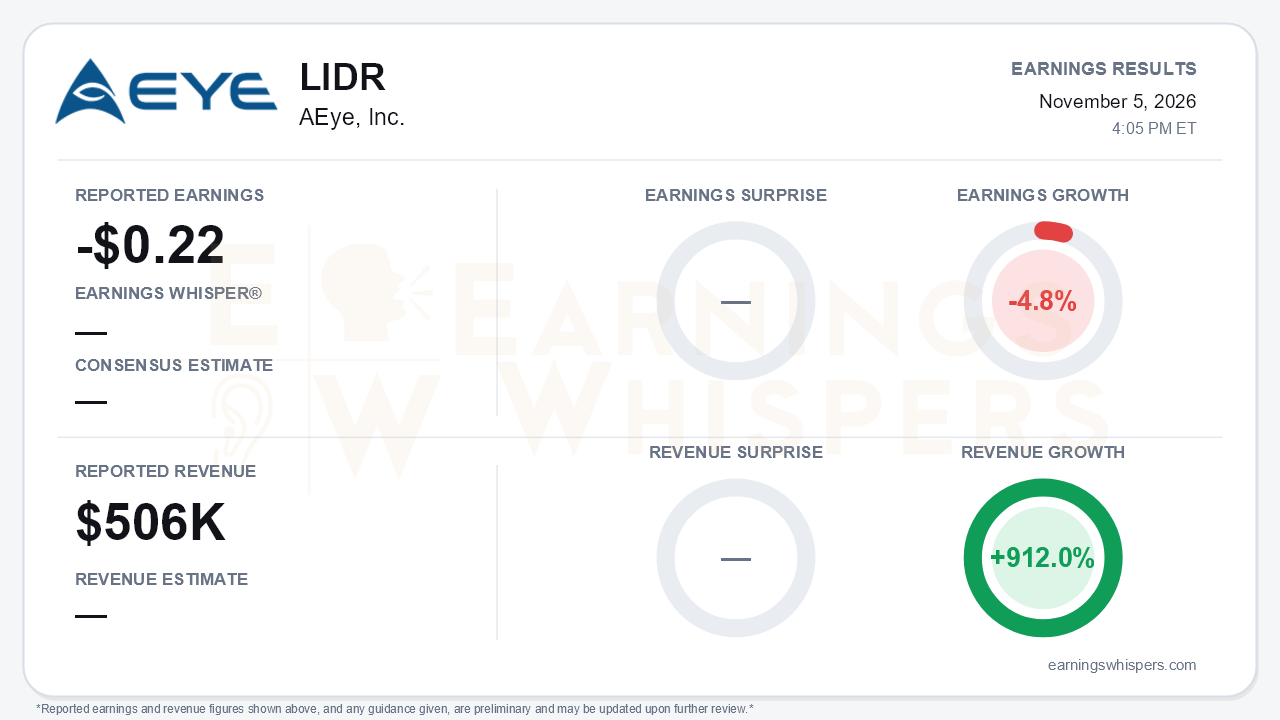
AEye (NASDAQ: LIDR) delivered the quarter that turns its commercialization story into revenue. Revenue reached $0.51 million for the September quarter, up 912.0% year over year, and management issued its first-ever revenue guidance. It expects fourth-quarter revenue of roughly $1 million, about double the third quarter, and calls that level a new quarterly baseline heading into 2027. The bottom line did not move the same way. Earnings Whispers puts the loss at $0.22 per share, with earnings down 4.8% year over year, and there was no consensus estimate to measure against. The central tension is that the top line is ramping steeply from a tiny base while the cost of funding that ramp is still rising.
How the loss reads depends on which figure you use. The company reported a GAAP net loss of $11.2 million, or $0.24 per share, and a non-GAAP net loss of $7.2 million, or $0.15 per share. Earnings Whispers' normalized $0.22 sits between the two. In dollar terms the GAAP loss widened from $9.3 million a year ago, driven mostly by stock-based compensation, which tripled to $3.3 million. Weighted shares rose to 46.5 million from 31.3 million, so per-share comparisons flatter the trend. Below the line, the picture improved: non-GAAP operating expenses fell to $7.7 million from $8.2 million in the second quarter, and the non-GAAP loss narrowed from $7.6 million. Gross margin, while still negative, improved 45 percentage points sequentially, from (80)% to (35)%. Management credited a richer mix, a lower bill of materials and lower warranty reserves tied to better Apollo return rates.
The operating metrics show momentum building across the business:
- **Revenue:** quarterly revenue rose from $101 thousand in Q1 to $202 thousand in Q2 to $506 thousand in Q3, the fifth straight sequential gain. Nine-month revenue of $809 thousand is already about 3.5 times all of 2025.
- **Customers:** revenue-generating customers increased from 16 at the end of 2025 to 32, up 28% from last quarter. Active technical engagements now exceed 200.
- **Conversions:** management expects several conversions within six to nine months as 12- to 18-month integration cycles mature.
- **Diversification:** the binding, multimillion-dollar Lunar Outpost program for NASA's Artemis lunar terrain vehicle began contributing revenue. STRATOS booked its first revenue through Swiftstrike AI's counter-drone work, and a second sports-analytics customer followed Alive3D.
- **Defense:** the lead defense customer placed its fifth order, up from its third last quarter, with growing volumes.
The forward catalysts are substantial for a company of this size. Management says it is moving into a second phase of commercialization. It hired a Chief Revenue Officer, realigned its go-to-market effort around converting the pipeline, and plans to unveil a new product at CES in January. The fourth-quarter guide is the most concrete near-term test, and its quality deserves scrutiny. It leans heavily on Lunar Outpost, a government program with hours-based revenue recognition, so milestone timing could easily shift dollars between quarters. Automotive remains slow. The $30 million transportation OEM program, previously flagged for broader deployment in the second half of 2026, received no update. Management also cited account-management capacity as a limit on how much inbound demand it can service.
Bears have legitimate ammunition on cash. Third-quarter cash consumption rose to $8.3 million from $7.5 million, partly because of an inventory build. Full-year 2026 burn is now set at $35 million, the top of the $30-35 million range the company had reaffirmed all year. Cash and securities have fallen from $86.5 million at year-end to $63.1 million. The runway language also slipped from "well into 2028" to "into 2028." There is a constructive offset: management targets roughly $30 million of cash use in 2027, and the higher receivables, inventory and contract liabilities reflect real program billings rather than speculative spending. Still, revenue of about $1 million a quarter covers only a small fraction of an $8 million quarterly burn.
The market context is thin. Shares opened at $1.19 after the August report, well below the 200-day moving average of $1.51. That suggests the stock was being treated as a show-me story heading into this print, though current price and sentiment data were not available to judge the reaction.
The bottom line is that AEye finally produced the evidence turnaround skeptics have demanded: accelerating revenue, a doubling customer count, diversified wins and a dated revenue target. The call preserved a credible growth story. Even so, revenue remains under $1 million a quarter, margins remain negative, and the cash burn is rising rather than falling, so the investment case still depends on converting the pipeline before the balance sheet becomes the headline.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Oct-22 | |
| Sep-23 | |
| Sep-16 | |
| Sep-09 | |
| Sep-03 | |
| Sep-01 | |
| Sep-01 | |
| Sep-01 | |
| Aug-21 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 |
