Karat Packaging Misses Badly As Freight And Resin Costs Swamp 38% Online Growth; Shares Entered The Report Near Their Highs
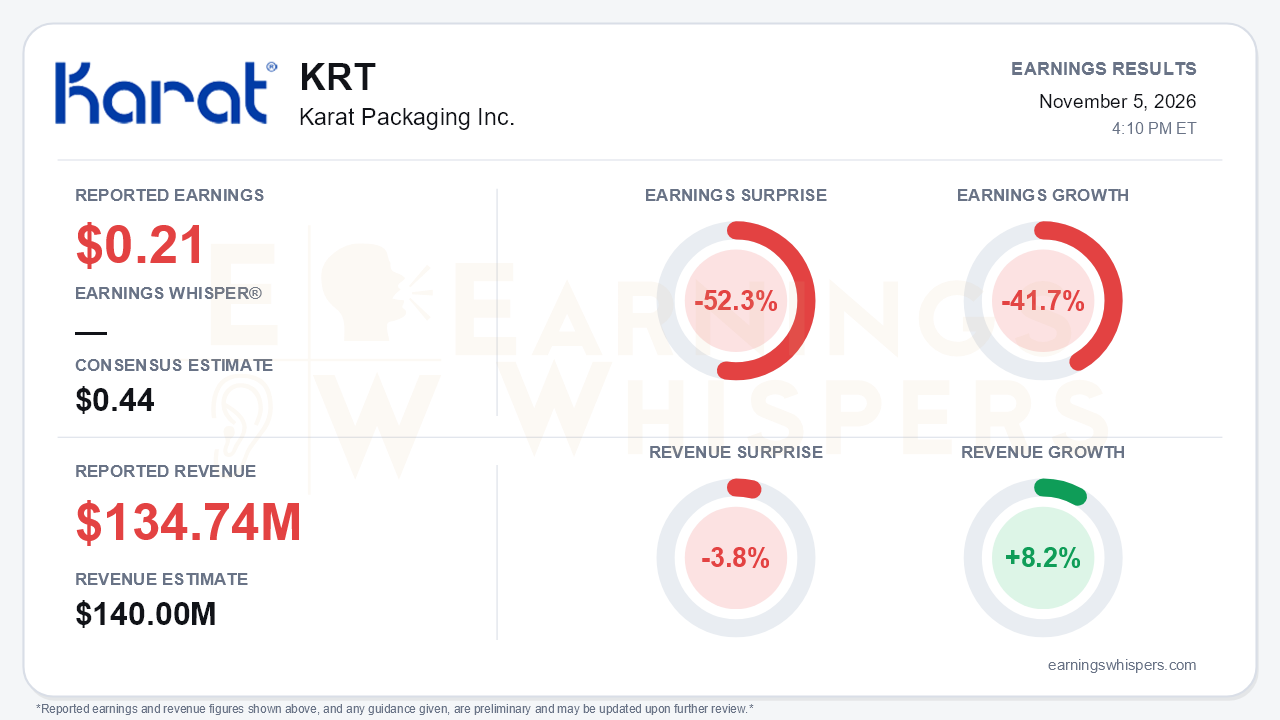
Karat Packaging (NASDAQ: KRT) delivered a decisive third-quarter miss. Earnings Whispers puts earnings at $0.21 per share against a $0.44 consensus, a 52.3% shortfall, and a 41.7% decline from a year ago. The company's own figures were $0.22 on a GAAP diluted basis and $0.24 adjusted, versus $0.36 and $0.37 last year. On any of those measures the quarter fell far short. Revenue of $134.74 million rose 8.2% but missed the $140.0 million consensus by 3.8%. It also fell about $2.5 million short of management's own low-double-digit growth guide. The company then lowered its outlook. The central tension is that the demand story is getting better while the profit model is getting worse. Online sales are accelerating and new chain accounts keep arriving, but freight, resin and fuel inflation are consuming the incremental gross profit, and then some.
The margin damage was broad. Gross margin slipped to 33.5% from 34.5% a year ago, missing the 35-37% guide. Product costs climbed to 50.6% of sales from 48.9%. Ocean freight added $2.4 million on 11.7% more containers and a 17.0% higher average rate. The larger problem sat below gross profit. Operating expenses jumped 17.2%, roughly double the pace of sales. Adjusted EBITDA fell to $8.9 million from $13.1 million, and margin compressed to 6.6% against a 9-11% guide. That raises a real question about the quality of the online growth. Online revenue rose about $7.4 million. Against that, the company absorbed $2.2 million in higher online shipping costs, $0.9 million in platform fees and $0.7 million in marketing. Management also noted on the call that FedEx fuel surcharges have risen as much as 40% and are hard to pass through. The fastest-growing channel is currently among the least profitable dollars Karat sells.
The call also exposed a steady deceleration beneath the headline. Total growth has stepped down every quarter: 13.7% in Q4 FY25, then 12.9%, 9.9% and now 8.2%. The core chains and distributors channel slowed to 3.9% growth from 9.0% in Q2 and 15.1% in Q1. Retail fell to $4.6 million from $5.6 million. Online is the clear bright spot, with growth accelerating from 1.9% four quarters ago to 23.6% in Q2 and 37.7% now. Regional gains of 19% on the East Coast and 22% in the Midwest also point to real share capture. Management blamed the revenue shortfall on chain start delays, as new customers deplete inventory from prior vendors. That is plausible, but it shifts revenue into 2027 rather than recovering it this year.
Guidance leans on several things going right at once. Full-year sales growth was trimmed to 9-11% from low double digits. Full-year gross margin guidance was cut to 39-41% from the low 40s. Both full-year margin figures are flattered by IEEPA tariff refunds. Those refunds contributed 660 basis points to nine-month gross margin, $20.2 million to net income and $1.00 to adjusted EPS. The fourth-quarter guide is the cleaner read on the underlying business:
- **Gross margin:** 33-35%.
- **Adjusted EBITDA margin:** high single digits, well below the 11-13% underlying expectation discussed on the Q1 call.
- **Revenue growth:** 9-11%, which implies acceleration from Q3 while management says it is receiving only 70-80% of needed product and shorting customers, a situation it likened to 2022.
The catalysts that could support recovery are concrete:
- Four additional chain accounts were won, on top of Q2's four. The Q2 group began shipping in October and has expanded into more product lines starting in early 2027.
- The Orlando distribution center is due online in November.
- Price increases were taken in Q4, with a 3-13% hike set for January.
- Sourcing from Indonesia, Malaysia and South America has risen to 19.4% of purchases.
- Management expects fiber and paper sales to roughly double in 2027.
The risks are equally concrete. Spot container rates are running $4,500-$6,000 against a roughly $2,500 contract rate, carriers have cut about 40% of North American capacity, and diesel is at $6.50-$7.50 a gallon. Management's tone shifted from Q2's cost-relief narrative to an explicit admission that results came in below expectations. It is now counting on pricing and geopolitics to restore margins.
The market setup magnifies the miss. Investor sentiment swung from -0.15 after the prior report to +0.18 heading into this one, a meaningful move from mildly negative to modestly positive. The stock rose 19.7% from its post-August opening of $44.81 to $53.63. That leaves it 48% above its 200-day moving average and only 4.3% below the 52-week high of $56.06 set October 12. Price and AVWAP trend readings were positive going in. In short, KRT entered the report priced for operating improvement, and the quarter delivered deterioration in margins, a guidance cut and a slowdown in its largest channel.
The bottom line is that Karat's growth engine is changing shape more than it is stalling. Online momentum and chain wins give the company a credible 2027 revenue story. However, this quarter showed that the growth is currently margin-dilutive and highly exposed to freight and resin costs the company does not control. Excluding tariff refunds, profitability is moving the wrong way, and the recovery case now depends on price increases holding and supply constraints easing. Bulls still have a story, but bears have legitimate ammunition, and the stock's run into the report left little cushion for that reality.
Read our earnings preview for Karat Packaging Inc.: https://www.earningswhispers.com/article/KRT/22324
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-22 | |
| Aug-19 | |
| Aug-06 | |
| Aug-05 | |
| Jul-23 | |
| Jul-10 | |
| Jun-29 | |
| Jun-29 | |
| May-29 | |
| May-20 | |
| May-07 |
