Perdoceo Beats On Margins And Buybacks As CTU Stalls, Leaving South University To Carry The Growth Story
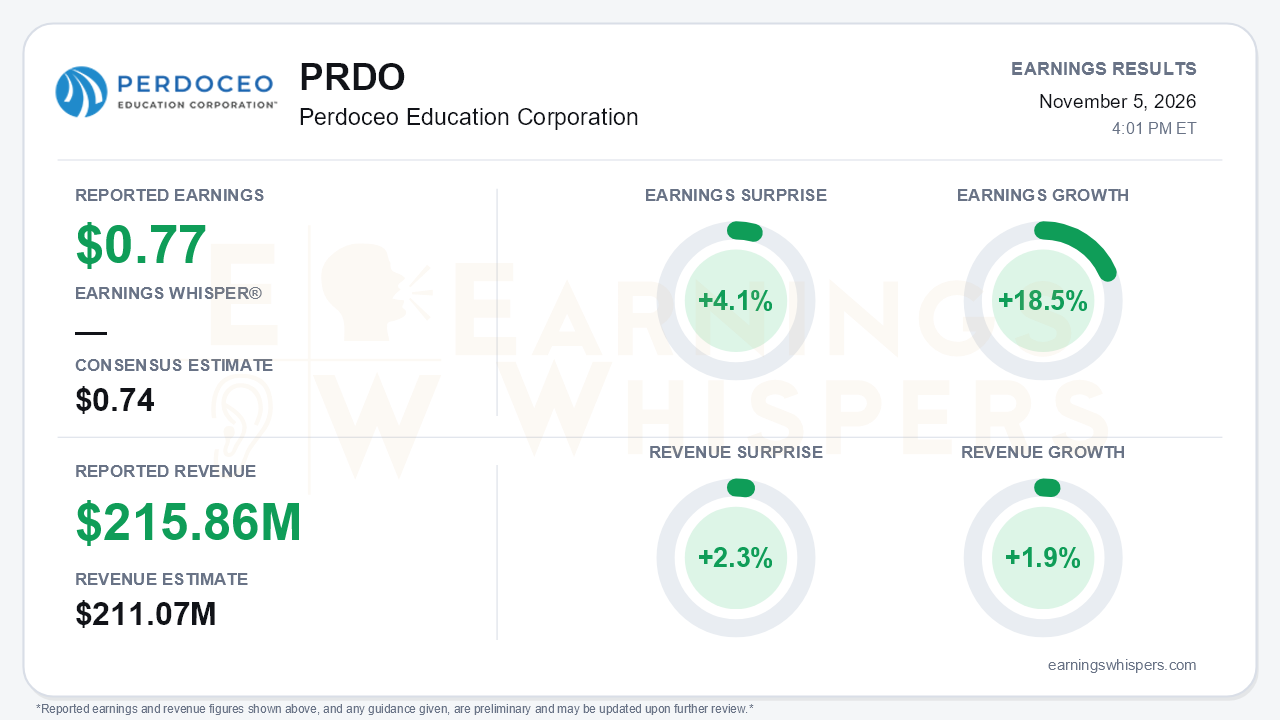
Perdoceo Education delivered another clean beat for the September quarter, but the earnings power is clearly outrunning the top line. Adjusted EPS of $0.77 topped the $0.74 consensus by 4.1% and grew 18.5% year over year. Revenue of $215.86 million beat the $211.07 million estimate by 2.3% but grew just 1.9%. Earnings Whispers characterizes the outlook as in line. That is the central tension: Perdoceo keeps converting flat-to-low-single-digit revenue growth into double-digit EPS growth, while the organic enrollment engine at its largest institution has stalled. The South University acquisition is now the clearest answer to where the next leg of growth comes from.
The quality of the beat deserves scrutiny, though it holds up reasonably well. GAAP EPS rose 16.7% to $0.70, and adjusted operating income rose 8.4% to $66.1 million. That figure topped the $64-65 million management had guided on the prior call, and adjusted EPS also exceeded the company's own $0.73-0.74 target. Operating margin expanded to 25.5% from 24.1%, helped by lower educational services costs and lower depreciation. Below the operating line, the per-share result got a meaningful lift from a diluted share count that fell to 63.3 million from 66.0 million. Q3 EPS growth also trailed the 22.8% adjusted EPS growth posted for the first nine months, so the pace is moderating even as it stays strong. Operating cash flow nearly doubled to $79.7 million, but the company attributes part of that to working-capital timing, so it overstates the underlying improvement.
The segment mix tells the more important story. CTU, the profit anchor, grew revenue just 0.3%, and its operating income fell 6.1% as legal fees tied to previously disclosed litigation stayed elevated. Its enrollment trajectory is the real concern. CTU enrollment growth slid from +6.6% in Q4 2025 to +1.9%, then +0.6%, and was essentially flat in Q3 at 31,870. Management now expects CTU to stay flat through year-end and return to growth in 2027, citing record graduations. That walks back the earlier expectation of 2026 growth accelerating in the second half. The offsets came elsewhere:
- **St. Augustine:** revenue rose 9.8%, and adjusted operating income climbed to $11.7 million from $7.2 million.
- **AIU System:** enrollments rose 7.5%, and operating income jumped 24.9% on essentially flat revenue. New AI-focused programs are drawing encouraging demand.
Even the bright spots carry caveats. St. Augustine's enrollment growth slowed to 3.2% from 6% in Q2, and AIU is guided lower for Q4 enrollments on calendar timing.
Guidance moved in the right direction, but modestly. The full-year adjusted operating income range is now $260-263 million, the third straight call where the floor moved higher. The top end has never budged, however, so the raises are narrowing the range from below rather than expanding the ceiling. The implied full-year adjusted EPS of roughly $3.15-3.19 sits above the $3.10-3.16 range from the Q2 call. The more consequential development is South University, which brings about 10,500 students, eleven campuses and online programs, plus graduate health offerings including PA, PharmD and nursing. The deal requires roughly $130-150 million in cash at closing, plus $18 million deferred and up to $56 million in EBITDA-based earn-outs. All of it is fundable from the $777 million cash pile, and management expects the deal to be accretive to adjusted operating income in 2027. Bears have legitimate ammunition here too:
- **Closing risk:** completion depends on regulatory and accreditor approvals, with closing no earlier than April 2027.
- **Integration risk:** absorbing eleven campuses and an online operation adds execution complexity.
- **Graduate loan exposure:** a bigger graduate health portfolio increases exposure to the elimination of Grad PLUS and to new graduate loan limits.
The market had not been rewarding the margin story heading into the print. Shares closed at $29.99 on November 4, down 7.5% from the $32.42 open following the August report. The stock had given back the entire post-Q2 spike to a $35.05 high and sat just 2.6% above the quarter's low of $29.24, set two days before this release. It also traded nearly 10% below its 200-day moving average of $33.30, with price and AVWAP trend readings negative even as momentum turned positive. Investor sentiment improved from -0.41 to -0.34, which is a modest shift and still decidedly negative. Investors appear to be discounting the CTU slowdown and regulatory overhang more heavily than the steady beats.
The bottom line is that Perdoceo executed well on profitability, cash generation and capital returns, and the call preserved a credible growth narrative through AIU, St. Augustine and South University. The core issue skeptics are focused on, however, remains unresolved: CTU has stopped growing, organic revenue is crawling, and EPS growth leans on margins and a shrinking share count. Until CTU enrollment turns, or South closes and proves accretive, the stock's discount to its 200-day average reflects a reasonable debate rather than an obvious mispricing.
Read our earnings preview for Perdoceo Education Corporation: https://www.earningswhispers.com/article/PRDO/22364
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Sep-14 | |
| Sep-14 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-22 | |
| May-20 | |
| May-07 | |
| May-07 | |
| Apr-21 |
