NGL Energy Raises Guidance Again As Water Strength Offsets A Crude Impairment And Tighter Liquidity
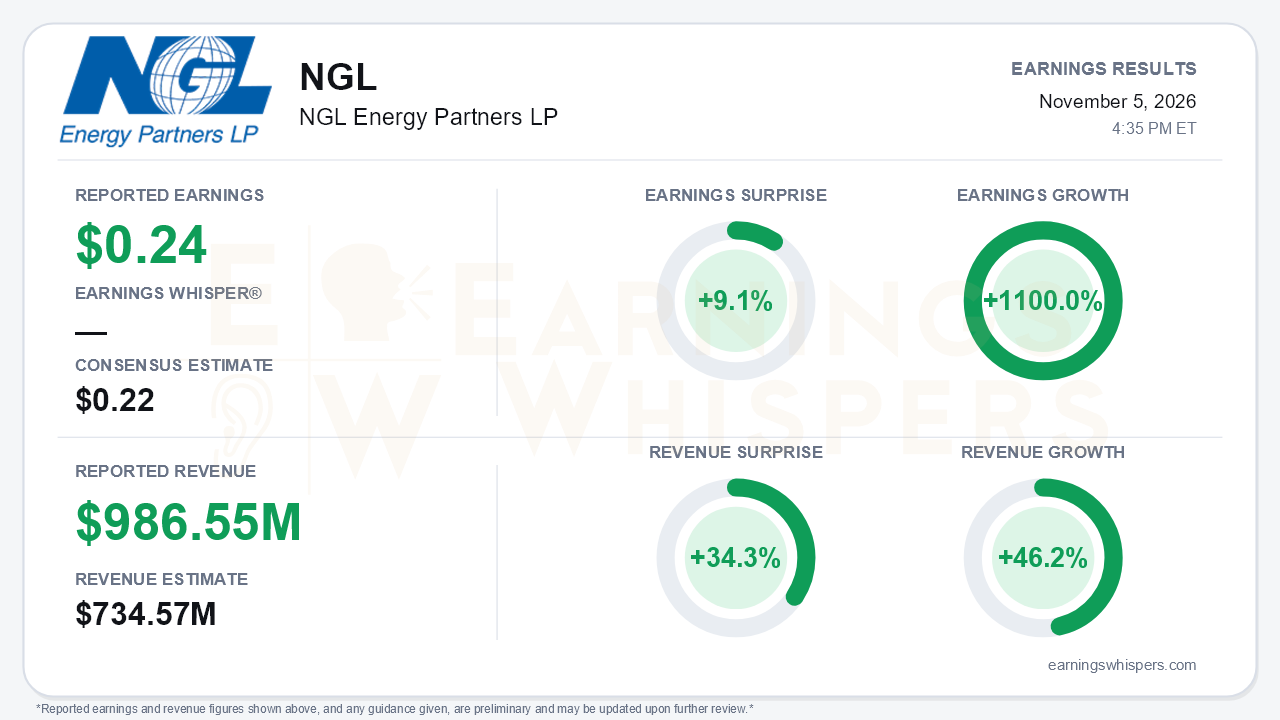
NGL Energy Partners delivered a fiscal second-quarter beat on the figures investors track most, and raised full-year guidance for the second straight quarter. Adjusted earnings of $0.24 per unit topped the $0.22 consensus by 9.1% and grew 1100.0% year over year. Revenue of $986.55 million beat expectations by 34.3% and rose 46.2%. Management lifted fiscal 2027 Adjusted EBITDA guidance to $735-$745 million, up from $725-$735 million last quarter and $715-$725 million originally. The central tension is that Water Solutions keeps outrunning the plan, while everything around it is getting harder: the crude business, the GAAP income statement and the balance sheet.
The quality of the beat deserves scrutiny. On a GAAP basis, NGL swung to a loss from continuing operations of $42.6 million, or $0.51 per common unit, from income of $29.8 million a year ago. Two items drove the loss: a $58.1 million impairment in Crude Oil Logistics and $35.6 million of net unrealized derivative losses, mostly on skim oil hedges after Iran-related crude volatility. Both are excluded from Adjusted EBITDA, which rose 15% to $192.4 million. The revenue surprise also flatters the story. Most of the gain came from product sales, but product cost of sales rose even faster, so the top-line jump did little for profit. The real earnings engine was Water Solutions, where segment Adjusted EBITDA climbed to $178.3 million from $151.9 million. Distributable cash flow improved to $78.5 million from $64.5 million, helped by lower preferred distributions.
The water operating trends remain strong. Physically disposed volumes set another record at about 3.45 million barrels per day, up 22.9% from a year ago and up from 3.32 million in the first quarter. Operating cost per barrel fell to $0.20 from $0.21 last quarter and $0.22 a year ago. Permitted injection capacity rose about 255,000 barrels per day in the quarter, roughly 450,000 so far this fiscal year. The CEO said water is running more than $20 million ahead of budget through the first half. Beneath that, momentum is less linear than the guidance raise suggests:
- Segment EBITDA was essentially flat sequentially, at $178.3 million versus $179.9 million.
- Paid-volume growth eased to about 11% from about 12%.
- Skim oil revenue rose $10.6 million to $38.6 million, partly on higher crude prices for unhedged barrels.
- Crude Oil Logistics weakened further, with segment EBITDA down to $11.9 million from $16.6 million and Grand Mesa volumes down to about 64,000 barrels per day from 74,000 in the first quarter.
The forward story got bigger, and so did the funding bill. Growth capex was raised from about $200 million to $250-$270 million for incremental contracted Delaware Basin takeaway projects. Most of the benefit lands in fiscal 2028, and management now explicitly expects EBITDA growth that year. The LEX II Extension, an 81-mile system with about 560,000 barrels per day of capacity backed by a new long-term volume commitment, is expected in service within weeks. Optionality also emerged from a memorandum of understanding with a data center developer for desalinated produced water. However, the key Texas discharge permit has been called imminent for several quarters running. The capex front-loading has a cost:
- Liquidity fell to about $129.7 million.
- ABL borrowings reached $249 million, even after the facility was upsized to $475 million.
- Management reaffirmed its year-end leverage target of about 4.0x and reiterated plans for Class D preferred redemption and eventual distribution reinstatement, but gave no new specifics.
- Bears can argue that heavier spending may push back the timing of both.
The market setup is more complicated than the surprise implies. Investor sentiment stayed positive but weakened meaningfully into the report, falling from 0.23 to 0.05. Shares closed at $15.52 before the release, down 8.7% from the open after the prior report. They have given back much of the run to a 52-week high of $19.06 on September 1 and sit 18.6% below that peak. The stock still holds about 4% above its $14.92 200-day moving average and 7.1% above its October low of $14.49. The internal trend readings are mixed, with momentum positive and AVWAP negative, consistent with a stock that has cooled without breaking down.
The bottom line is that NGL's water franchise continues to justify higher guidance and now extends visibly into fiscal 2028, and that is what matters most for the equity. The adjusted beat, however, sits on top of a GAAP loss, a shrinking crude business, crude-price-sensitive skim income and thinner liquidity. Investors who had grown more cautious will want to see LEX II contribute on schedule, water EBITDA resume sequential growth, and capital-return milestones advance before giving the guidance raise full credit.
Read our earnings preview for NGL Energy Partners LP: https://www.earningswhispers.com/article/NGL/22345
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-14 | |
| Sep-17 | |
| Aug-05 | |
| Aug-04 | |
| Aug-03 | |
| Jul-31 | |
| Jul-15 | |
| May-29 | |
| May-28 | |
| May-27 | |
| May-12 | |
| May-07 |
