Astrana Health Misses Consensus As Record EBITDA Meets Unchanged Guidance And Worsening Medicaid Costs
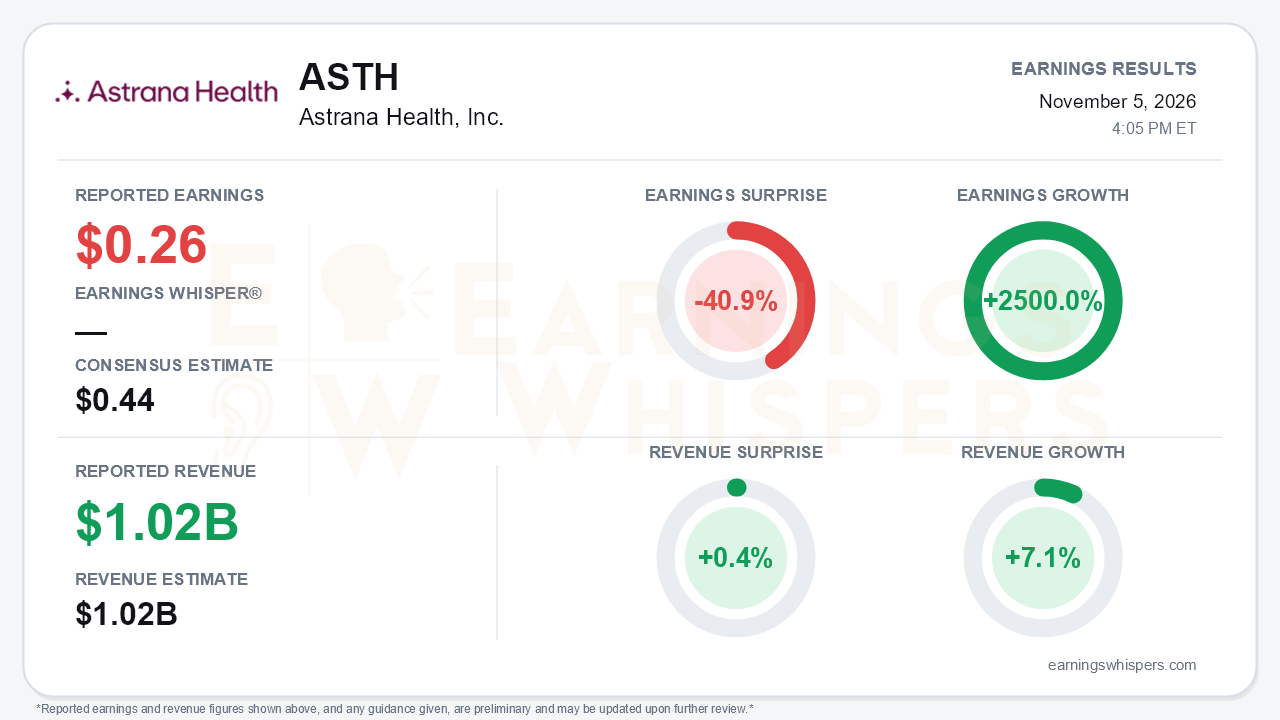
Astrana Health reported third-quarter earnings of $0.26 per share, 40.9% below the $0.44 consensus estimate. Revenue of $1.024 billion was a record and edged past the $1.02 billion consensus by 0.4%. On paper, earnings grew 2,500% year over year, but that figure reflects a jump from just $0.01 a year ago, when acquisition costs and a $13.0 million legal charge depressed results. The company's adjusted EPS of $0.71 tells a different story than the GAAP figure, and the gap between the two needs explaining. Even the adjusted number rose only 4%, a sharp slowdown from 36% adjusted EPS growth for the nine-month period. The central tension is that Astrana delivered record operating profit but did not raise its outlook, and the call introduced new cost-trend concerns.
The deceleration is largely mechanical. Revenue growth slowed to 7.1% from 33% for the nine months because the Prospect Medical acquisition now sits in both periods. That makes this the first clean look at organic growth. On that basis, adjusted EBITDA of $77.2 million, up 13%, was respectable. It landed near the top of the $72.5 to $77.5 million range management guided after Q2, and margin edged up to 8% from 7%. Care Partners operating income nearly doubled, up 94%.
Several factors kept the improvement from reaching GAAP earnings per share. Stock-based compensation roughly doubled to $15.6 million. Net income attributable to non-controlling interests rose to $7.3 million from $0.7 million, so a large share of the $20.3 million in consolidated net income went to minority owners rather than Astrana shareholders. Care Delivery also posted an operating loss. The quality of the beat at the EBITDA line deserves scrutiny as well. Management acknowledged that Q3 benefited from a non-recurring Medicare Shared Savings Program accrual and $5 to $10 million of risk-adjustment sweeps. That helps explain why fourth-quarter adjusted EBITDA guidance of $48.5 to $61.5 million is both much lower than Q3 and unusually wide.
The call preserved a credible growth story, but with more caveats than in prior quarters. On the positive side:
- Capitation revenue grew about 8.5% despite Medicaid and exchange attrition.
- Medicare Advantage membership grew at a high-single-digit organic rate.
- Texas full-risk cohorts moved from "in line" to ahead of plan.
- Full-risk revenue is on track to reach roughly 82% of capitation by year end, up from 80% in Q1.
- Prospect retention exceeds 99%, and synergies are tracking toward the high end of the $12 to $15 million target.
The cost picture moved the other way. Medicaid medical cost trend, described as favorable in Q1 and in line in Q2, is now running above assumptions, with early signs of adverse selection. Commercial trend is slightly elevated on clinician-administered drugs. Management also adjusted several expectations downward:
- It now assumes another 10% to 15% Medicaid membership decline in 2027, creating a mid-single-digit EBITDA growth headwind.
- Its medium-term EBITDA growth framing softened from "mid-to-high teens" to "at least mid-teens."
- G&A is now expected to run about 6.2% of revenue for the full year, versus an earlier target of exiting the year near 6%. Q3 came in at 6.6%.
Full-year guidance was narrowed around unchanged midpoints: revenue of $3.9 to $4.0 billion, adjusted EBITDA of $261 to $274 million, and free cash flow of $107.5 to $130 million.
The forward catalysts are real. Astrana closed a Georgia IPA tuck-in and signed care enablement clients in Connecticut and California. It also added Medicare Advantage partnerships effective January 2027, including Alignment Healthcare, and expects the share of members in 4-star plans to rise from about 30% to more than 50%. The balance sheet is improving: net leverage fell to about 2.2x from 2.6x at the end of 2025, and the company has repaid $116 million of debt year to date. Bears have legitimate ammunition, however. Nine-month free cash flow of $105.4 million trails last year's $110.4 million. Other open issues include an unsized September cybersecurity incident, the end of ACO REACH after 2026, and an unremediated material weakness.
The market setup is more demanding than the revenue beat implies. Investor sentiment improved meaningfully heading into the report, rising from 0.13 to 0.47. Shares at $39.67 were up 14.9% since the post-Q2 open and 16.6% above the 200-day moving average. They sat about 3% below the inter-earnings high of $41.00 and well above the September low of $32.22. In other words, the stock entered the report near the top of its range with expectations rising. The internal trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Astrana's organic engine, measured by EBITDA growth outpacing revenue and a rising full-risk mix, looks healthy. However, a GAAP earnings miss, a flat guidance midpoint, a Q3 flattered by one-time items, and newly adverse Medicaid trends give the quarter a balanced rather than accelerating feel. That is a harder sell for a stock that rallied into the report on improving sentiment.
Read our earnings preview for Astrana Health, Inc.: https://www.earningswhispers.com/article/ASTH/22241
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-09 | |
| Aug-07 | |
| Aug-06 | |
| Jul-14 | |
| Jul-13 | |
| Jul-13 | |
| Jun-04 | |
| May-12 | |
| May-11 | |
| May-07 | |
| Apr-21 | |
| Apr-10 |
