Yelp's 46.5% EPS Beat Rides On Buybacks And Cost Cuts As Ad Erosion Deepens And Revenue Guidance Slips
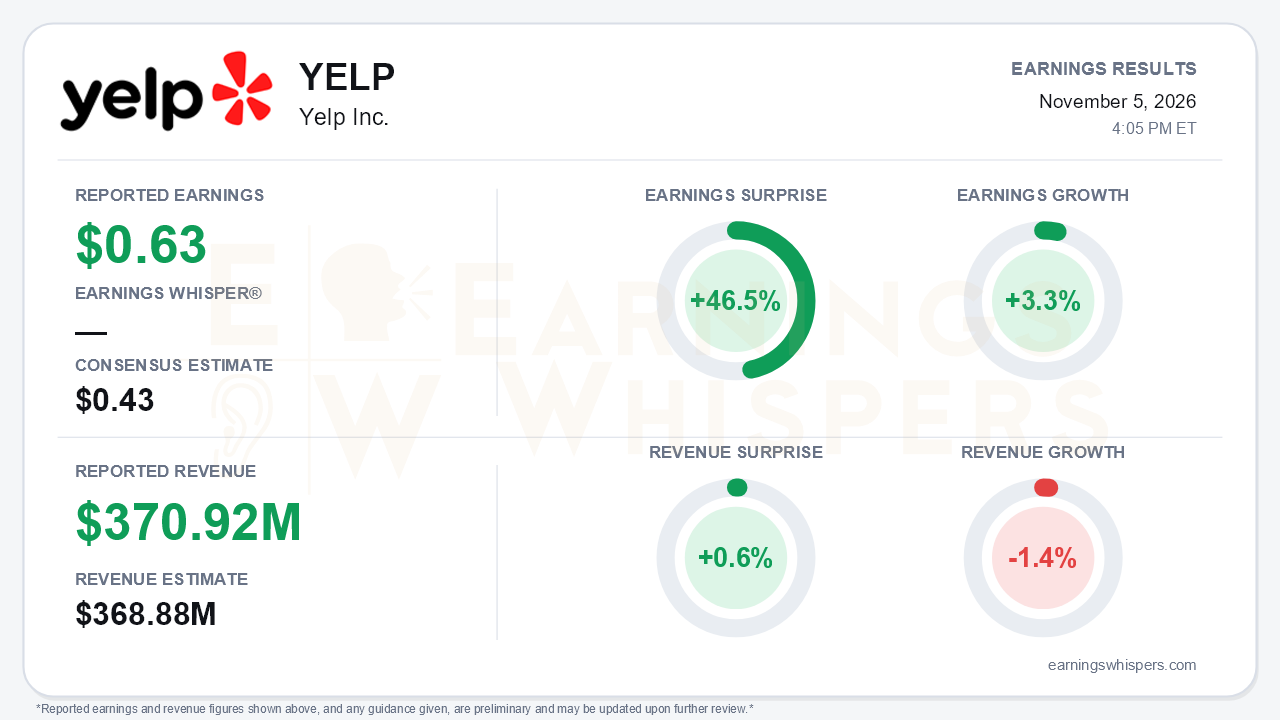
Yelp (NYSE: YELP) delivered a headline beat that looks far stronger than the business underneath it. Third-quarter earnings of $0.63 per share topped the $0.43 consensus by 46.5% and grew 3.3% year over year. Revenue of $370.92 million edged past the $368.88 million estimate by 0.6% but fell 1.4% from a year ago. The central tension is that the beat was built on expense discipline and a sharply smaller share count, while the core advertising franchise weakened again. Management also lowered full-year revenue guidance for the second consecutive quarter.
The quality of the beat deserves scrutiny. GAAP net income actually declined to $34.6 million from $39.3 million, and net margin slipped to 9% from 10%. Per-share growth came entirely from diluted shares falling roughly 15% to 54.8 million, the legacy of aggressive repurchases. Operating costs were held flat largely through cuts elsewhere:
- Product development spending dropped to $64.7 million from $78.1 million.
- Stock-based compensation fell to $23.1 million from $32.9 million.
- Depreciation, amortization and cost of revenue climbed with the Hatch acquisition.
Adjusted EBITDA of $92 million declined 6% year over year but cleared the high end of guidance by $17 million, with the 25% margin up from 24% in Q2 and 22% in Q1. Cash generation was less flattering. Quarterly free cash flow fell to $84.5 million from $118.9 million. The $263.6 million Hatch purchase has left Yelp with $120 million of cash and a $75 million revolver balance, and buybacks are paused until the revolver is repaid. That removes the share-count tailwind that has propped up EPS.
The call made clear that advertising erosion is broadening rather than stabilizing:
- Services ad revenue, long the steadier segment, turned negative at -2%, after flat results in Q2 and +1% in Q1.
- Restaurants, retail and other ad revenue worsened to -13% from -10%, even as paying locations rose 3%, implying lower spend per multi-location advertiser.
- Ad clicks fell 8%, versus a 5% decline last quarter, which management attributed to softer consumer demand.
The tone shifted noticeably. Q2's 'early signs of improvement' gave way to expectations of 'increased pressure on advertising revenue' in Q4 and a view that the local ad market won't turn 'anytime soon.' Management also conceded that Google AI Overviews are now having 'some impact' on traffic, a retreat from Q2's claim that Yelp had bucked that trend. Even the revenue beat narrowed to $1 million above the high end of guidance, versus $8 million in Q2.
The forward guide reinforces the deceleration. Full-year revenue guidance is now $1.455 billion to $1.46 billion, down from $1.46 billion to $1.47 billion. The implied Q4 range of $347 million to $352 million compares with $360 million a year ago. Full-year adjusted EBITDA was narrowed to the high end at $320 million to $325 million, but the implied Q4 figure of $57 million to $62 million sits well below last year's $86 million as investment in Hatch and Yelp Host ramps. A roughly $30 million Q4 tax benefit will flatter GAAP net income without helping EBITDA, so investors should be wary of reading too much into next quarter's bottom line.
The AI story does provide a credible offset:
- Other revenue hit a record $34 million, up 82%, putting the run rate at $136 million, more than halfway to the $250 million end-2028 target.
- Request a Quote is now integrated into ChatGPT listings and contributed to roughly 10% project growth.
- A Meta AI data deal places Yelp content across Meta properties.
- Yelp Host's annual call run rate reached 2.5 million, and its new voice capability lifted food-order conversion 13% at a large client.
Bears have legitimate ammunition here as well. Hatch ARR growth has slowed from 92% to 59% to 55%, and Yelp Assistant's share of quote projects is cited at about 10%, versus roughly 15% in Q1. At roughly $136 million annualized, these businesses remain too small to offset a decline in a far larger ad base.
The market setup is more complicated than the surprise implies. Shares entered the report at $22.05, down 18.7% from the open following the August report. The stock sat 6.5% below its 200-day moving average and 24.6% below the $29.23 inter-earnings high. It did rebound 27.7% off a 52-week low of $17.27 set in late September, so some recovery was already underway. Investor sentiment improved meaningfully, from -0.36 to -0.04, but remains slightly negative, suggesting expectations had moved toward neutral rather than optimism. Price and AVWAP trend readings remain negative.
The bottom line is that Yelp's EPS beat is a product of financial engineering and cost control, not demand. Core advertising deteriorated across both segments, guidance moved lower, and the buyback support behind per-share growth is now on hold. The AI and data-licensing businesses are growing quickly and give the long-term story substance, but the next several quarters hinge on whether they can scale before ad erosion and rising investment compress earnings further.
Read our earnings preview for Yelp Inc.: https://www.earningswhispers.com/article/YELP/22419
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Sep-16 | |
| Sep-10 | |
| Sep-08 | |
| Sep-02 | |
| Aug-25 | |
| Aug-25 | |
| Aug-07 |
