Texas Roadhouse Misses As A Late-Quarter Traffic Break Overshadows Margin Recovery
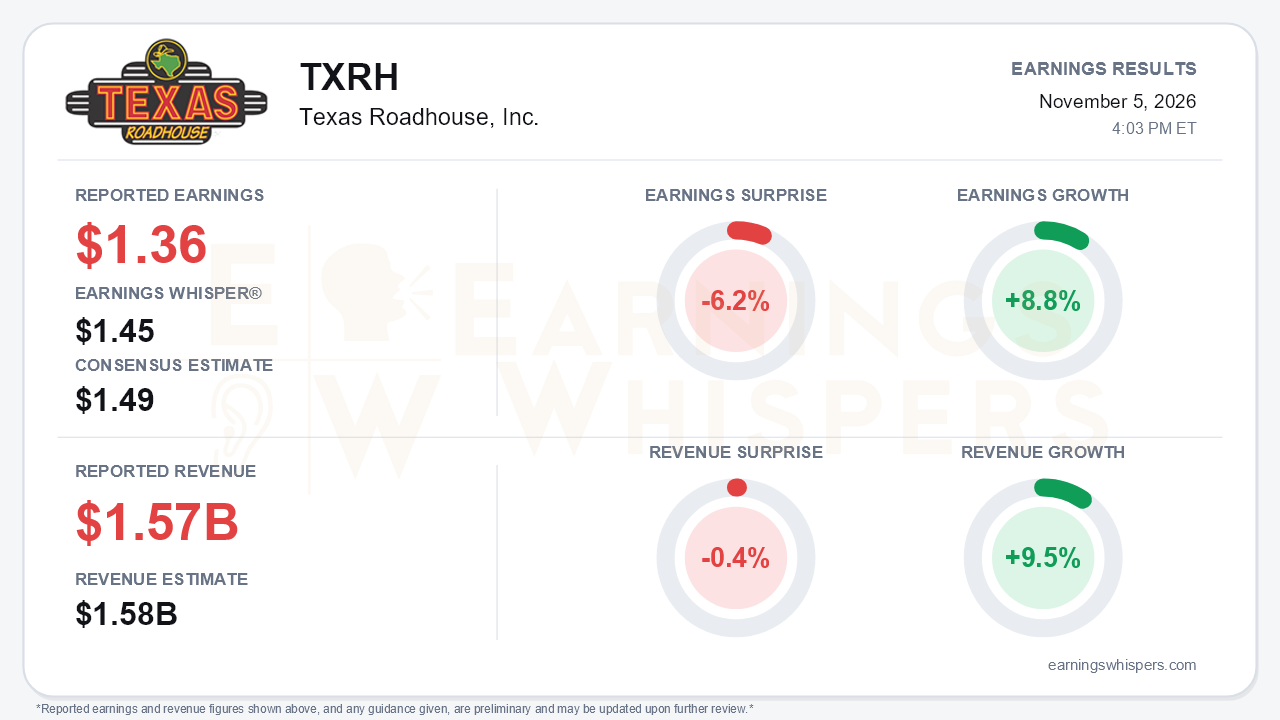
Texas Roadhouse reported third-quarter earnings of $1.36 per share, well short of the $1.49 consensus and the $1.45 Earnings Whisper number, a 6.2% miss. Revenue of $1.573 billion was 0.4% below the $1.58 billion consensus. On paper, growth held up: earnings grew 8.8% year over year, and revenue rose 9.5%. The company's own table shows 8.6% earnings growth based on unrounded figures. The earnings growth was a clear improvement over the slight decline in the second quarter. But the quarter's real story is not the year-over-year comparison. It is a traffic trend that broke in September and has not convincingly recovered. That is the central tension. The cost side of the model is finally turning favorable just as the demand engine that justified a premium casual-dining story has stalled.
The quality of the quarter deserves scrutiny in both directions. Restaurant margin rose 30 basis points to 14.6%. That compares with a 66-basis-point decline in the second quarter and a roughly 309-basis-point drop in the fourth quarter of 2025. Food and beverage costs improved 32 basis points as commodity inflation eased to 2.0% from about 7% in the prior quarter, and restaurant margin dollars climbed 11.9% to $228.6 million. Below the restaurant level, however, the leverage faded. Income from operations grew only 6.2%, trailing revenue growth, for several reasons:
- Depreciation and amortization rose nearly 15%.
- General and administrative expense increased 9%.
- Pre-opening costs rose.
- Impairment and closure charges jumped to $3.6 million from $0.1 million.
A lower tax rate and a smaller share count did some of the work in getting EPS to $1.36. Those supports do not repeat on their own.
The call made clear how abruptly demand shifted. Monthly comparable sales ran +5.9% in July and +6.8% in August, then collapsed to +1.0% in September. Management attributed the drop to a late-August social media hoax. Quarterly comps of +4.3% included just 0.7% traffic growth, down from 3.0% traffic and +6.2% comps in the second quarter. Average weekly sales slipped to about $164,000 from roughly $177,000 in the second quarter. Revenue growth decelerated to 9.5% from 11.1%. The one encouraging demand detail was mix, which reached flat after running negative 40 to 50 basis points in the first half. Notably, CEO Jerry Morgan's own statement in the release said only that traffic "softened late in the quarter." Management's tone shifted from the celebratory posture of the record second quarter to a defensive one. It pointed to week-by-week sequential improvement without quantifying the recovery.
The fourth-quarter read is the bears' strongest ammunition. Comparable sales for the first five weeks rose just 1.5%, versus +6.2% at the same point in the third quarter and +8.2% early in the first quarter. That figure includes a roughly 30-basis-point Halloween drag, and management flagged a roughly 75-basis-point holiday-shift headwind for the quarter. A 1.0% menu price increase offers modest support. Analysts also pressed on whether easing retail beef inflation could erode the steak-value traffic advantage the chain has enjoyed.
Against that, the forward cost picture improved in several ways:
- Fourth-quarter commodity inflation was lowered to about 4.5%.
- Initial 2027 guidance calls for roughly 3% labor inflation, the lowest in years, and about 4% commodity inflation. First-quarter 2027 commodities are expected near 5%, with pressure from oils, produce and freight.
- Store week growth is guided to 5% to 6%.
Development also remains intact. More than 30 company restaurants are under construction, about 35 openings are planned for 2027, and new franchise agreements were signed in Vietnam and Japan. Chicken Alfredo Pasta is expected to go system-wide by spring, and mobile POS is expanding to more than 200 additional stores. Capital intensity is rising, though. The 2026 capex guide moved up to about $440 million from $400 million, partly on timing and land adjacent to headquarters. Cash fell to $141 million from $202 million last quarter, and the company now carries $50 million drawn on its revolver.
The market had already lived through this story before the print. Shares set a 52-week high of $216.30 on August 13, shortly after the prior report. They then slid to $154.57 by October 1 as the September slowdown became apparent. They rebounded about 27% off that low to $196.45 heading into earnings. That leaves the stock roughly 9.9% above its 200-day moving average but still down 4.0% since the open after the August report. Investor sentiment was roughly unchanged, edging up to 0.48 from 0.46 and remaining moderately positive. Momentum and AVWAP trend readings are positive even as the price trend is negative. The sharp October recovery suggests investors were leaning toward a quick traffic rebound, which the 1.5% quarter-to-date comp does not yet show.
The bottom line is that Texas Roadhouse delivered a genuine margin inflection and a credible 2027 cost and unit-growth outlook. It paired them with an earnings miss and the weakest demand trajectory in years. Whether September was a hoax-driven anomaly or the start of a broader consumer slowdown is now the key question. After a 27% rebound from the October low, the stock is priced closer to the first answer than the current comps can support.
Read our earnings preview for Texas Roadhouse, Inc.: https://www.earningswhispers.com/article/TXRH/22406
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-28 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-06 |
