Atlassian Clears The Bar On Margins And Cash, But Decelerating Revenue And A Cautious Cloud Guide Set Up A Tougher Second Half
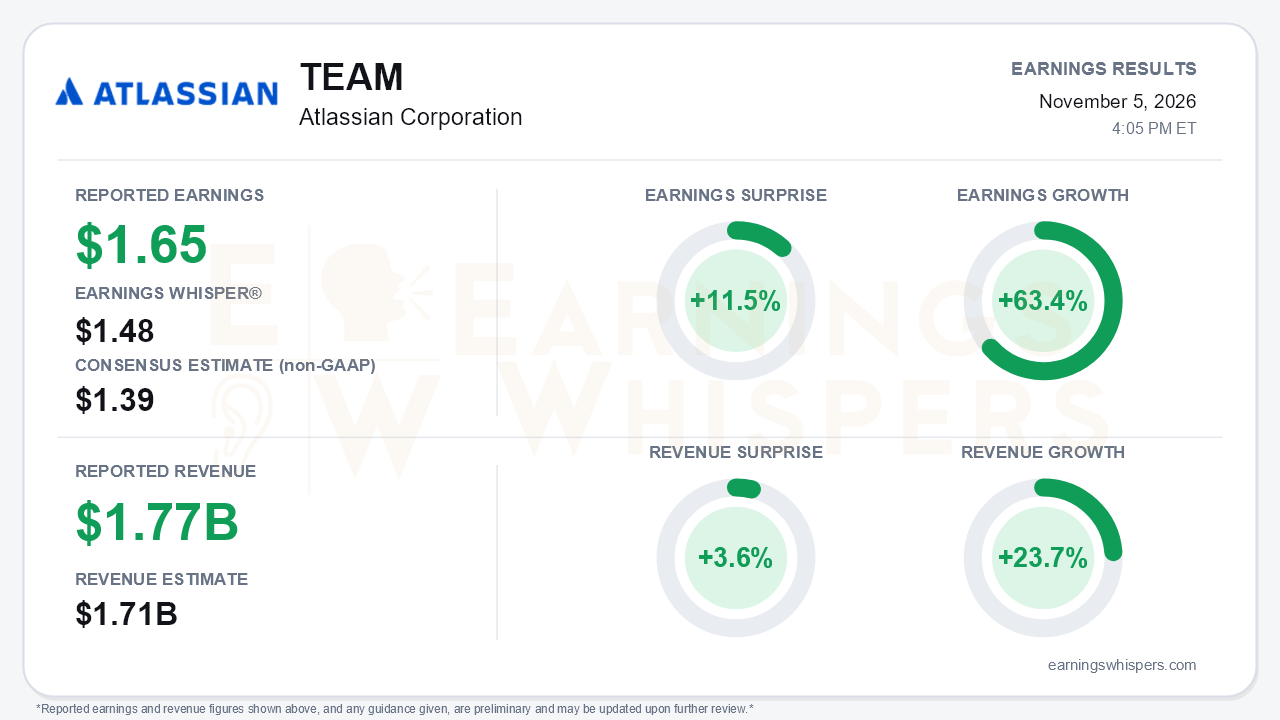
Atlassian delivered a clean beat for its fiscal first quarter. Non-GAAP earnings of $1.65 per share topped the $1.39 consensus by 11.5% and cleared the $1.48 Earnings Whisper number. Earnings grew 63.4% year over year. Revenue of $1.772 billion beat the $1.71 billion consensus by 3.6% and grew 23.7%. Profitability drove the upside more than the top line did. Total revenue growth has now slowed from 32% two quarters ago to 28% last quarter and 24% this quarter. The forward guide also signals further cloud deceleration. That is the central tension: margins are expanding while revenue growth is visibly decelerating.
The quality of the earnings beat is high, with some caveats. Non-GAAP operating margin jumped to 32% from 23% a year ago. On a GAAP basis, Atlassian swung from a $96 million operating loss to $189 million of operating income, an 11% margin. That was well above the 6.5% management had guided for Q1, though slightly below Q4's 12%. Several factors helped the comparison:
- Last year's quarter carried $56 million of restructuring charges.
- Operating expenses rose only 4% while revenue grew 24%.
- Gross margin improved roughly three points to about 85%, despite rising AI usage.
- Free cash flow quadrupled to $463 million, a 26% margin.
Part of the per-share growth came from the share count rather than operations. Atlassian spent $588 million on buybacks, and diluted non-GAAP shares fell to 256.9 million from 264.3 million. The repurchases outpaced free cash flow, and cash declined to $1.12 billion. GAAP net income of $91 million remains far smaller than the non-GAAP figure, mostly because of $356 million in stock-based compensation.
Beneath the headline, the core cloud engine held steady. Cloud revenue grew 31% to $1.3 billion, matching Q4 and up from 29% and 26% in the two quarters before that. Other indicators were also solid:
- Subscription ARR grew 23% to $6.8 billion.
- RPO grew 44% to $4.7 billion, with current RPO up 28%. In absolute terms, RPO dipped slightly from Q4's $4.8 billion.
- Customers paying $5 million or more grew about 70%, and net revenue retention stayed above 120%.
- Teamwork Collection reached more than 3,000 customers, up 7x year over year.
- Service Collection passed 70,000 customers, with roughly $1 billion of ARR growing above 30%.
The weak spot was the size of the cloud beat. It shrank to about $20 million from roughly $50 million in each of the prior two quarters. Management partly attributed that to new hybrid deals, which let large Data Center customers sign multi-year migration commitments. Those deals shift some revenue into Data Center, which itself beat by $33 million on better-than-expected retention.
The guide is where bears have legitimate ammunition. For Q2, Atlassian projected:
- Revenue of $1.825 billion to $1.835 billion.
- Cloud growth of about 27%, implying roughly four points of deceleration, more than the prior guide had suggested.
- GAAP operating margin of 4.5% and non-GAAP operating margin of 26%, both well below Q1's levels.
For the full year, the company targets total revenue growth of about 13.75%, cloud growth of 26%, a 16% decline in Data Center revenue, and Subscription ARR growth of roughly 18.5%. Hitting that ARR target means a meaningful slowdown from today's 23% pace. Management cited the DX acquisition anniversary, tougher second-half comparisons and macro prudence.
There is an apparent conflict in the outlook. The revenue outlook sits above estimates, but the full-year raise was smaller than the Q1 beat. Management attributed the gap to ASC 606 timing and Data Center pull-forwards that it did not flow through to the full year. Analysts also pressed on two longer-term questions:
- Whether the Data Center tail survives the March 2029 end-of-life, given that FedRAMP High is not expected until January 2029.
- Whether AI agents could reduce demand for Jira and Confluence coordination.
Management's answer to the AI concern is to make Atlassian the context layer for agents. It launched the Agentic Multiplayer Protocol and rebuilt its MCP server, which now handles 15 million daily tool calls. It also expanded its OpenAI partnership, and Rovo is used by 87% of enterprise cloud customers. These are credible adoption signals, but they are not yet revenue drivers. AMP is not separately monetized. Usage-based pricing enforcement begins in December, but management explicitly excluded it from near-term revenue expectations.
The market setup is more complicated than the surprise suggests. Shares closed at $189.88 ahead of the report, up 30.8% since the open after the August release and about 59% above the 200-day moving average. However, the stock was already 17.4% below the $229.96 52-week high set on October 22, so it had given back a sizable portion of its run before reporting. Investor sentiment moved from slightly negative (-0.06) to slightly positive (+0.07), a modest improvement rather than euphoria. The Earnings Whispers trend signals are uniformly positive, consistent with the recent recovery in price and sequential growth.
The bottom line is that Atlassian produced a high-quality profit and cash beat, steady 31% cloud growth and strong enterprise and AI adoption metrics. However, total revenue growth is decelerating, the cloud beat is shrinking and guidance points to slower cloud and ARR growth with lower margins ahead. The call preserved a credible platform story. With the stock still well above its long-term trend, the debate now centers less on execution and more on how much growth survives the second half.
Read our earnings preview for Atlassian Corporation: https://www.earningswhispers.com/article/TEAM/22401
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 6 hours | |
| 7 hours | |
| 8 hours | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-26 | |
| Oct-23 |
Atlassian Swing Trade: Why We Sold A Resilient Stock In A Tech Pullback
TEAM
Investor's Business Daily
|
| Oct-18 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-12 | |
| Oct-07 |
