WillScot's Volume Inflection Arrives, But Flat EBITDA Guidance And Heavy Capex Leave Investors Waiting For Margins
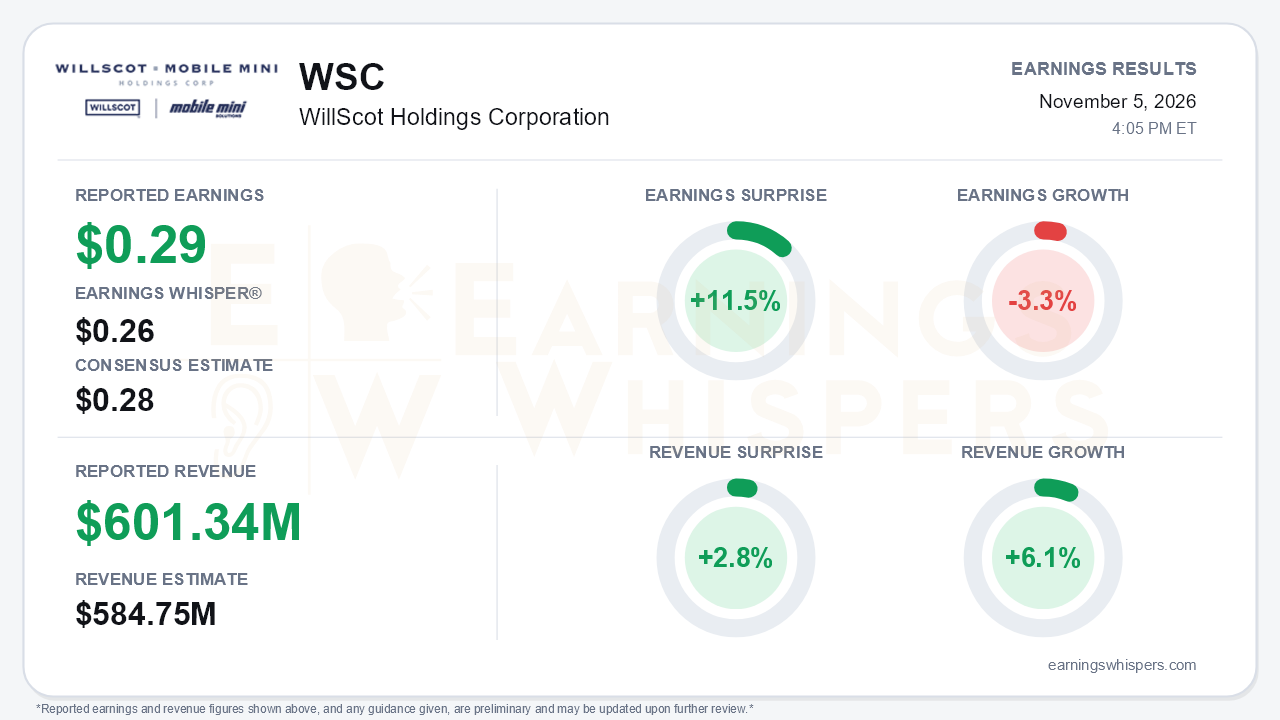
WillScot Holdings (NASDAQ: WSC) delivered the quarter bulls had been waiting for. Adjusted earnings of $0.29 per share topped the $0.28 consensus and cleared the $0.26 Earnings Whisper number for an 11.5% surprise. Revenue of $601.34 million beat the $584.75 million consensus by 2.8% and grew 6.1% year over year. More important than the beat, modular units-on-rent turned positive, up 1.2% year over year, earlier than management had expected. That was the first year-over-year volume growth in years. Management also raised full-year revenue guidance for the third straight time, to $2.34 billion. The central tension is that the inflection is showing up in revenue, not yet in profit. Adjusted EPS still fell 3.3% from a year ago, and full-year Adjusted EBITDA guidance was held at $920 million despite the higher top line.
The quality of the quarter deserves scrutiny on two fronts. First, margins. Adjusted EBITDA of $234 million was down from $243 million a year earlier, and the 38.8% margin compares with 42.9% in last year's third quarter. That margin did improve 160 basis points from the second quarter. Delivery and installation revenue jumped 23%, but the related costs rose about 25%, so that growth adds activity far faster than it adds profit. Second, the composition of leasing growth. Leasing revenue rose $17.5 million, or 4%, but $13.3 million of that came from other leasing-related revenue. That line climbed to $16.8 million from $3.5 million as write-offs of uncollectible receivables fell to $7.0 million from $24.5 million. Core modular leasing grew a more modest 2.2%, and portable storage leasing fell 7%. GAAP EPS rose to $0.28 from $0.24. That gain was helped by lower interest and depreciation, and it flatters the comparison relative to the adjusted figure.
The call preserved a credible growth story, and the forward indicators are genuinely improving:
- **Leasing growth:** accelerated from -2% in the first quarter to roughly 1.5–2% in the second and 4% in the third, with about 4% expected in the fourth.
- **Order book:** the modular pending order book grew more than 20%, up from 13% last quarter.
- **Pricing:** rates on new complex orders rose by double digits.
- **Large wins:** a 750-unit pharmaceutical campus and a 250-plus-unit semiconductor expansion.
- **2027 outlook:** a preliminary view of low-single-digit organic revenue growth and mid-single-digit Adjusted EBITDA growth. On the prior year-end call, management had explicitly declined to assume that kind of growth.
Not every metric moved the right way. Modular activation growth slowed to 12% from 16%. Enterprise account revenue growth eased to 15% from 21%. Fourth-quarter sequential margin expansion is now guided at 300–400 basis points, down from the 300–500 basis points suggested last quarter.
Bears have legitimate ammunition on capital intensity. Net CAPEX guidance has climbed from $275 million to $400 million over four updates. Third-quarter Net CAPEX of $123 million nearly doubled from a year ago, pushing Adjusted Free Cash Flow down to $78 million from $124 million. The free cash flow margin fell to 13.0% from 21.8%. Management says incremental fleet is more than 90% on rent or assigned with minimum durations above two years, which supports the investment case. Still, leverage sits at 3.7x net debt to Adjusted EBITDA, and the target of approaching 3.0x is not until exiting 2027. Data centers make up about 18% of the pending modular order book, and management flagged recent political changes as a risk to the pace of those build-outs. The non-recurring World Cup revenue also creates tougher comparisons in mid-2027.
The market setup is more complicated than the surprise implies. Shares opened at $26.29 after the August report, near the inter-earnings high of $26.72, then slid to a low of $15.57 on October 19. The stock entered this report at $19.30, down 26.6% since the prior report. That price is about 24% above the October low but still 11.6% below the 200-day moving average of $21.83. Investor sentiment was already negative and weakened modestly into the print, slipping from -0.13 to -0.18. Earnings Whispers trend readings are mixed: momentum is positive while price and AVWAP trends remain negative. That pattern fits a stock that has bounced but has not repaired its broader decline.
The bottom line is that WillScot has moved from hoping for a volume inflection to reporting one, backed by a stronger order book, firmer pricing, and a first look at 2027 growth. What investors have not yet received is evidence that this volume converts into margin and free cash flow. EBITDA guidance is unchanged, margins remain roughly 400 basis points below last year, and capex keeps climbing. Until fourth-quarter flow-through and 2027 margins validate the top-line story, the improvement is real but still largely on the revenue line.
Read our earnings preview for WillScot Holdings Corporation: https://www.earningswhispers.com/article/WSC/22415
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-07 | |
| Sep-15 | |
| Sep-11 | |
| Aug-20 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-28 | |
| Jul-23 | |
| Jul-13 |
