PDF Solutions Posts Record Revenue And Margin Breakout, But A Backlog Dip And Slower Implied Q4 Growth Temper A Narrow Miss
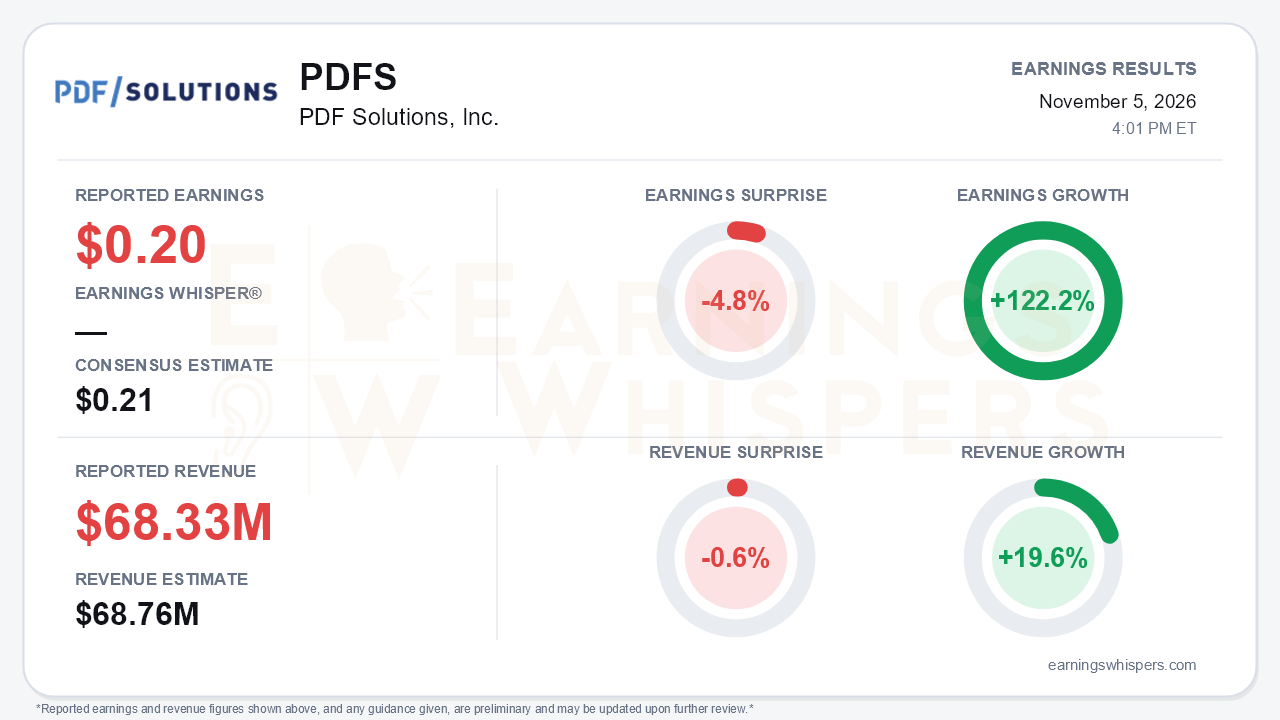
PDF Solutions delivered the strongest operating quarter in its history while still missing the bar. Earnings Whispers calculates third-quarter earnings of $0.20 per share, a penny below the $0.21 consensus, a 4.8% shortfall. Revenue of $68.33 million was a record but fell 0.6% short of the $68.76 million estimate. Year-over-year growth was strong, with earnings up 122.2% and revenue up 19.6%. The company reported GAAP diluted EPS of $0.16 and non-GAAP EPS of $0.40, both well above year-ago levels of $0.03 and $0.25, so investors should note that the Earnings Whispers figure does not match either company-reported number. The central tension is clear: profitability broke out, but backlog shrank and the full-year target implies slower growth in the fourth quarter.
The margin story was the best part of the quarter. Non-GAAP gross margin recovered to 77% from 73% in the second quarter. Non-GAAP operating margin jumped to 28% from 22%, ahead of the 27% long-term target management set in December 2025, only three quarters into the plan. GAAP operating margin rose to 12% from 8%. Platform revenue drove the gain, climbing to $58.3 million, up 19% sequentially and 22% year over year. Volume-based revenue slipped to $10.0 million from $12.4 million in the second quarter, though it was still up from $9.1 million a year ago. The quality of the earnings deserves some scrutiny. Stock-based compensation rose to $8.5 million from $6.0 million sequentially, and the diluted share count grew to roughly 43 million from 39.6 million a year earlier, reflecting the May equity raise. That raise also pushed cash to about $107 million.
Revenue growth is decelerating on a year-over-year basis even as sequential momentum improves. Revenue rose 11% from the second quarter, but the 20% annual growth rate trails the 26% posted in the first quarter. Management reaffirmed its 20% annual revenue growth target for 2026. However, the call analysis shows this implies fourth-quarter revenue of roughly $73 million, or about 17% growth, down from roughly 22% in the first half. Earnings Whispers characterizes the outlook as lowered guidance. Strictly speaking, management reaffirmed its annual target, so the more accurate reading is that the implied exit rate is softer than the first-half pace.
Backlog is the clearest blemish. Ending backlog fell to $247.2 million from $270.7 million in the second quarter and $292.0 million a year ago. Management attributed the decline to the timing of large deals. It expects a handful of eight- and nine-figure renewals in the fourth quarter and first quarter to lift backlog back above $271 million by year-end and eventually past the 2025 peak. That outlook implies roughly $100 million of net bookings in the fourth quarter, and management conceded some of those deals will likely slip into 2027. Bears have legitimate ammunition here, particularly given how lumpy these contracts are and how volatile the geographic mix has been, including a recent surge in Japan.
The product pipeline gives bulls more to work with:
- **E-Probe traction:** The company signed an eight-figure E-Probe and CV test-chip contract with an existing leading-edge customer. A second customer is now running multiple machines, a flash evaluation has started, and a DRAM pilot is installed on-site.
- **Customer validation:** Samsung presented its use of E-Probe on an advanced node at PDF Connect.
- **2027 capacity:** Management plans to build more E-Probes in 2027 than in 2026, with a possible first placement in China.
- **Exensio Aurora:** The new AI-native analytics architecture was unveiled in September, though management admitted it is too early to judge monetization.
- **SecureWise:** Management expects a very good 2027.
The offsets are capex of $15.1 million in the quarter, rising memory and component costs for E-Probe compute, and build capacity limited by supply and execution. Management's tone on 2027 was notably confident, saying nothing has it thinking less than typical targets.
The market has not been rewarding the story. Heading into the report, shares sat at $39.79, down 15.3% since the open after the August report and 10.9% below the 200-day moving average. The stock traded just 3% above its October 23 inter-earnings low of $38.63 and 30.2% below its October 6 high of $56.98, meaning a sharp rally had fully unwound. Investor sentiment improved from -0.37 to -0.21 but remains negative. The Earnings Whispers price and AVWAP trend readings are negative, while the sequential growth trend is positive, consistent with fundamentals that are improving faster than the share price.
The bottom line is that PDF Solutions proved it can hit its long-term margin model ahead of schedule and is building real momentum in E-Probe. However, the narrow miss, the sequential backlog decline, and an implied fourth-quarter slowdown give skeptics reason to wait. With shares near the bottom of their recent range, the next test is whether the promised large renewals close on time and push backlog back toward its prior peak.
Read our earnings preview for PDF Solutions, Inc.: https://www.earningswhispers.com/article/PDFS/22360
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-19 | |
| Sep-09 | |
| Aug-28 | |
| Aug-11 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-16 | |
| Jul-15 | |
| Jun-02 | |
| May-15 |
