Opendoor's Acquisition Boom Collides With A Margin Collapse As Q3 Loss Widens And Profitability Targets Slip
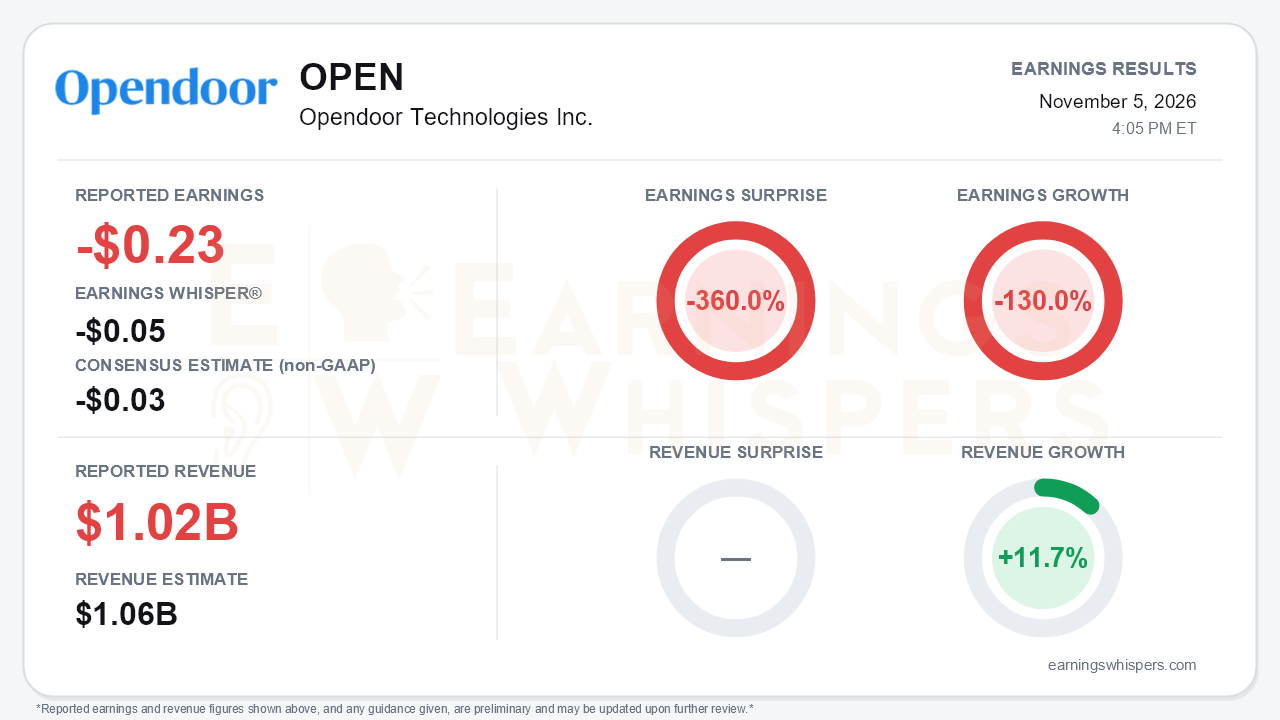
Opendoor Technologies posted a third-quarter loss of $0.23 per share, well short of the -$0.03 consensus and the -$0.05 Earnings Whisper number, a 360.0% negative surprise. Earnings fell 130.0% from a year earlier. Revenue rose 11.7% to $1.022 billion but missed the $1.06 billion consensus by 3.6%. One caveat matters: the reported figure is GAAP, while consensus was framed on a non-GAAP basis. The GAAP loss of $218 million includes $96 million of stock-based compensation tied to market-condition RSUs, and adjusted net loss was a narrower $66 million. Even on management's preferred measures, though, the quarter went backward. Opendoor is growing faster than it has in years and earning less on every home it sells. That is the central tension.
The volume story is real. Homes purchased jumped to 4,865 from 1,169 a year ago. Acquisition contracts topped 7,000, up from more than 5,000 in the first quarter. Estimated market share reached 0.56%, about 4.4 times the prior-year level. Efficiency also improved:
- Trailing-twelve-month marketing expense per acquired home fell 57% to $2,800.
- Operations expense per acquired home fell 36% to $4,000.
- Fixed operating expenses held at $37 million while purchases quadrupled.
The resale side broke down. GAAP gross margin collapsed to 3.7% from 9.7% in Q2 and 10.0% in Q1, hit by a $53 million current-period inventory valuation adjustment. Contribution margin fell to 3.3% from 5.8%, and contribution profit per home sold dropped to $12,000 from $22,000. Adjusted EBITDA swung to a $31 million loss from a nearly break-even -$4 million in Q2.
The call made the reversal explicit. Management blamed a housing market that deteriorated sharply in the quarter, citing record-low pending home sales and mortgage rates above 7%. Homes bought aggressively in the spring are now being sold into that weakness with deeper price cuts. The share of listed homes on the market for more than 120 days doubled to 18% from 9%. That reverses an improvement trend that had run from 51% a year ago to 10% in Q1. The company downgraded its unit-economics and resale-velocity objective from green to yellow. Management also conceded it is behind on its adjusted EBITDA and adjusted net income profitability targets for the end of 2026, after earlier calls repeatedly said it was on track. The tone shifted with it, from claims that Opendoor didn't need the market to explicit macro attribution, though management remained defiant about share gains.
Guidance offers little near-term relief. Opendoor expects fourth-quarter revenue to grow at least 40% year over year, yet that still landed below Street estimates. Management expects contribution profit dollars to decline again sequentially and guided to an adjusted EBITDA loss of $70 million to $85 million. It said the drag from spring-acquired inventory should persist into Q1 2027. Marketing spend is also rising to roughly $20 million from $5 million in Q3, so the cost-leverage narrative will be tested just as margins compress.
The forward catalysts are capital-light:
- Buy with Opendoor mortgages, which earn revenue on homes Opendoor never owns.
- List with Opendoor, which lifted first-offer conversion 28% in tests.
- Mortgage licenses in 25 states, with originations up more than 400% sequentially and October alone exceeding half of Q3 volume.
- Title and escrow services extended to non-Opendoor transactions.
These are credible diversification efforts, but they remain small relative to a $2.57 billion inventory book.
The balance sheet deserves attention. Inventory rose from $925 million at year-end to $2.57 billion. Current asset-backed debt climbed to $2.02 billion, and nine-month operating cash outflow reached $1.8 billion. Shareholders' equity fell to $592 million. The $650 million 0% convertible extended maturities and funded a roughly 5% buyback, but it also cuts against prior no-raise rhetoric. Cash stood at $910 million.
The market had largely priced in trouble before the report. Shares fell 49.1% from the $3.89 open after the August report to $1.98. They sit 52% below the 200-day moving average of $4.13 and just 14.5% above a 52-week low of $1.73 set two days before earnings. Price and AVWAP trend readings remain negative. Investor sentiment stayed negative but improved modestly, from -0.25 to -0.17, suggesting some investors were looking past the quarter toward the volume ramp.
The bottom line is that Opendoor proved it can buy homes at scale and run leaner, but it has not yet proved it can sell them profitably in a hostile market. Profitability targets slipped, margins are guided lower again, and aged inventory is building. Bears have legitimate ammunition, and the stock's deep drawdown reflects that. The bull case now depends on clearing the spring cohort and scaling mortgage and listing products before the inventory and leverage build becomes the dominant story.
Read our earnings preview for Opendoor Technologies Inc.: https://www.earningswhispers.com/article/OPEN/22354
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-19 | |
| Oct-19 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-12 | |
| Sep-28 | |
| Sep-28 |
