Kodiak AI Hits Estimates As Commercial Milestones Pile Up, But Flat Underlying Revenue And A Shrinking Cash Runway Define The Setup
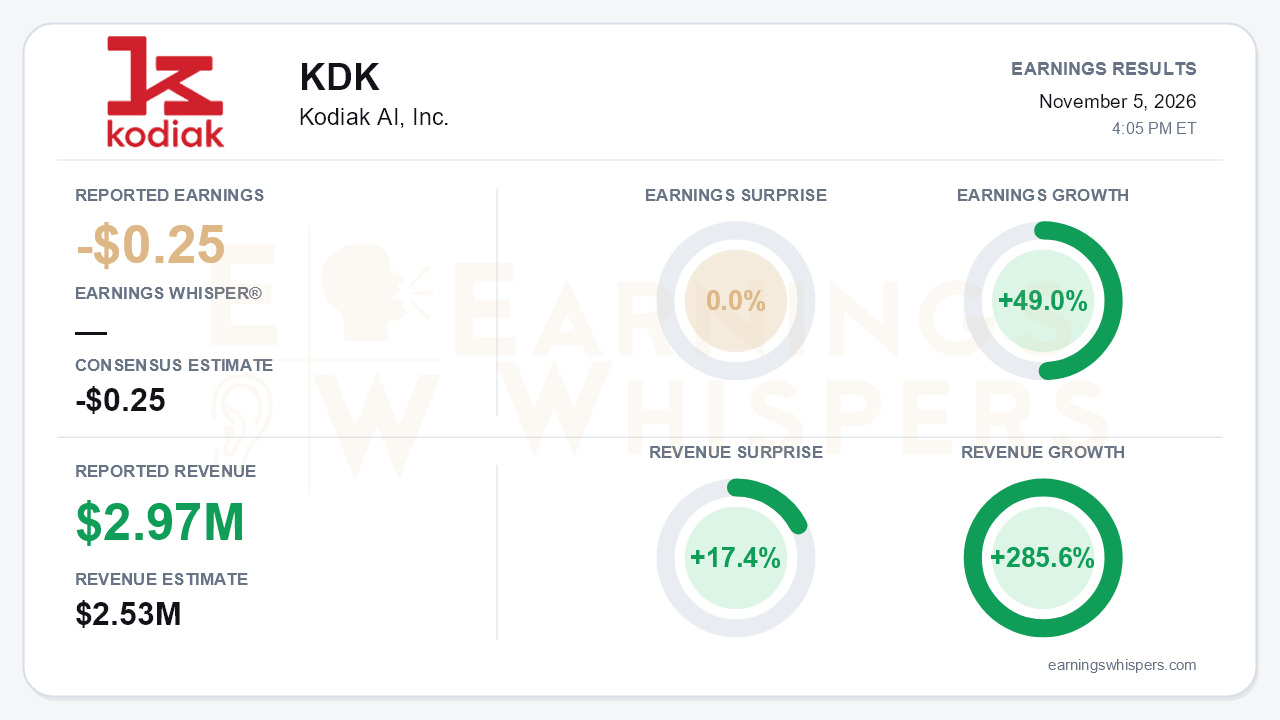
Kodiak AI delivered a third quarter that was in line on earnings and ahead on revenue, but the real story is the gap between a rapidly maturing commercial pipeline and a balance sheet that is running short of time. The company reported a loss of $0.25 per share, matching the consensus estimate, while revenue of $2.97 million topped the $2.53 million consensus by 17.4%. On Earnings Whispers' normalized basis, earnings improved 49.0% year over year, and revenue jumped 285.6% from a tiny prior-year base. On the call, Kodiak paired those numbers with its first binding long-haul contract, a third OEM platform and multi-year targets. Investors are left to weigh an increasingly credible operating story against a shrinking cash cushion.
The quality of the quarter deserves scrutiny. Reported GAAP results show net income of $27.4 million and diluted EPS of $0.09, but that profit came entirely from a $78.2 million non-cash gain on the fair value of common stock warrants, which reflects the collapse in the share price rather than operating progress. Strip that out and the operating picture deteriorated. The GAAP operating loss widened to $50.4 million from $43.7 million in Q2 and $37.9 million in Q1. Non-GAAP operating expenses nearly doubled year over year to $44.5 million. The revenue beat also looks thinner than it appears. The $3.0 million total included roughly $0.5 million of one-time Defense revenue, sequential revenue fell from $3.5 million, and underlying Driver-as-a-Service revenue was roughly flat quarter over quarter.
Where the business clearly moved forward was in operating readiness and commercial commitments. The Autonomy Readiness Measure climbed to 99% from 91% in Q2 and 84% in February, and management reaffirmed the year-end unsupervised long-haul launch, with IKEA Supply running five trucks on a 219-mile stretch of I-45. Other operating measures kept growing:
- Cumulative paid driverless hours reached 58,000, up from 40,000 in Q2.
- Quarterly freight volume topped 396,000 tons, versus more than 300,000 tons in Q2.
The DTL Transport agreement for 75 customer-owned trucks validates the Driver-as-a-Service model in long-haul, not just in the Permian. Adding International LT as a third OEM broadens the hardware path, with deployments targeted for the second half of 2027. Management also introduced its first long-range targets:
- About 200 unsupervised trucks and more than $50 million in annualized run-rate revenue exiting 2027.
- 5,000 cumulative trucks and free-cash-flow breakeven in 2029.
Bears have legitimate ammunition on near-term execution. Atlas added only two trucks in Q3, ending at 37 against a high-30s framing, after adding seven in Q2 and eight in Q1. The year-end mid-40s target implies roughly 10 second-half additions versus about 15 in the first half. The 100-truck commitment by the first half of 2027 was maintained. Analysts also pressed on upfit capacity and supply-chain quality for the steep 200-to-5,000 truck ramp. Management declined to comment on Daimler opening its platform to multiple autonomy providers.
Liquidity is the central tension. Cash and marketable securities fell to $113.6 million from about $151 million in Q2. Q3 free cash flow of negative $38.0 million beat guidance, and full-year free cash flow guidance improved for the third straight quarter to negative $153 million to $155 million. Even so, the Q4 burn guide of $42 million to $44 million is a step up as autonomy hardware capex ramps. Management said it will not raise equity at current prices, which it considers undervalued, and is exploring hardware and strategic financing instead. That stance protects shareholders from dilution near $1, but it makes the outcome of those alternatives critical.
The market has priced that risk aggressively. Shares fell 74.9% from the $4.39 open after the August report to $1.10 entering this release. That leaves them about 81% below the 200-day moving average and roughly 15% above the $0.96 52-week low set on October 23. Investor sentiment swung sharply from slightly negative to strongly positive heading into the report. The supplied reading sits outside the stated -1 to +1 scale, so its magnitude should be treated cautiously, but the direction clearly shifted toward optimism. Trend readings are mixed, with momentum positive while the AVWAP trend remains negative, consistent with a stock bouncing off its lows without repairing the broader downtrend.
The bottom line is that Kodiak used this quarter to make its commercial case far more concrete, with a binding long-haul contract, a reaffirmed launch, a third OEM and explicit 2027-2029 targets. However, flat underlying revenue, widening operating losses and a runway measured in quarters mean the story now hinges on financing as much as on autonomy. A clean year-end launch would strengthen the narrative, but the stock's recovery likely depends on management showing it can fund the ramp without the dilution it is trying to avoid.
Read our earnings preview for Kodiak AI, Inc.: https://www.earningswhispers.com/article/KDK/22320
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Nov-02 | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-21 | |
| Oct-20 | |
| Oct-15 |
