Entravision's Ad-Tech Engine Cools Sequentially As Univision Break Rewrites The TV Story
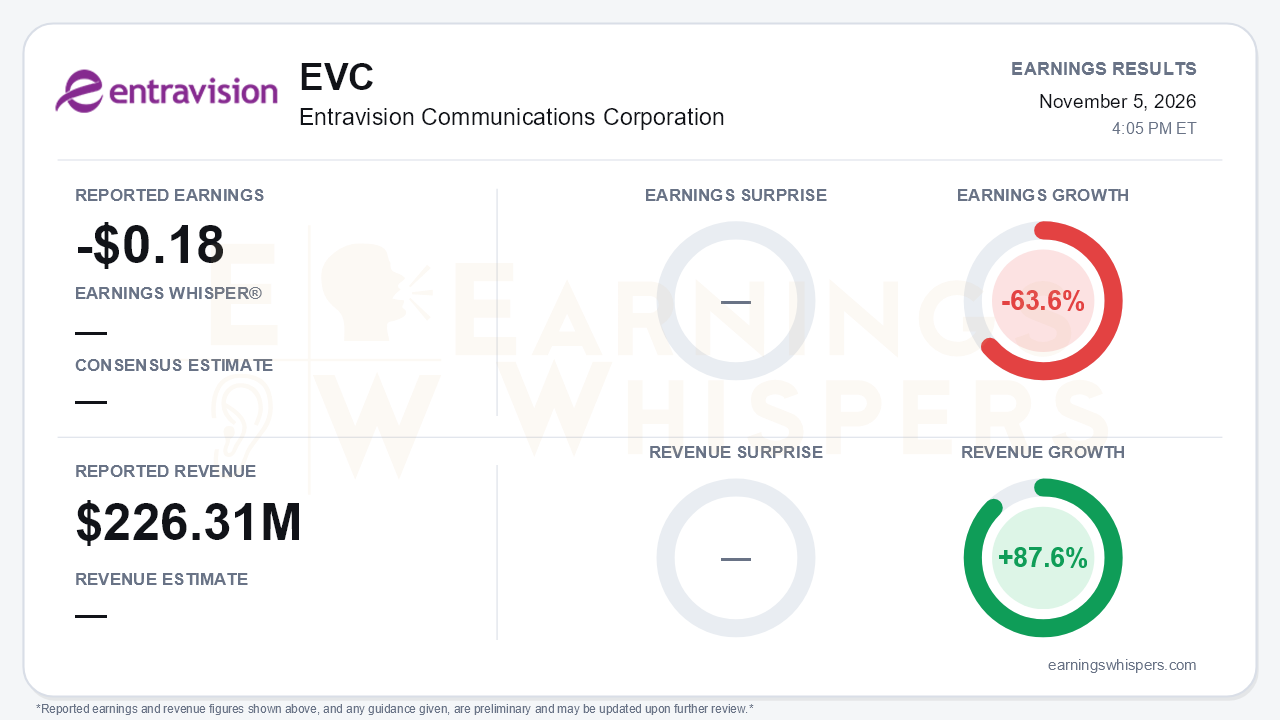
Entravision's third quarter has a reporting conflict that investors need to know about before anything else. The Earnings Whispers normalized data lists a loss of $0.18 per share on revenue of $226.31 million, with earnings down 63.6% year over year and revenue up 87.6%. The company's own release shows the opposite sign. It reports GAAP net income of $19.0 million, or $0.18 per diluted share ($0.21 basic), compared with a loss of $0.11 a year earlier. There was no consensus estimate or Whisper number for comparison. Whichever earnings figure investors anchor to, the operating story is the same. The advertising technology and services (ATS) segment is still producing enormous year-over-year gains. The more important developments, however, are a sequential cooling in that engine and a strategic rupture in the legacy TV business.
The year-over-year numbers are striking. ATS net revenue jumped 133% to $177.2 million, and ATS segment operating profit rose 261% to $35.2 million. The company attributed the gains to more monthly active advertisers and higher revenue per advertiser, driven by AI investments in the platform and added sales capacity. Consolidated operating income was $28.3 million, compared with an operating loss of $9.1 million a year ago.
The quality of the improvement holds up better than many turnarounds:
- **Cleaner comparison base:** The prior-year quarter carried a $5.7 million impairment and $3.2 million of restructuring costs.
- **Cash flow:** Operating cash flow roughly doubled to $16.1 million in the quarter and reached $61.7 million year to date.
- **Balance sheet:** Cash and marketable securities climbed to about $90 million, up from $63 million at year-end.
The softer details are mostly beneath the surface. Receivables have swelled to $152 million from $95 million. Stock-based compensation rose to $4.8 million. Diluted share count is now 104.5 million, versus 92.3 million basic shares.
The headline masks clear deceleration. ATS growth of 133% compares with 182% for the nine-month period, and consolidated growth of 88% trails the 108% year-to-date pace. Sequentially, the trend weakened:
- **Revenue:** ATS revenue slipped 3% from $182.8 million in the second quarter.
- **Profit:** ATS operating profit fell 12% from $40.0 million.
- **Margin:** ATS margin compressed to roughly 20% from about 22%.
Management had guided to a sequential cooldown, so the revenue dip was not a surprise. The margin squeeze came from fully onboarded hires and temporary cost overlap from a multi-cloud migration at Smartics. Management argues that migration will lower future cloud spend. Management also reaffirmed that fourth-quarter ATS revenue should grow more than 100% year over year. Still, customer concentration and spending swings among large clients remain a recurring theme. That leaves bears with legitimate ammunition if a key account pulls back.
The media segment is where the narrative changed most. On the surface, the quarter looked better:
- Media revenue rose 10% to $49.1 million, helped by about $6 million of political advertising.
- The segment posted a $0.1 million operating profit, versus losses of $3.3 million in the second quarter and $5.2 million in the first.
Underneath, the outlook weakened considerably. Full-year 2026 political revenue is landing around $25 million. That is the low end of internal expectations and below both 2022 ($32 million) and 2024 ($34 million), despite earlier talk of being "very well positioned." More consequentially, management abandoned its repeated "plan to renew" stance on the Univision affiliation. The affiliation now carries only a short extension through March 31, 2027, while the company explores strategic alternatives for the TV business without it. Entravision describes itself as Univision's largest affiliate group, so this is not a footnote. It raises real questions about the value of its stations and the durability of retransmission revenue.
Management is responding on several fronts:
- **Asset sale:** An agreement to sell the Tampa TV stations for $30 million.
- **Media reset:** A planned expense and organizational overhaul aimed at media profitability in 2027.
- **Capital allocation:** A review in early 2027, with results promised on the fourth-quarter call.
With debt down to roughly $153 million and cash building, the company has flexibility. The direction of that review, however, is now an open question rather than a footnote.
The market context is thin this cycle, with no current price or sentiment reading supplied. Shares opened at $10.11 after the August report, well above the 200-day moving average of $6.84. That suggests the stock had already been rewarded for the ATS transformation heading into this quarter. With that much good news priced in, a sequential stall in ATS combined with an affiliation shock creates a more complicated setup than the year-over-year growth rates imply.
The bottom line is that Entravision remains a high-growth ad-tech story attached to a media business whose identity is now in flux. ATS still delivers triple-digit growth and the balance sheet is strengthening, but the quarter showed the first sequential revenue and margin slippage. Management's tone on political revenue and Univision also turned decidedly more cautious. Investors should reconcile the conflicting EPS data against the GAAP release. Beyond that, they should focus on whether fourth-quarter ATS delivers the promised 100%-plus growth with margins recovering, and on what the TV strategic review ultimately produces.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-22 | |
| Oct-21 | |
| Sep-28 | |
| Sep-16 | |
| Aug-26 | |
| Aug-17 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Aug-05 | |
| Jul-28 | |
| Jun-04 |
