Affirm Beats On 34% GMV Growth And A 4.3% Take Rate, But Credit Upticks And A Light GAAP Margin Guide Muddy The Story
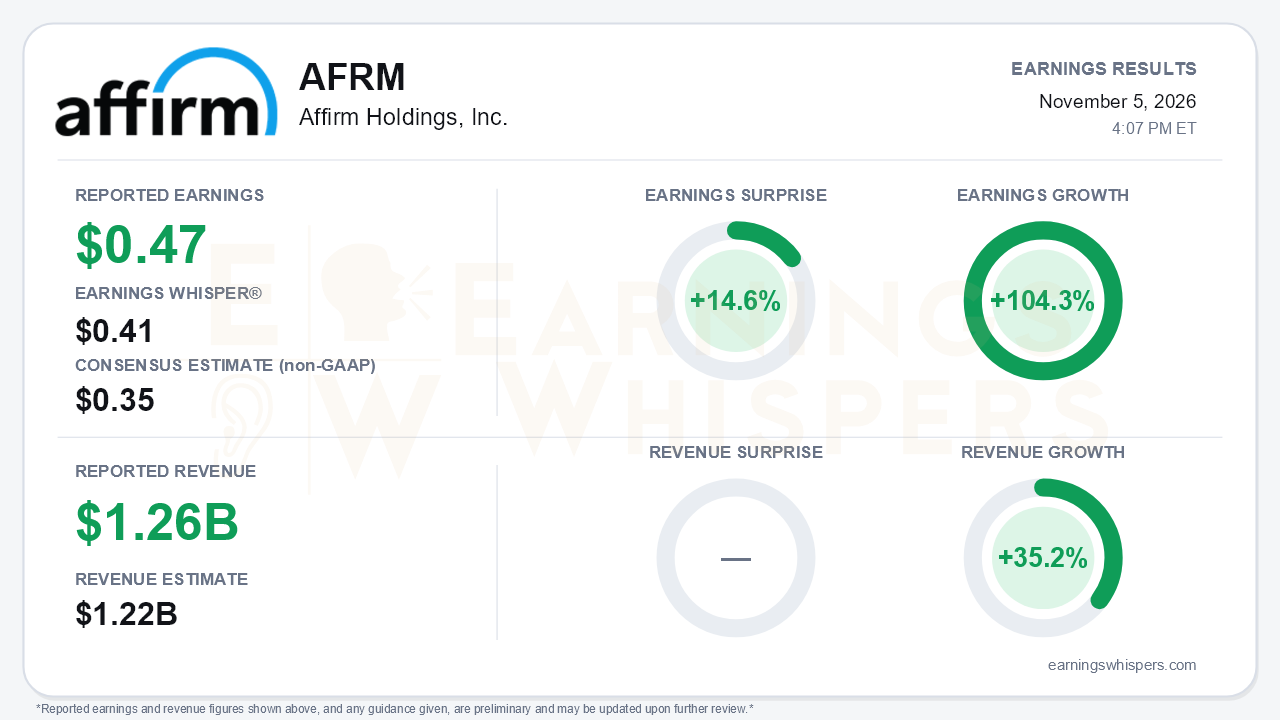
Affirm opened fiscal 2027 with a clean beat. Earnings of $0.47 per share topped the $0.35 non-GAAP consensus and the $0.41 Earnings Whisper number, a 14.6% surprise. Revenue of $1.262 billion beat the $1.22 billion consensus by 3.5%. Earnings grew 104.3% year over year and revenue rose 35.2%. The more important development was that growth re-accelerated rather than fading. A year earlier, management had guided investors to expect gross merchandise volume growth to slow toward roughly 25% after losing a top-three merchant. Instead, GMV grew 34% in the September quarter, and management said September and early fiscal second-quarter trends are running in the high-30s. The central tension is that this top-line strength arrived alongside a modest uptick in credit costs, higher funding costs and a GAAP margin outlook below Street expectations. Those items were enough to sour the initial market reaction.
The quality of the beat holds up better than the stock's response suggests. Revenue less transaction costs reached 4.3% of GMV. That is above the roughly 4.16% fiscal 2027 target management set last quarter and well above the 3.25%-4% medium-term range. Funding costs as a share of on-balance-sheet loans fell year over year to about 6%, and more than 70% of that funding is fixed rate. Capital-markets access remains strong. A recent asset-backed deal was more than four times oversubscribed despite a weak equity tape, and Affirm executed three- and five-year fixed-rate ABS. The press release offered little detail beyond pointing to the shareholder letter, so the operating story rests largely on the call.
The call surfaced real blemishes. Provision expense as a percentage of GMV and delinquencies both ticked higher. Management attributed the increase to September approval experiments that Affirm kept on its balance sheet, along with seasonality. That explanation is plausible, but it is a change in tone from last quarter, when the message on credit was essentially that nothing gave management pause. Funding costs also rose 27 basis points sequentially as benchmark rates moved higher, which partly offsets the favorable year-over-year comparison. Merchant and network revenue as a share of GMV is under pressure from direct-to-consumer and card mix, because card interchange runs below Affirm's merchant discount rate. Finally, the fiscal second-quarter GAAP operating margin guide came in below consensus. Management tied the shortfall to heavier partner warrant expense linked to new-user growth in the UK. That expense is arguably the cost of growth rather than core deterioration, but it is still a cost.
On guidance, the overall message was constructive even though the headline outlook was characterized as in line. Management restated a floor of at least 30% GMV growth for fiscal 2027. CEO Max Levchin described "30-plus" growth as the internal minimum for a long time. Product catalysts are stacking up:
- A transformer-based underwriting model that management says roughly doubles risk separation versus the prior candidate, adding about 2-3 points of approvals with no incremental loss.
- Brand-sponsored promotions scaled to about one million SKUs in the Affirm app ahead of the holidays.
- Card-exclusive financing offers launching within days to weeks.
- ACH down payments replacing debit to reduce interchange costs.
- A services vertical, including Intuit and ServiceTitan, that remains the fastest-growing disclosed segment.
Management was also notably more expansive on agentic commerce than earlier in the year, when it called the opportunity very early. The softer spot is Affirm Edge. First bank pilots are now slated for the first half of calendar 2027, which appears to be a later timeframe than last quarter's framing. Management stressed patience, and no partners have been named.
Investor sentiment cooled heading into the report, slipping from 0.28 to 0.17. It remains positive but is clearly less enthusiastic. Price action tells a similar story. As of the pre-report snapshot, shares were at $75.59, down 12.1% from the $86.00 open after the August report and 16.4% below the $90.44 52-week high set on the first trading day after that release. The stock still sat 13.6% above its 200-day moving average and about 14.5% above its September low of $66.03. The call analysis indicates shares sold off after this report, so the stock is again giving back ground despite a beat. Sequential growth, momentum and AVWAP trend readings remain positive, while the price trend is neutral.
The bottom line is that Affirm delivered the growth re-acceleration and take-rate outperformance that bulls wanted. GMV beat last year's deceleration roadmap by a wide margin, and unit economics ran ahead of plan. Bears have legitimate ammunition in rising provisions, a sequential jump in funding costs, a light GAAP margin guide and a slipping Edge timeline. The key question for the coming quarters is whether the September credit uptick proves to be a contained experiment or the start of a trend. If credit holds, the growth story looks more durable than the stock's reaction implies.
Read our earnings preview for Affirm Holdings, Inc.: https://www.earningswhispers.com/article/AFRM/22225
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-29 | |
| Oct-28 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-26 | |
| Oct-22 |
