Quantum-Si Beats On A Narrower Loss As Platinum Revenue Fades; Proteus Execution Is Now The Whole Story
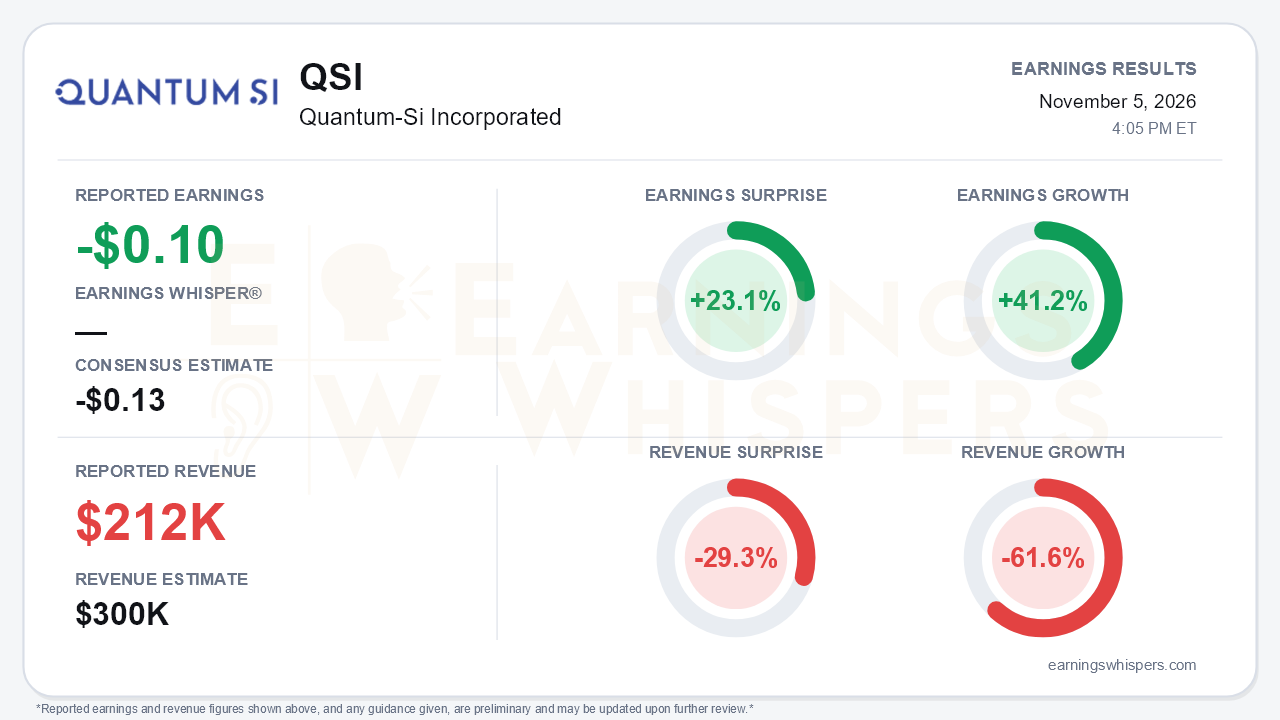
Quantum-Si reported a third-quarter loss of $0.10 per share, beating the -$0.13 consensus by 23.1% and improving 41.2% from a year ago. Revenue went the other way. Sales of $0.21 million missed the $0.3 million consensus by 29.3% and fell 61.6% year over year. That split is the quarter in miniature. QSI is no longer being valued on its income statement. It is being valued on whether Proteus launches on time in the second quarter of 2027, and on whether the cash lasts long enough to get there. On that test, the quarter was considerably better than the revenue line suggests.
The quality of the EPS beat deserves scrutiny. GAAP net loss narrowed to $22.3 million from $35.7 million, but much of the improvement comes from an easy comparison. The year-ago quarter carried $13.6 million of net lease termination expense and $1.8 million of legal settlement costs, while this quarter absorbed $2.9 million of restructuring charges. Interest income also fell to $1.4 million from $2.4 million as the cash pile shrank. The cleaner measure, adjusted operating expense, came in at $18.2 million. That compares with $21.4 million a year ago and $22.6 million in the second quarter, a genuine sequential step down as the August reduction in force (about 20% of headcount, targeting roughly $12 million in annual savings) took hold. Adjusted EBITDA improved to -$17.0 million from -$20.1 million.
The legacy business, meanwhile, is fading faster than a casual read implies. Revenue slid sequentially from $344,000 in Q2 to $212,000. Gross margin dropped to 35% from 50% in the prior quarter. Management frames 2026 through mid-2027 as a deliberate transition, with customers holding off on Platinum instruments in anticipation of Proteus. The reaffirmed full-year revenue target of about $1.0 million, against $814,000 through nine months, signals no near-term recovery. Bears have legitimate ammunition here: the company is effectively pre-revenue for at least another two to three quarters.
The call, however, preserved a credible development story and arguably repaired the damage from the Q2 launch delay. Management said the instrument variability that caused the delay has been "substantially addressed." Design changes were fewer than expected, and first instruments from the new build are due in Q4. Other technical milestones also improved:
- Amino acid detection advanced to 19, up from 17 in Q1.
- All 20 are now targeted at launch, versus "either 19 or 20" last quarter.
- World HUPO data showed roughly 30 times the output per chamber of Platinum Pro.
- The false discovery rate fell to 1.36% from 6.58%.
Management also opened a formal pre-order program with deposits and priority access. It cited a roadshow spanning 35-plus cities and 800-plus attendees, with the funnel split evenly between new and existing users. Pre-orders are a softer signal than booked revenue, but they give investors something measurable to track into launch.
On the balance sheet, full-year adjusted opex guidance was cut to $87 million or less from $98 million, and cash usage guidance to $87 million or less from $93 million. These cuts largely ratify the lower run rate already achieved rather than signal a new round of savings. Cash fell to $149.4 million from $169.9 million in Q2, and runway into the fourth quarter of 2028 was reaffirmed. The newest risk is supply-side. AI-driven demand is stretching lead times on components, pushing QSI into earlier and larger inventory purchases that tie up working capital. Management says this will not affect the launch date, but it is a pressure point on both timing and cash. The launch still hinges on the new build performing as designed.
The market had already moved aggressively ahead of the report. Shares rose 72% from the $0.75 open after the Q2 release to $1.29, about 34% above the 200-day moving average. Notably, the stock has climbed back above $1 after a period in which Nasdaq listing maintenance appeared among the company's cited risks. Investor sentiment swung sharply, from -0.36 after the prior report to +0.59, a near-complete reversal in expectations. Yet the stock entered earnings almost 29% below its October 29 inter-earnings high of $1.81, so some of that enthusiasm had already cooled. Price and AVWAP trends are positive, while sequential growth and momentum remain negative. That mix fits a stock trading on catalysts rather than financials.
The bottom line is that Quantum-Si delivered a narrower loss, lower spending and a stack of technical milestones that make the Q2 2027 Proteus launch look more credible than it did three months ago, even as Platinum revenue withers. With sentiment having flipped from pessimism to optimism and shares well off their lows, the setup now depends less on cost control and more on whether upcoming Proteus updates, first builds and pre-order traction validate what the market has already begun to price in.
Read our earnings preview for Quantum-Si Incorporated: https://www.earningswhispers.com/article/QSI/22368
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-16 | |
| Oct-15 | |
| Oct-08 | |
| Oct-01 | |
| Sep-28 | |
| Sep-20 | |
| Sep-15 | |
| Sep-09 | |
| Aug-18 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 |
