InTEST Beats On Mix-Driven Margin Surge As Record Semi Orders Build 2027 Visibility, But Q4 Guide Signals A Profit Plateau
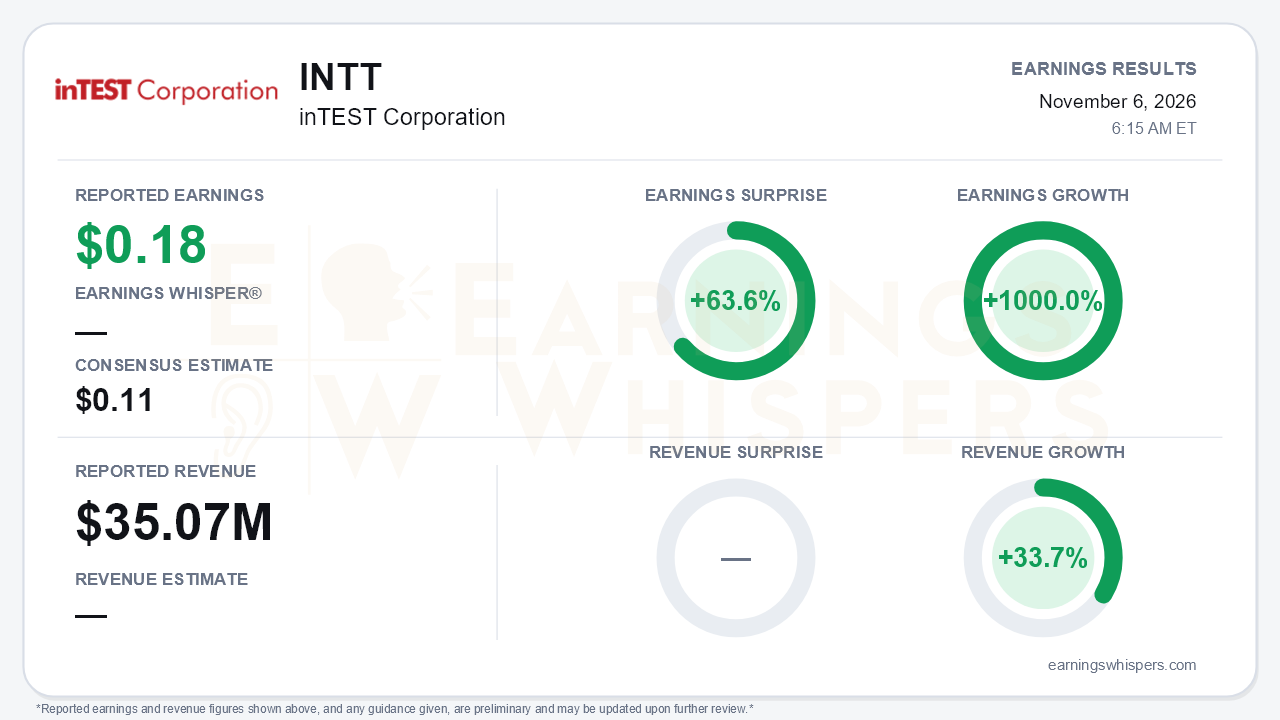
inTEST Corporation (NYSE American: INTT) delivered its strongest quarter in some time. Adjusted EPS of $0.18 beat the $0.11 consensus by 63.6% and swung from a $0.02 adjusted loss a year earlier, which works out to 1000.0% year-over-year growth. On a GAAP basis, the company earned $0.15 per diluted share versus a loss of $0.08. Revenue rose 33.7% to $35.07 million. The more important number, though, sits outside the income statement. Orders reached a record $49.4 million, a book-to-bill of roughly 1.41, and lifted backlog to a record $59.7 million. The semiconductor recovery management has been flagging all year has finally shown up in demand. It has not yet shown up in revenue, and that is the central tension.
The beat came almost entirely from margin, not volume. Revenue was essentially flat sequentially, at $35.1 million versus $35.3 million in the second quarter. A $6.8 million, 50% sequential drop in Auto/EV revenue was offset by gains in Semi (up 27% to $11.5 million), Defense/Aerospace (nearly doubling to $7.4 million) and Industrial. That mix shift toward higher-margin Semi pushed gross margin up 720 basis points to 47.7%. That was well above the roughly 44% management had guided and far above Q2's 40.5%. Operating expenses held at about $14.0 million, so the margin gain flowed straight through. Adjusted EBITDA doubled sequentially to $4.4 million, a 12.6% margin, and operating income rose to $2.7 million from $363,000. The Electronic Test segment carried the quarter, nearly tripling division operating income from a year ago to $3.4 million. Process Technologies swung from a small loss to a $964,000 profit.
The order book is where the story changed. Semi orders of $25.1 million more than doubled from Q2 and more than tripled year-over-year. Back-end orders hit a record $23.9 million as customers added capacity for power, analog and mixed-signal devices. Management said customers are ordering earlier as tester lead times stretch to roughly 18 months. It described a Q4 sales funnel about as large as the one entering Q3. Roughly 60% of backlog is expected to ship beyond the fourth quarter, and management expects much of the Semi intake to convert in the first half of 2027. That is unusual multi-quarter visibility for a small-cap test supplier. Auto/EV orders more than doubled sequentially to $9.4 million and Defense/Aerospace orders rose 43%. New wins include a major automaker's first functional test order, a data storage customer and a silicon carbide evaluation order. Management's tone shifted from cautious optimism on Semi earlier in the year to a clear message that demand has arrived.
Bears still have legitimate ammunition. The fourth-quarter outlook of $34 million to $36 million in revenue is flat at the midpoint. Gross margin is guided back to about 45% as mix normalizes, and operating expenses step up to $14.2-$14.7 million as leadership roles are filled. Together, those assumptions point to a lower operating profit than Q3 delivered. The full-year tax rate also moves up to about 20% from 18%. Full-year revenue is tracking toward the high end of a $135-$140 million range that has been raised twice this year, but the Q4 guide is essentially in line rather than a step-up. Other cracks:
- Free cash flow was negative at about $0.6 million.
- Receivables climbed and cash fell $1.2 million.
- Year-over-year Auto/EV orders still fell 36% against a strong comparison.
- Supply chain lead times are lengthening.
- A refreshed S-3 shelf raises the possibility of dilution.
- A material weakness disclosed in Q2 is still being remediated.
Management itself framed Semi strength as lasting "into the early part of 2027 at least," which leaves the cycle's duration an open question.
The market has been skeptical. Shares closed at $12.30 the day before the report, down 5.7% from the opening price after the August release. They sit 11.7% below the 200-day moving average of $13.94. The stock did rally from a September 18 low of $10.30 to a quarter high of $16.28 on October 28, but it surrendered about 24% of that peak in the final days before earnings. That leaves it roughly mid-range between those levels. Investor sentiment improved modestly, from slightly negative (-0.08) to roughly neutral (+0.01). That is less a vote of confidence than an absence of conviction in either direction.
The bottom line is that inTEST's quarter was better in substance than the flat sequential revenue suggests. A record order book and backlog give it genuine 2027 visibility, and Q3 showed what Semi-heavy mix can do for margins. The near-term guide, however, points to margin normalization, higher costs and soft cash conversion, so the earnings power on display this quarter is not yet a run rate. For a stock that sold off hard into the print and still trades below its long-term average, the burden now shifts to converting that backlog into revenue on schedule and proving the cycle extends beyond early 2027.
Read our earnings preview for inTEST Corporation: https://www.earningswhispers.com/article/INTT/22490
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-04 | |
| Oct-29 | |
| Oct-27 | |
| Oct-06 | |
| Oct-02 | |
| Aug-13 | |
| Aug-10 | |
| Aug-10 | |
| Jul-31 | |
| Jun-29 | |
| May-20 | |
| May-15 | |
| May-05 | |
| Apr-27 |
