AirSculpt's Turnaround Reverses: Same-Center Demand Slumps, EBITDA Nearly Vanishes, And Guidance Is Cut Again
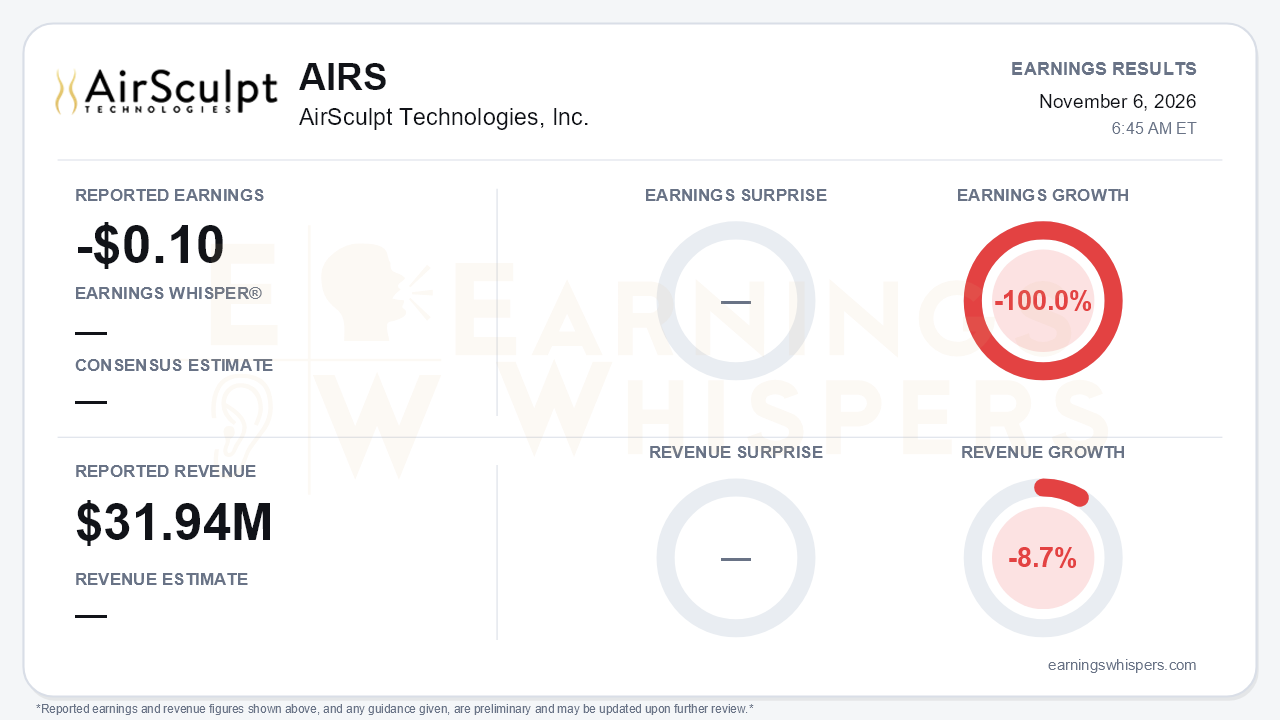
AirSculpt Technologies (NASDAQ: AIRS) reported a third-quarter loss of $0.10 per share on revenue of $31.94 million. Earnings fell 100.0% year over year and revenue declined 8.7%. No consensus estimate or Earnings Whisper was available, but management did not need one to frame the result: CEO Yogi Jashnani said the quarter came in below expectations. The company cut full-year guidance for the second consecutive quarter. The central takeaway is that the early-2026 recovery narrative has broken down. Same-center demand turned sharply negative, and the business's thin profit cushion nearly disappeared.
The quality of the headline numbers deserves scrutiny because GAAP flatters the comparison. Net loss narrowed to $7.2 million from $9.5 million, but only because the year-ago quarter carried a $7.1 million impairment charge. The adjusted figures show the real trajectory. Adjusted net loss widened to $6.1 million, or $0.08 per share, from $2.4 million, or $0.04. Adjusted EBITDA collapsed to $0.4 million, a 1.2% margin, from $3.0 million (8.7%) a year ago and $4.9 million (11.5%) in the second quarter. Selling, general and administrative expense rose to $20.3 million even as revenue fell, which shows how little operating leverage remains when volume slips. Operating cash flow was negative $3.5 million for the quarter. Shareholders are also absorbing dilution: weighted shares rose to 72.5 million from 62.4 million, and the company raised another $7.2 million through its at-the-market program during the quarter.
Beneath the totals, the problem is demand capture rather than pricing or conversion. Same-center cases fell 9.6% after two quarters of growth. Same-center revenue declined 7.5%, compared with roughly -1% in the second quarter and +1% in the first. Management attributed much of the shortfall to Google AI Overviews reducing search clicks. Leads fell 16% year over year, cost per lead jumped 26%, and customer acquisition cost climbed to about $3,800 per case from $3,500 in Q2 and $3,100 a year ago. Execution issues at a handful of centers compounded the pressure, and some of those problems are taking months to fix. The bright spots are real but secondary. Gross margin improved to about 60% from 57.5% a year ago, though it slipped from roughly 61% in Q2. Average selling price rose 2.3% to about $12,900, and conversion rates held steady. When the funnel shrinks, however, price and conversion cannot offset the lost volume.
The guidance path tells the story of eroding visibility:
- **Revenue:** Now $144-146 million, down from $151-157 million.
- **Adjusted EBITDA:** Now $9-10 million, down from $12-14 million last quarter and $15-17 million at the start of the year.
The new outlook assumes third-quarter weakness persists. It implies fourth-quarter adjusted EBITDA of only around $0.4-1.4 million, and management still described the consumer as choppy. Management also cut planned incremental brand marketing to $3 million from $5 million. That cut protects near-term cash but raises questions about how the company rebuilds lead flow.
The call did preserve some catalysts:
- **GLP-1 procedures:** These have climbed steadily, from more than 100 skin removals in Q4 FY25 to about 250 procedures this quarter, nearly 10% of cases. They are now offered in nearly all centers, and management continues to cite a $100 million-plus long-term opportunity.
- **New initiatives:** The Alloclay rollout is expanding. A first-ever network-wide open house is scheduled for November 12, and the company is shifting toward AI-search optimization and grassroots marketing to reduce its reliance on Google.
- **Refinancing:** The new $39 million term loan and $5 million revolver from Blue Torch push the maturity out to 2031 from November 2027, with lower amortization and more covenant headroom.
The refinancing has a cost. Interest rises roughly 300 basis points to SOFR plus 775, and gross debt edges slightly higher just as EBITDA shrinks. Liquidity has also declined to about $20 million from roughly $24 million in Q2. Bears have legitimate ammunition here: the company has bought time, but at a higher price.
Investor sentiment and current price data were not available for this report. For context, shares opened at $2.87 after the August report, below the current 200-day moving average of $3.10. The stock was already trading at depressed levels before this second guidance cut.
The bottom line is that AirSculpt's third quarter replaced a tentative turnaround story with a customer-acquisition problem that management has not yet shown it can solve. Pricing, gross margin, and GLP-1 procedure growth are holding up, and the refinancing removes a near-term maturity overhang. However, falling same-center volume, rising acquisition costs, near-breakeven EBITDA, and a guidance trajectory that has fallen for two straight quarters leave the burden of proof squarely on execution in the coming quarters.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-02 | |
| Sep-05 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-03 | |
| May-27 | |
| May-08 | |
| May-01 | |
| Apr-06 | |
| Apr-02 | |
| Apr-02 |
