Treace Medical Concepts Beats On A Narrower Loss And First Positive Adjusted EBITDA, But Revenue Still Shrinks As Volume Gains Fail To Reach The Top Line
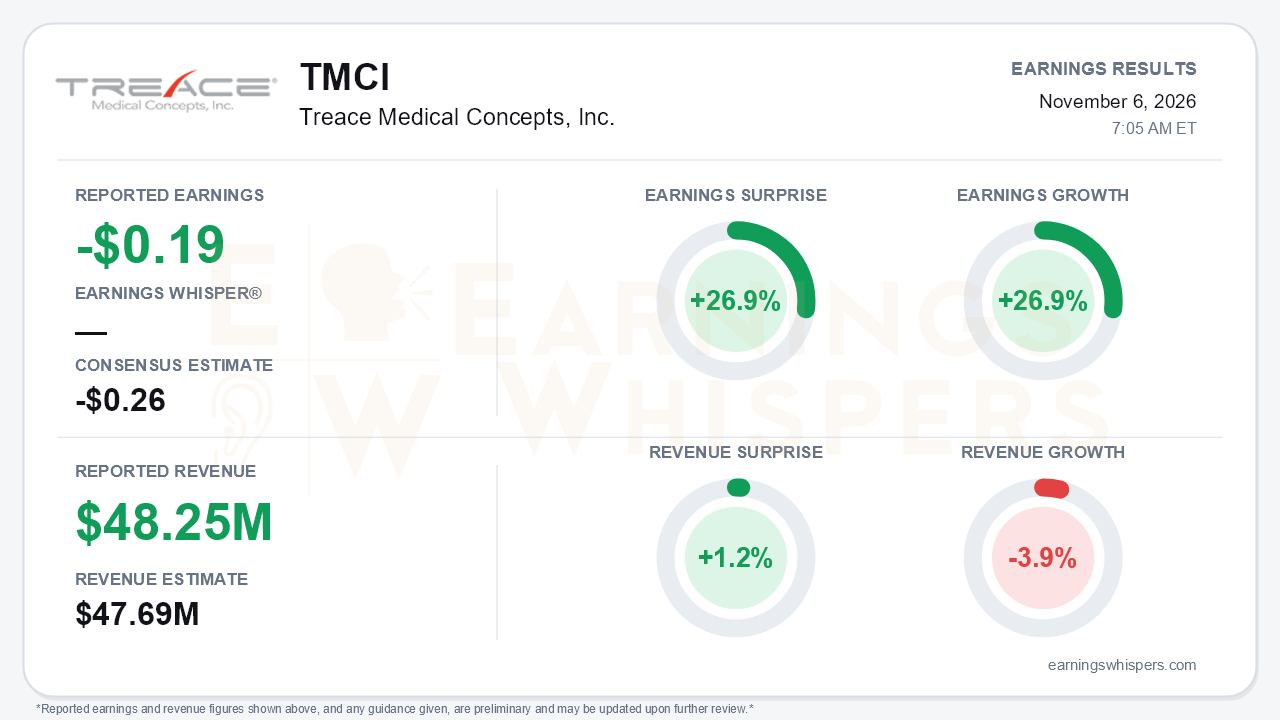
Treace Medical Concepts delivered the cleanest operating quarter it has posted in some time, but it still did not deliver revenue growth. The bunion-correction specialist reported a third-quarter loss of $0.19 per share, beating the -$0.26 consensus by 26.9% and improving 26.9% from a year ago. Revenue of $48.25 million topped the $47.69 million consensus by 1.2% but fell 3.9% year over year. The central tension is that case volumes accelerated to double-digit growth while revenue declined. Treace is winning procedures and losing price per case, and the bet on the stock now rests on when those two lines converge.
Most of the earnings improvement came from cost discipline rather than sales. Operating expenses fell 10% to $49.9 million, led by a $4.7 million cut in sales and marketing. Gross margin edged up to 79.5% from 79.1%, which is notable given the mix shift toward lower-priced minimally invasive products. Adjusted EBITDA turned positive at $0.3 million, compared with a $2.6 million loss a year earlier, and management stressed that this happened in a seasonally weak quarter. The quality of that milestone deserves some scrutiny. On a GAAP basis, Treace still lost $12.6 million. Adjusted EBITDA excludes $6.9 million of share-based compensation and $2.7 million of intellectual-property litigation costs, and those litigation costs more than doubled from a year ago.
The call made a credible case that underlying demand is strengthening. Case volume growth has stepped up from mid-single digits in the first quarter to high-single digits in the second and double digits in the third. Adoption of the three bunion systems launched in 2025 reached 45% of Lapiplasty surgeons, up from 40% in the second quarter, 35% in the first and 25% at the end of 2025. Two factors explain why revenue is still falling despite these gains:
- **Stocking distributors.** Excluding stocking-distributor orders, revenue grew mid-single digits. Management expects that comparison headwind to fade significantly after the third quarter.
- **Mix dilution.** Revenue per case continues to fall as surgeons shift toward minimally invasive systems and the broader portfolio.
On the product side, management widened its addressable-market expansion. The company now claims about $700 million of new market from 2026 launches, including SuperBite screws, HyperPlate XM, VitaFuse, CartoBlaster and the TaylorPlasty bunionette system. That compares with roughly $300 million cited earlier in the year. Five-year Lapiplasty outcome data, which the company called a first for a commercial instrumented bunion system, adds clinical support for the core franchise.
Guidance cut both ways:
- **EBITDA outlook improved.** The full-year adjusted EBITDA loss guidance improved again, to $1–2 million from $3–5 million. That is the third consecutive improvement.
- **Revenue outlook narrowed.** Revenue guidance was narrowed to $206–210 million. The low end rose for a third straight quarter, but the high end was trimmed from $212 million despite the third-quarter beat, leaving the $208 million midpoint unchanged.
- **Fourth quarter carries the load.** With $140.8 million booked through nine months, the range implies fourth-quarter revenue of roughly $65–69 million. Management's own assumption of improving year-over-year growth rates means the fourth quarter has to demonstrate the return to growth the third quarter did not.
- **Product delay.** Lapiplasty Lightning slipped from a targeted limited launch in the fourth quarter of 2026 to a full launch in the first quarter of 2027.
That combination adds execution risk to a seasonally heavy quarter crowded with launches, while peers are flagging slower elective procedure volumes.
The balance sheet gives bears legitimate ammunition. Cash and marketable securities fell to $39.8 million from $45.6 million in the second quarter and $51.9 million in the first. Year-to-date operating cash use of just $0.7 million looks impressive, but it leaned heavily on working capital. A $11.6 million drawdown in receivables and a $7.6 million rise in payables did much of the work, while inventory grew by $6.3 million. The $115 million of additional borrowing capacity under the credit facility, available subject to conditions, provides a cushion.
Investors were not positioned for good news. Earnings Whispers sentiment swung from slightly positive (0.04) to clearly negative (-0.26) ahead of the report, a meaningful shift. Shares closed at $4.18 the day before the release, down 18.5% from the $5.13 open after the August report. The path was volatile. The stock dropped to $3.78 in early October, rallied to $5.25 on October 29, then gave back about 20% of that peak within a week. Shares still sit roughly 28% above their 200-day moving average of $3.27, so the longer-term trend has improved even as the short-term move faded.
The bottom line is that Treace beat on earnings and reached adjusted EBITDA breakeven largely through cost control. Accelerating case volumes and rising surgeon adoption suggest the commercial strategy is gaining traction. Even so, revenue is still shrinking, the high end of guidance came down, a key launch slipped and cash keeps declining. The fourth quarter now has to prove that volume growth can finally outrun mix dilution, and until it does, skepticism toward the story is understandable.
Read our earnings preview for Treace Medical Concepts, Inc.: https://www.earningswhispers.com/article/TMCI/22502
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Nov-03 | |
| Oct-29 | |
| Oct-23 | |
| Sep-26 | |
| Sep-17 | |
| Sep-15 | |
| Aug-07 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Jul-24 |
