FTAI Infrastructure Posts Record EBITDA And A Narrower Loss, But The Long Ridge Exit And USD Deal Now Define The Equity Story
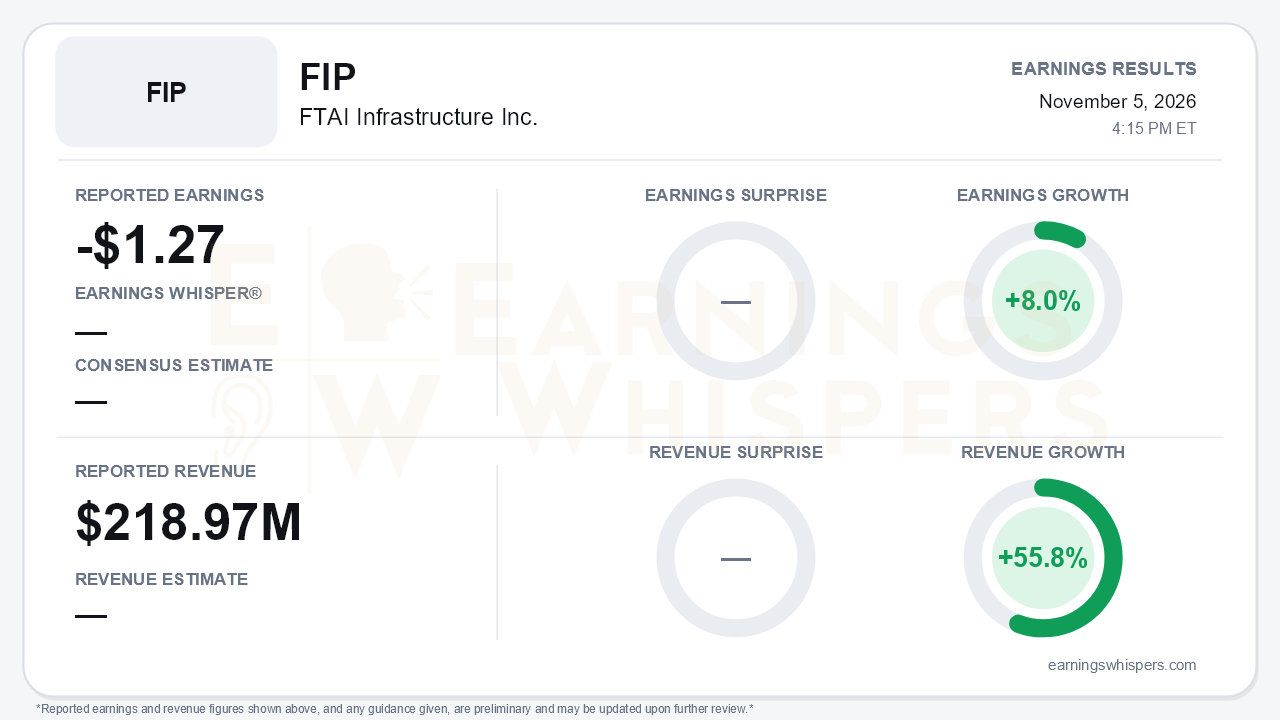
FTAI Infrastructure delivered its strongest operating quarter to date even as GAAP results stayed deep in the red. The company lost $1.27 per share, an 8.0% year-over-year improvement from the $1.38 loss a year earlier. Revenue rose 55.8% to $218.97 million. Adjusted EBITDA hit a record $95.3 million, up from $70.9 million a year ago and well above the $76.1 million in Q2 and $70.6 million in Q1. That is clear sequential acceleration. The more important development, though, is that the quarter turned several long-promised transactions into dated events. Long Ridge received regulatory approval, the USD Group acquisition is set to close in November, and Jefferson signed new crude customers. Those deals, more than the headline loss, now shape the investment case.
The gap between EBITDA and GAAP results deserves scrutiny. Several large items drove the $150.2 million net loss attributable to common holders:
- $116.5 million of interest expense;
- a $28.6 million impairment in Power and Gas;
- a $25.6 million non-hedge derivative charge in the railroad segment;
- $40.5 million of preferred dividends and accretion, mostly tied to the RailCo preferred.
The balance sheet shows the strain. Stockholders' equity swung to a $544 million deficit from a positive $21 million at year-end. Cash stood at $52.4 million, plus $88.3 million of restricted cash. Nine-month operating cash flow was still negative at $8.4 million, though far better than the $115.3 million outflow a year earlier. Mix also matters. Long Ridge contributed roughly $41 million of the quarter's EBITDA. The record $54.4 million ex-Long Ridge figure, up from $48.7 million in Q2, is the more relevant base once the sale closes.
Rail is the cleanest part of the story. Revenue climbed to $104.2 million from $92.2 million in Q2 and $85.0 million in Q1, and segment EBITDA reached $47.4 million versus $42.4 million and $40.2 million. Management now explicitly guides to double-digit revenue and EBITDA growth into 2027, with mid-single-digit pricing and some high-single-digit increases. Other supports for that outlook:
- the Gary Works blast furnace returned to full capacity in September;
- the Wheeling systems cutover is complete, with management targeting an operating ratio in the low 70s from 76.6%;
- Nippon Steel's roughly $3 billion Mon Valley investment could add 30,000 to 50,000 carloads and about $20 million of EBITDA, though over two to three years.
Management called the rail M&A environment the most active in decades, and the tone was noticeably more confident. Investors should note that a pivot toward larger rail deals also adds execution and leverage risk.
Jefferson is where the story both improved and weakened. Q3 crude volumes fell to just 41,000 barrels per day amid Middle East disruption, with no Saudi imports in July. Management described the recovery as choppy, although October volumes rebounded to 85,000 barrels per day. Segment EBITDA still edged up to $14.2 million from $13.0 million. The bigger change is the USD Group deal. For $255 million, FTAI acquires a Beaumont crude terminal and a 50% stake in an Alberta diluent recovery unit, adding about $50 million of take-or-pay EBITDA from an investment-grade customer. Two new crude export customers starting January 1 add roughly $8 million more. Management says combined Jefferson EBITDA could exceed $100 million, positioning the asset for a 2027 sale. Bears have legitimate ammunition here. The three organic Jefferson expansions, worth more than $50 million of EBITDA and promised for execution this year, remain unsigned, so Jefferson's growth now leans on purchased rather than built EBITDA.
Several timelines and targets also slipped:
- the Long Ridge close moved from a mid-Q3 target to the end of November;
- Repauno Phase 2 language softened from completion by year-end to "coming months";
- the Wheeling cost-savings target drifted to about $19 million from $23 million earlier in the year;
- expected parent-level interest savings from the Long Ridge deleveraging fell to roughly $25 million from about $30 million.
The Long Ridge sale, at about $1.5 billion, should still remove roughly $1.4 billion of debt. That is the single most consequential near-term event for a capital structure where common equity sits behind substantial debt, preferred and warrant claims.
Market context is limited. Shares opened at $3.11 after the August report, well below the 200-day moving average now at $4.47. That gap suggests the market had been treating the equity with considerable skepticism heading into a quarter of heavy transaction activity.
The bottom line is that FTAI Infrastructure posted genuinely improving operations, led by accelerating rail growth and record EBITDA, and converted its strategic plan into near-term closings. The investment case now rests less on quarterly EPS and more on execution. The Long Ridge deleveraging must close as promised, the USD assets must integrate smoothly, and Jefferson volumes need to stabilize. Slipping timelines, trimmed savings targets and still-unsigned organic projects mean the equity's improvement depends on deals closing rather than on results already delivered.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Oct-13 | |
| Sep-29 | |
| Sep-28 | |
| Aug-06 | |
| Aug-05 | |
| Jul-15 | |
| Jul-15 | |
| Jun-29 | |
| May-07 | |
| May-07 | |
| May-06 | |
| May-01 | |
| May-01 |
