Informa TechTarget Abandons 2026 Growth Target And Cuts EBITDA Outlook As Its Pipeline Fails To Convert
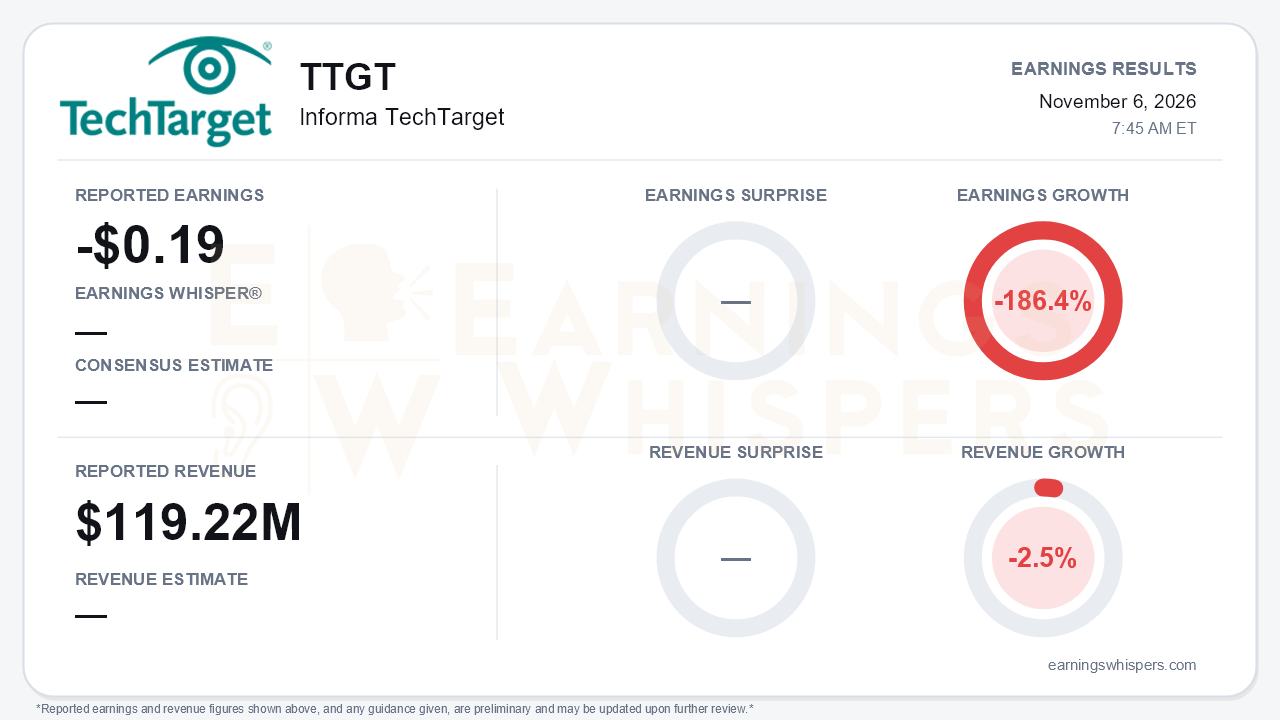
Informa TechTarget (NASDAQ: TTGT) reported a loss of $0.19 per share on revenue of $119.22 million for the September quarter. On Earnings Whispers' normalized basis, earnings fell 186.4% year over year, and revenue declined 2.5%. No consensus or Earnings Whisper estimate was available, so this quarter is not a beat-or-miss story. It is a guidance story. Management dropped its plan for 2026 revenue growth and now expects full-year revenue to be modestly lower than 2025. It also cut full-year Adjusted EBITDA guidance to $80 million to $85 million from the $95 million to $100 million range it had reiterated on every prior call this year. The company had defended that target as recently as August. Abandoning it now is the central development.
The headline loss needs context. On a GAAP basis, the net loss narrowed sharply to $18.2 million, or $0.25 per share, from $76.8 million, or $1.07, a year earlier. That improvement came almost entirely from the absence of last year's $80.3 million goodwill impairment and $12.4 million restructuring charge. Underlying profitability moved the other way:
- Gross profit fell to $67.8 million from $74.9 million as cost of revenues rose while sales slipped.
- Adjusted EBITDA dropped 17.9% to $18.6 million.
- Adjusted EBITDA margin compressed to 15.6% from 18.5%, which management attributed to lower revenue and cost inflation, partly offset by synergies.
- Selling and marketing expense fell nearly $5 million, so the cost savings are real but are not keeping pace with the revenue shortfall.
The normalized $0.19 loss and the GAAP $0.25 loss reflect different bases. Either way, this quarter's earnings sit well below the prior year's.
The revenue picture is more nuanced than outright deterioration:
- Year-over-year growth went from +2% in Q1 to -3.2% in Q2 to -2.5% in Q3, a modest easing of the decline.
- Revenue rose 2.6% sequentially.
- Brand to Demand, which grew about 5% in Q1, fell 2.5% on lower intent-data revenue and weak international campaign timing.
- Intelligence & Advisory fell 2.4%, with subscription gains offset by lower advisory work. The segment is down 4.5% year to date.
The call shows how the narrative shifted. In Q2, management cited a materially larger pipeline and stable win rates to justify its guidance. In Q3, it conceded that customers are pausing marketing spend while they prioritize AI investment, so the pipeline is converting more slowly. International weakness has also widened. What began as a Middle East issue in Q1 is now a broader divide in which Asian tech vendors are pulling marketing focus away from North America and Europe.
The call did preserve a credible, if longer-dated, growth story:
- The largest-client cohort posted double-digit bookings growth, and the 2027 order backlog increased.
- Intent bookings improved after the declines that hurt this quarter's revenue.
- Search traffic stabilized, with conversion to membership improving by roughly double digits.
- The audience base exceeds 59 million members.
- Buyer Intelligence, launched in Q3, has passed 40% user adoption. The MCP framework lets clients use TechTarget intent data inside their own AI workflows, and a Demandbase integration starts in January 2027.
These are reasonable building blocks. However, management had pointed to pipeline strength before, and it did not translate into revenue this year.
The guidance itself deserves scrutiny. Nine-month Adjusted EBITDA was $41.0 million, so the new range requires roughly $39 million to $44 million in the fourth quarter alone, about as much as the first three quarters combined. Q4 is seasonally strong because of the live events calendar, and last year's Q4 segment profit was far above other quarters. Still, the outlook depends heavily on a single quarter after the company just missed its own conversion assumptions.
The balance sheet has also tightened:
- Cash fell to $35.3 million from $45.8 million at the end of Q2.
- Revolver borrowings rose to $120.1 million, pushing net debt to $84.8 million, about 1x trailing Adjusted EBITDA.
- Nine-month free cash flow was negative $18.7 million.
- Adjusted free cash flow of $15.0 million trails the prior year's $25.7 million and implies a negative third quarter.
Management argues that integration and restructuring cash costs are largely behind it, which should produce cleaner cash flow in 2027. That is plausible, but it is a promise rather than a result.
Market context is limited. No investor sentiment readings or current price data were available. Shares opened at $3.69 after the August report, while the 200-day moving average stands at $4.21. That gap indicates the stock was already struggling before this guidance reset. Bears have legitimate ammunition: a reversed growth target, falling margins, rising leverage and a back-end-loaded outlook.
The bottom line is that Informa TechTarget's narrower GAAP loss is an accounting artifact of fading impairments, not evidence of an operating recovery. The real news is that management could no longer defend its 2026 growth and profit targets. Encouraging signals from large clients, the 2027 backlog and AI-integrated products give the turnaround case something to stand on. Investors will want proof that the pipeline converts and that the Q4 events season delivers before giving those signals much weight.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| 11 hours | |
| 12 hours | |
| Nov-05 | |
| Oct-29 | |
| Oct-27 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-06 | |
| Sep-30 |
