Kingstone Posts Record Quarter And Lifts EPS Guidance, But Premium Growth Is Losing Speed
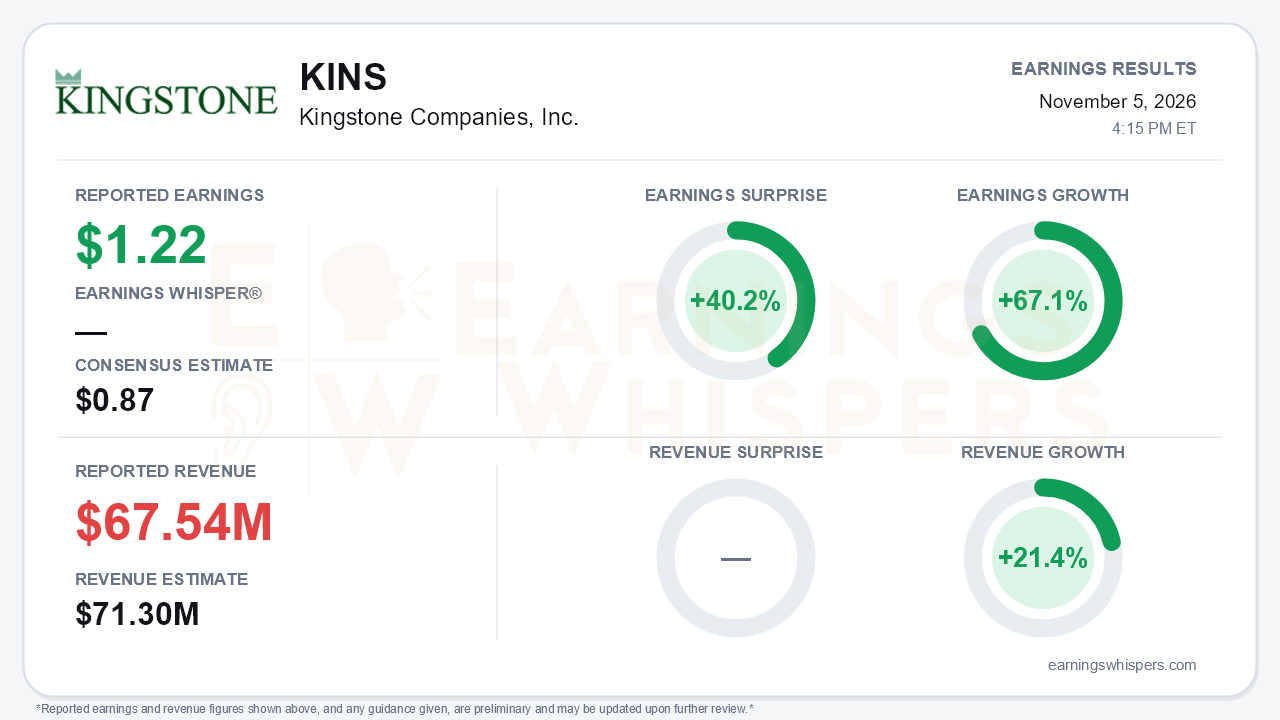
Kingstone Companies delivered the most profitable quarter in its history, and the earnings beat was large. Operating EPS of $1.22 topped the $0.87 consensus by 40.2% and grew 67.1% year over year. GAAP diluted EPS was $1.19, up from $0.74, on net income of $17.6 million. Revenue was weaker. Total revenue of $67.54 million grew 21.4% but missed the $71.3 million consensus by 5.3%. That split is the central tension of the report. Underwriting profitability is running well ahead of expectations, while the top-line growth that supports the long-term story is slowing. Management raised earnings guidance and trimmed premium growth guidance in the same release.
The beat is real, but its quality deserves a closer look. The GAAP combined ratio improved 7.1 points to 65.6% despite 7.5 points of catastrophe losses, up from just 0.2 points a year ago. Two forces offset the storm losses. First, favorable prior-year reserve development added 6.1 points, or $3.8 million, up from 2.7 points in the second quarter. For the first time, that development included casualty lines as well as property. Second, and more durable, the underlying loss ratio fell 10.6 points to 33.5%. The company cited lower claim frequency and severity, Select's growing share of the book and faster claims cycle times.
The weaker spots sit in expenses and revenue mix:
- The expense ratio rose to 30.7% from 28.4%, as last year's sliding-scale ceding benefit faded.
- Ceding commission revenue fell to $1.7 million from $4.9 million as the quota share was reduced. Net premiums earned rose 30% because Kingstone is keeping more of what it writes, but the lost commission income helps explain why total revenue still fell short of forecasts.
The operating trends show both momentum and deceleration:
- Retention improved 2.9 points, compared with about 2 points in Q2 and 1 point in Q1.
- Policies in force rose 11% to more than 86,000.
- Select penetration reached 65% of homeowner policies, up from 62% in Q2 and 57% at year-end 2025.
- Direct premiums written grew 14.5%, slowing from roughly 19% in Q2 and about 20% in Q1.
- New business policy count growth slowed sharply to 10%, from 35% in Q2.
On the call, management described New York competition that has broadened beyond the dwelling-fire softening first flagged last quarter. Rivals are loosening underwriting appetites, paying higher producer commissions and pricing aggressively. California has largely stalled. Admitted carriers reopened and excess-and-surplus capacity cut rates, so first-year premiums there will be a "fraction" of the roughly $10 million originally planned. As a result, full-year DPW growth guidance moved to about 16%, the bottom of the prior 16% to 20% range. That leaves little cushion for the roughly 15% annual pace needed to reach the company's $500 million premium target by 2029.
On the earnings side, the outlook improved materially:
- Diluted EPS guidance rose to $2.70 to $2.90 from $2.20 to $2.90, lifting the midpoint to $2.80.
- Return on equity guidance tightened to 29% to 30%.
- The GAAP combined ratio target improved to 79% to 83% from 81% to 86%.
Bears have legitimate ammunition here. Part of the raise reflects non-recurring reserve releases, $6.7 million year to date, and the guidance assumes no further development in the fourth quarter. The underlying combined ratio outlook was held at 74% to 76%, roughly in line with the 75.1% year-to-date figure. That suggests management is not extrapolating the exceptional 64.2% third-quarter result.
The new catalysts are concrete. The Connecticut admitted homeowners launch began on schedule in late September, and management reported strong producer reception. The rebuilt claims organization is now producing measurable results, both in reserve releases and in loss costs. The balance sheet tells a mixed story. Diluted book value per share rose 26.5% to $9.21, and 34.9% to $10.43 excluding accumulated other comprehensive income. However, $9.7 million of after-tax unrealized bond losses cut comprehensive income to $7.9 million, below the year-ago $13.1 million.
Investor sentiment shifted meaningfully, moving from -0.23 before the prior report to +0.19, a swing from mildly negative to modestly positive. The stock has not followed. Shares at $18.96 are 7.7% below the $20.54 open after the August report, even though that quarter was also a record. The stock remains 8.3% above its 200-day moving average of $17.51, so the longer-term trend is intact. The market appears to have been discounting peak-margin earnings and paying closer attention to the premium deceleration that this report confirmed.
The bottom line is that Kingstone's profitability story got stronger while its growth story got weaker. Lower claim costs and Select's rising share of the book point to underwriting gains with some staying power. Reserve releases and a fading ceding benefit, however, flatter the headline comparisons. With New York pricing tightening and California effectively shelved, Connecticut execution and the durability of the underlying loss ratio are now the key questions for whether the record earnings can be sustained as growth slows.
Read our earnings preview for Kingstone Companies, Inc.: https://www.earningswhispers.com/article/KINS/22321
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Oct-28 | |
| Oct-23 | |
| Oct-16 | |
| Sep-22 | |
| Aug-20 | |
| Aug-07 | |
| Aug-06 | |
| Jul-23 | |
| Jul-16 | |
| Jul-07 | |
| Jul-01 | |
| Jun-22 | |
| May-26 |
