Calumet Crushes Estimates With Record Quarter, But Management Itself Warns The Specialty Windfall Is Not The New Norm
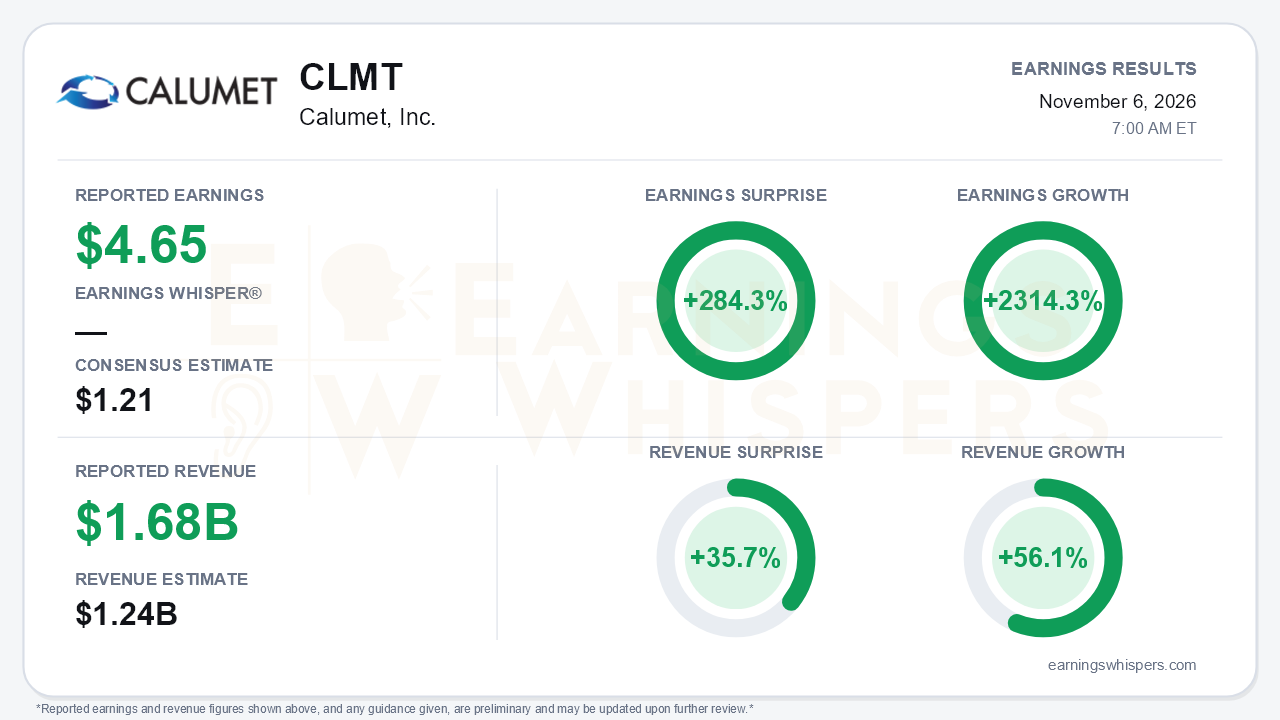
Calumet delivered a quarter that left Street estimates far behind. On Earnings Whispers' normalized basis, the company earned $4.65 per share against a $1.21 consensus, a 284.3% surprise. Earnings grew 2314.3% year over year. Revenue of $1.683 billion beat the $1.24 billion consensus by 35.7% and rose 56.1%. Adjusted EBITDA with tax attributes reached a record $347.2 million, roughly double the second quarter's $175 million and nearly four times the year-ago $92.5 million. The central tension is that much of this earnings power comes from an unusually tight specialty market that management openly says will normalize. That turns this into a story about how fast Calumet can convert a cyclical windfall into a permanently stronger balance sheet.
The quality of the beat deserves some scrutiny on the GAAP side. Reported basic EPS was $2.91, down from $3.61 a year ago. Net income was shaped by two non-cash items that pulled in opposite directions:
- a $113.8 million unrealized derivative loss;
- $176.7 million of non-cash RINs-related gains.
Equity-based compensation also jumped to $38.0 million from $5.9 million. The operating improvement itself, however, is unambiguous. Specialty Products & Solutions adjusted EBITDA rose to $248.1 million from $80.2 million. Segment margin was 23.2% versus 11.8%, and adjusted gross profit per barrel more than tripled to $48.04. Production volumes were actually slightly lower, so this was a pricing and margin story, not a volume story. Management attributed it to a global specialty shortage, lasting supply-chain disruptions, and commercial execution.
The sequential trajectory is what makes the quarter striking. SPS EBITDA has climbed from $44.3 million in the first quarter to $161.7 million in the second and $248.1 million now. Specialty margins topped $108 per barrel, versus $54 per barrel in the first quarter. Montana Renewables added a second engine. MRL posted record adjusted EBITDA with tax attributes of $80.4 million, or $1.86 per gallon, in its first full quarter since the SET2 RVO, up from $17 million in the second quarter. The Montana refinery (CMR) contributed $40.8 million. Management said fourth-quarter specialty demand is holding and framed the supply shortfall as a "2027 and beyond" story. Even so, it conceded that roughly $250 million SPS quarters are not the new baseline once global base oil capacity returns. Performance Brands remains the weak spot: EBITDA was $9.1 million versus $13.2 million, and that figure included $7.0 million of insurance proceeds while price increases lag feedstock costs.
The most durable development may be the balance sheet. Calumet has retired roughly $265 million of high-cost debt since July, saving about $26 million in annual interest. Consolidated net leverage is now about 3.0x, compared with 4.9x at year-end 2025, and the 2029 notes become callable at par in January. The MaxSAF reconfiguration is finalized: an amended DOE loan guarantee delivers about 70% of the original benefit, roughly $137 million, for less than 15% of the originally planned Phase II capital. The SAF ramp targets an 80 million gallon run rate by year-end and 200 million gallons in 2028. That year-end target sits at the low end of the prior 80-100 million range, and the 120-150 million gallon milestone has slipped from spring to end-2027. Bears also have legitimate ammunition:
- the fourth quarter carries heavy downtime from the Shreveport turnaround in October and the MRL tie-in for most of November;
- catalyst damage from the April outage still limits MRL rates;
- Warburg's preferred return rises to 11.5% PIK;
- stockholders' equity remains negative at -$870.7 million.
The market setup is more complicated than the surprise implies. Shares ran to a 52-week high of $59.87 on September 21 as the specialty boom became visible. They then gave back most of that spike, closing at $43.35 before the report. That is 27.6% below the high and only 6.1% above the open following the August report. The stock still sits about 11% above its 200-day moving average, so the longer-term trend has improved even as the fall pullback signals investor doubts about sustainability. Investor sentiment moved from slightly negative (-0.08) to modestly positive (0.16) ahead of the release. That is a meaningful improvement, but hardly euphoric.
The bottom line is that Calumet posted a record quarter that overwhelmed expectations and, more importantly, used the windfall to cut leverage sharply and de-risk its SAF growth plan. Investors now have to weigh a weaker, downtime-heavy fourth quarter and management's own warning that peak specialty margins will fade. Lasting value will depend on whether the stronger balance sheet holds after the cycle turns.
Read our earnings preview for Calumet, Inc.: https://www.earningswhispers.com/article/CLMT/22476
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-05 | |
| Nov-02 | |
| Oct-29 | |
| Oct-15 | |
| Oct-06 | |
| Sep-28 | |
| Sep-21 | |
| Sep-17 | |
| Sep-14 | |
| Sep-03 | |
| Sep-02 | |
| Sep-01 | |
| Aug-25 |
