SiriusPoint Crushes Estimates And Moves To Close Its Run-Off Book, But Flat GAAP Earnings And Lagging Net Premiums Show The Beat Is Less Clean Than It Looks
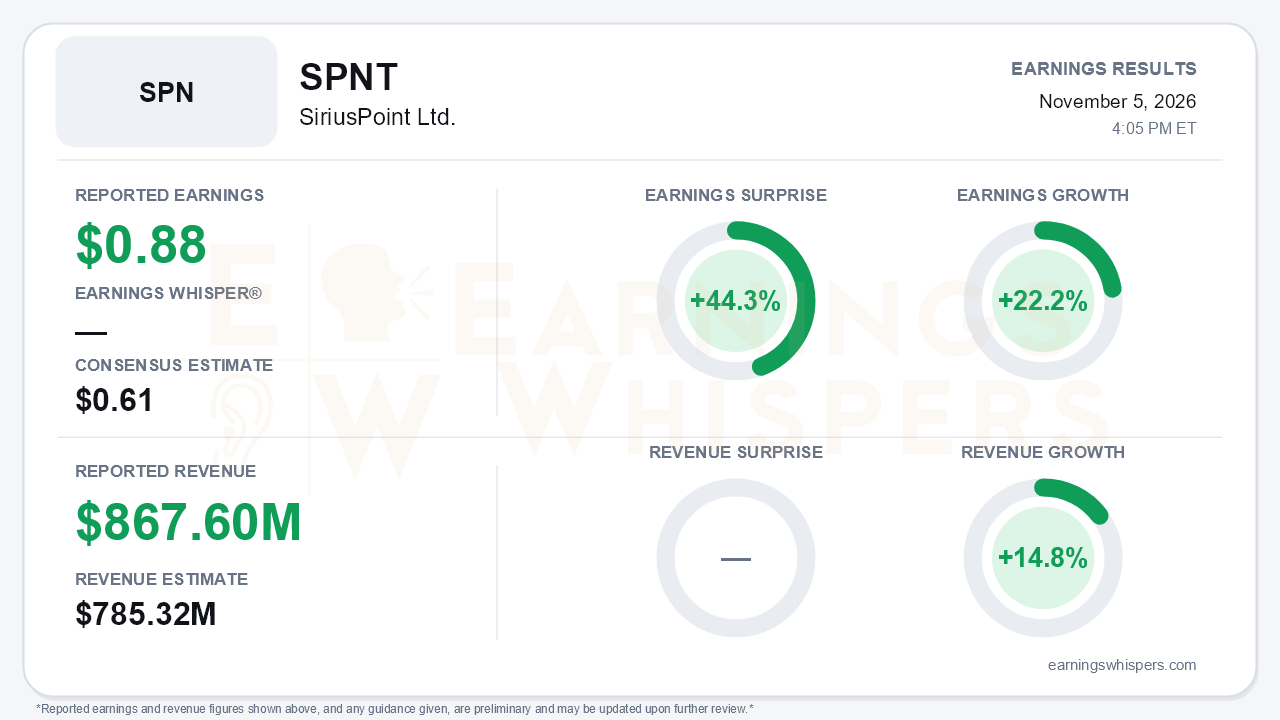
SiriusPoint delivered one of its strongest headline quarters in years. Operating earnings of $0.88 per share beat the $0.61 consensus by 44.3%, and Earnings Whispers calculates year-over-year earnings growth of 22.2%. Management cited a 19% increase from $0.74, a difference in prior-year basis. Revenue of $867.6 million topped the $785.32 million estimate by 10.5% and grew 14.8%. The bigger strategic news was a loss portfolio transfer with RiverStone covering substantially all remaining run-off reserves. That deal finally offers a path to remove the legacy book that has repeatedly clouded results. The central tension is that operating momentum is real and accelerating, but the quality of the beat deserves scrutiny.
Start with the headline numbers. GAAP net income available to common shareholders was $86.8 million, identical to a year ago, and diluted GAAP EPS was $0.74 versus $0.73. The gap to operating earnings came from investment losses, LPT-related expense, foreign exchange and other non-recurring items. Revenue also needs context. Net earned premium jumped 18.9% in Core, but much of that came from upward revisions to estimated earned premium in Professional Liability and A&H. The company says those revisions were largely offset by corresponding losses and acquisition costs, with no significant effect on underwriting income. The core combined ratio of 90.1% was a point worse than last year's 89.1%. Underneath, the attritional loss ratio improved two points to 57.0%. Favorable prior-year development doubled to $18.3 million. Offsetting those gains, the acquisition cost ratio climbed from 25.3% to 29.2%, driven largely by profit commission accruals.
The segment detail sharpens the picture. Insurance & Services grew gross written premium 19.8%, but its combined ratio deteriorated to 92.8% from 90.1% a year ago and 90.7% in Q2, and its underwriting income fell to $33.0 million from $37.7 million. Reinsurance was the profit engine, with an 86.0% combined ratio and underwriting income up to $42.9 million, but reserve releases in Property and Energy drove most of that improvement. Net written premium rose just 2% against 14% gross growth, and is roughly 1% lower year to date. The mix is shifting toward lower-retention lines such as surety. Book value per diluted share excluding AOCI rose 12% year to date to $20.21. Reported book value per share was essentially flat at $19.37, however, and tangible book value slipped to $17.30, reflecting AOCI losses and acquisition-related intangibles.
Still, the call preserved a credible and improving growth story. Core gross premium growth accelerated from 1% in Q1 to 6% in Q2 to 14% in Q3. Reinsurance returned to growth after declines of 9-10%. Operating ROE rebounded to 17.6% from 13.8% in Q2, and 15.8% year to date now sits above the 12-15% target. Further support came from three areas:
- employer stop-loss pricing, where rate expectations exceed 20%;
- expanded Lloyd's capacity;
- a reinvestment yield above 5%.
The RiverStone LPT is expected to unlock more than $200 million of capital and add roughly 20 points to the BSCR. That would reverse a steady drift from 247% at year-end 2025 to 232%. The $74 million remaining buyback authorization is expected to be largely completed by year-end once the deal clears. The planned Q4 segment recast, with A&H standalone and the rest as Specialty P&C, should make peer comparisons easier.
Bears have legitimate ammunition. The LPT carries an estimated $60 million day-one cost, requires regulatory approval and could slip into Q1 2027. A large international A&H program and a FinPro program were not renewed, and Specialty P&C premiums are guided modestly lower year over year in Q4. Reinsurance and property-cat pricing look soft into January renewals, and competition is intensifying in D&O, professional lines and marine. Analysts pressed on whether 22 consecutive quarters of favorable development can continue as pricing softens. Management is also monitoring emerging surety loss trends.
Investor sentiment moved the opposite way from the headline. Earnings Whispers sentiment fell from -0.08 to -0.25, a meaningful shift deeper into negative territory, though not an extreme one. The stock tells a steadier story. At $26.27, shares are 5.4% above the opening price after the July report and 13.6% above the 200-day moving average. The market has been rewarding the operating trajectory even as investors grow more skeptical.
The bottom line is that SiriusPoint's quarter marked a genuine acceleration in premium growth, returns and per-share value, and the RiverStone LPT could finally close the legacy chapter. But flat GAAP earnings, estimate-driven revenue, rising acquisition costs, reliance on reserve releases and anemic net premium growth mean the beat overstates the underlying improvement. Execution on the LPT close, Q4 premium trends and January renewal pricing will determine whether the momentum holds.
Read our earnings preview for SiriusPoint Ltd.: https://www.earningswhispers.com/article/SPNT/22387
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-28 | |
| Oct-22 | |
| Sep-15 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-24 | |
| Jul-16 | |
| Jul-01 | |
| May-26 | |
| May-09 |
