Ready Capital Narrows Its Core Loss And Clears 2026 Maturities, But Book Value Erosion And A Longer Path To Breakeven Overshadow The Beat
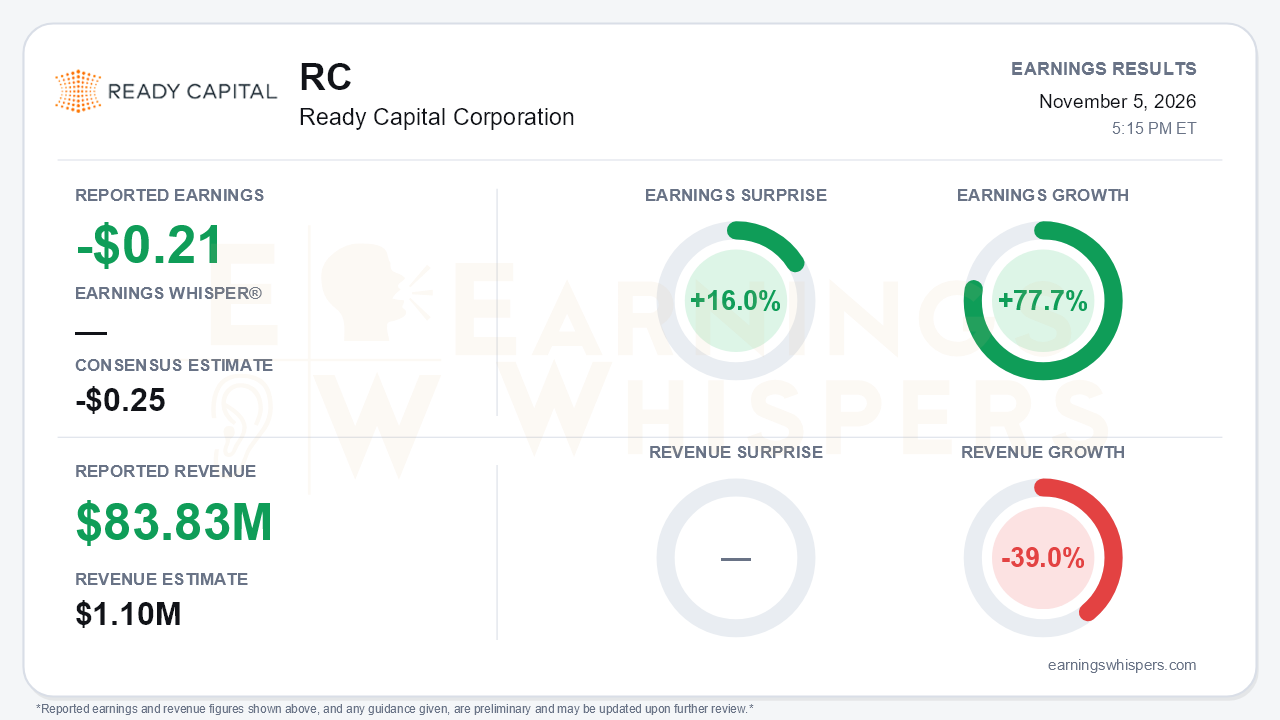
Ready Capital (NYSE: RC) beat expectations on its core measure. The company reported a distributable loss before realized losses of $0.21 per share, better than the -$0.25 consensus, a 16.0% surprise. Earnings Whispers calculates year-over-year earnings growth of 77.7%. The headline revenue comparison needs context: Earnings Whispers shows $83.83 million of revenue against a $1.1 million consensus, a 7520.7% surprise. That gap almost certainly reflects a definitional mismatch between interest income and a net figure, not a blowout quarter. The more telling number is the 39.0% year-over-year decline in revenue. It is a direct consequence of a balance sheet that has shrunk from $7.8 billion in total assets at year-end to $5.8 billion. The central tension is clear. The liquidity crisis that defined the past year is largely resolved, but shareholders paid heavily for that outcome, and management has pushed the destination further out.
The quality of the quarter deserves scrutiny. The $0.21 figure excludes realized losses. Including $53.9 million of realized losses on sales of investments, the distributable loss widened to $0.53 per share from $0.47 in the second quarter. The GAAP loss of $0.40 per share narrowed from $0.63 in Q2 and $1.25 in Q1, but it is still much worse than the $0.13 loss a year ago. Net interest income before provisions was essentially zero at about $1,000, down from $10.5 million a year earlier. The refinancing math is also unfavorable: Ready Capital issued $225 million of 10.00% senior secured notes while retiring $350 million of 4.50% notes. Book value fell to $6.44 per share from $6.83 in Q2 and $8.79 at the end of 2025. The pace of erosion is slowing, roughly 5.7% this quarter versus about 15% in earlier quarters, but the decline has not stopped. The quarterly dividend is now $0.01, compared with $0.125 a year ago.
The call did show genuine operating progress. Management said about $649 million of corporate debt will be repaid after the November maturity, with $2.3 billion of liquidity generated year to date. Other measures improved as well:
- Leverage eased to 2.8x from 3.0x, and unrestricted cash rose to $157.1 million from $124.1 million.
- Recurring revenue climbed to $20.7 million from $15.3 million.
- Operating expenses declined to $47.6 million from $67.7 million in Q1.
- SBA 7(a) originations rose 33% to $109 million, gain-on-sale jumped 56% to $6.1 million, and the pipeline nearly doubled to $150 million.
- Management raised its targeted capital allocation to SBA lending to 25-33% from 20%.
- Unsecured working-capital lending through iBusiness is expected to roughly double in 2027.
The small-business franchise is clearly where management sees the rebuilt company.
Bears, however, have legitimate ammunition in what was cut or softened:
- The goal shifted from a "return to profitability" in Q2 to bringing distributable earnings ex-losses "closer to break-even" during 2027.
- The explicit 25-35% opex reduction target became an unquantified "material" cut.
- The $1.5 billion annual SBA origination target was reframed as a $1 billion near-term run rate, with $1.5 billion now a long-term aim.
The legacy book is the bigger concern. Management has moved roughly $582 million of multifamily NPLs and REO into a long-term hold strategy. These assets carry about a 2.5% debt yield and roughly 70% occupancy, need around $15 million of capex, and have resolution timelines stretching into 2029. In Q2, management had cited an 11-month resolution duration. It also estimated that a higher 10-year Treasury knocked another 5-10% off multifamily values. Other pressure points:
- 14% of the performing bucket is on non-accrual.
- Servicing expense rose to $7.6 million from $3.4 million.
- Unencumbered assets slipped to $606 million from $690 million.
- Ritz-Carlton Portland condo sales have largely stalled at 39% sold, even as hotel RevPAR rose 35% to $271.
The forward catalysts are mostly structural. Management expects to announce non-core divestitures in coming quarters, and staff reductions in Q4 should deliver their full benefit in early 2027. It is also considering possible joint ventures to capitalize the long-term NPL/REO book. Moving $161 million of loans from held-for-sale back to held-for-investment signals that forced portfolio sales are over. That should reduce future realized-loss drag, if credit holds.
The market has priced in deep skepticism. Shares have fallen 31.4% since opening at $1.56 after the August report and now trade at $1.07, about 35.9% below the $1.67 200-day moving average. They also sit at a small fraction of the $6.44 stated book value, a gap that signals investors doubt the carrying values of the legacy assets. Investor sentiment improved only marginally, from -0.41 to -0.39, and remains firmly negative. That is consistent with a market acknowledging the narrower core loss without yet giving credit for a turnaround.
The bottom line is that Ready Capital has survived its maturity wall, and its core loss is shrinking quarter after quarter. Underneath, though, the company has eroded book value, cut the dividend to a token, raised its cost of debt, and stretched both its profitability and NPL resolution timelines. The SBA growth engine is real but small relative to a long-dated, low-yielding legacy portfolio. Until book value stabilizes and the 2027 breakeven target looks firmer, the beat is better read as a slower bleed than as a recovery.
Read our earnings preview for Ready Capital Corporation: https://www.earningswhispers.com/article/RC/22548
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-30 | |
| Oct-24 | |
| Sep-18 | |
| Sep-15 | |
| Sep-03 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-31 | |
| Jul-30 | |
| Jun-15 |
