Kyivstar Raises Guidance A Third Time On A Revenue Beat, But Slowing EBITDA Growth And A Flagged Q4 Slowdown Temper The Quarter
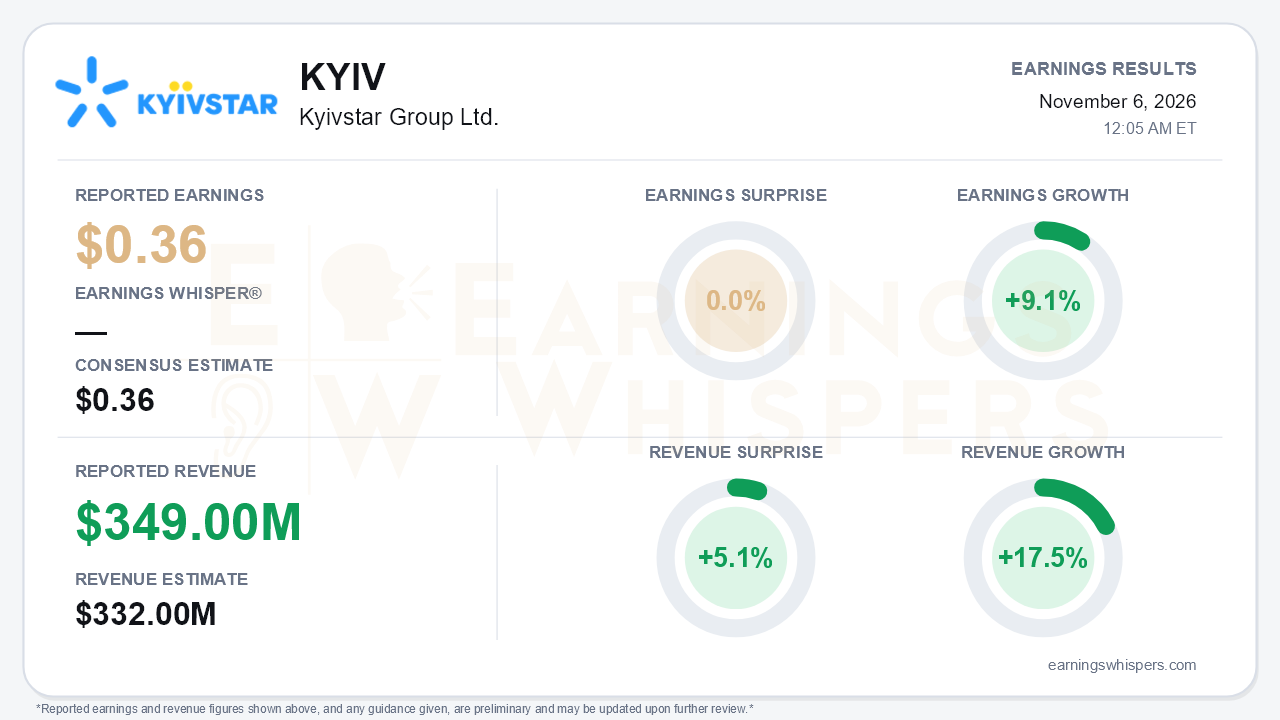
Kyivstar Group (NASDAQ: KYIV) earned $0.36 per share in the third quarter, exactly matching consensus. Revenue was the stronger number: $349.0 million beat the $332.0 million estimate by 5.1% and grew 17.5% year over year. Management also raised full-year guidance for the third straight quarter. The central tension is beneath that headline. Revenue is compounding faster than expected, while profit growth, margins and quarterly cash generation are all decelerating. Management has also told investors to expect a slower fourth quarter.
The quality of the quarter is mixed. Earnings grew 9.1% year over year on Earnings Whispers' normalized basis. That is a more useful measure than the IFRS comparison, which swings from an $89 million net loss in 3Q25 to a $99 million profit. The year-ago loss was driven by a $162 million one-time, non-cash charge tied to the Kyivstar listing. EBITDA rose 10.3% in dollars to $189 million, well behind revenue growth, and the group margin fell to 54.0% from roughly 58% a year earlier. The call shows a clear slowdown in EBITDA growth:
- 23% in Q1;
- 14% in Q2;
- 10% now.
In telecom and infrastructure, revenue rose 8.4%, but segment EBITDA grew just 2.9%, and the margin fell 3.1 points to 57.7% on higher energy costs. Free cash flow also softened sequentially, to $83 million from $104 million in Q2. Still, nine-month free cash flow of $274 million was up 56.8%, helped by a 25.6% drop in capex. Cash climbed to $436 million.
Digital remains the growth engine. Digital revenue jumped 68.9% to $76 million, or 21.7% of group revenue, up from about 16% in Q4 FY25. Digital EBITDA rose 74.2%. That pace is flattered by the Tabletki consolidation from February, and digital margins are slipping:
- digital margin went from 43% in Q1 to 42% in Q2 and 41% now;
- Tabletki's margin eased to about 75% from about 80%;
- Uklon rides grew only about 2%, versus 4% in Q2;
- Uklon EBITDA fell to $10 million from $12 million as reinvestment increased.
In the core mobile business, the trend is decelerating more clearly. Mobile ARPU growth has slowed from 17% in Q4 FY25 to 14%, then 11%, and now about 9%, while the mobile base is still down about 3%. Partly offsetting that, churn fell to just under 12% from 14% in Q2 and 16% in Q1. Multiplay customers rose to 40.3% of active users and generate 1.5 times average mobile ARPU, which supports management's cross-selling argument.
The guidance raise deserves a careful read. FY26 dollar revenue growth moved to 15%–17% from 14%–16%, and hryvnia revenue growth moved to 22%–24%. Dollar EBITDA guidance changed only at the low end, to 10%–12% from 9%–12%. The increments are smaller than earlier raises. The CFO explicitly guided to slower Q4 growth, citing four factors:
- Kyivstar TV lapping prior-year gross revenue;
- solar seasonality;
- Uklon investment;
- electricity inflation.
The call also produced several catalysts. The agreed GigaCloud acquisition, up to $50 million, gives Kyivstar what management calls the leading cloud position in Ukraine. The Ukrtelecom open-access deal lifts the addressable broadband footprint from about 4.6 million to 6.7 million households with no capex. The 3G shutdown frees spectrum for 4G, and Starlink direct-to-cell users exceeded 8 million. War risk remains concrete. September strikes hit Kyivstar infrastructure and a GigaCloud data center, although management described the impact as immaterial.
The market setup reflects that ambivalence. Investor sentiment improved meaningfully into the report, rising from -0.50 to -0.28, but it remains negative. Shares closed at $12.96 before the release, down 6.9% from the opening price after the July report. The stock sits essentially on its 200-day moving average of $12.90. It is roughly midway in its inter-earnings range: 9.7% below the September 3 high of $14.35 and 9.0% above the October 12 low of $11.89. The stock has already given back its late-summer gains, so investors are not paying up for the growth story. The steady erosion in margins and EBITDA momentum gives skeptics something concrete to point to.
The bottom line is that Kyivstar delivered a credible top-line beat, another guidance raise, a strengthening balance sheet and a growing digital franchise. It did not deliver operating leverage. With EBITDA growth slowing for a third straight quarter, ARPU gains fading and a Q4 slowdown already flagged, the debate shifts from whether Kyivstar can grow to whether digital expansion and lower capex can offset energy-driven margin pressure. Until margins stabilize, the stock's position near its 200-day average looks like an appropriate reflection of a story that is improving on revenue but not yet on profitability.
Read our earnings preview for Kyivstar Group Ltd.: https://www.earningswhispers.com/article/KYIV/22492
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Oct-29 | |
| Oct-27 | |
| Oct-08 | |
| Sep-25 | |
| Sep-25 | |
| Sep-02 | |
| Aug-08 | |
| Jul-31 | |
| Jul-30 | |
| Jul-29 | |
| Jul-09 | |
| Jul-07 | |
| Jul-01 |
