Fluor Misses On Earnings But Books A Record $10.9 Billion In Awards, Widening The Gap Between Trough Profits And A Swelling Backlog
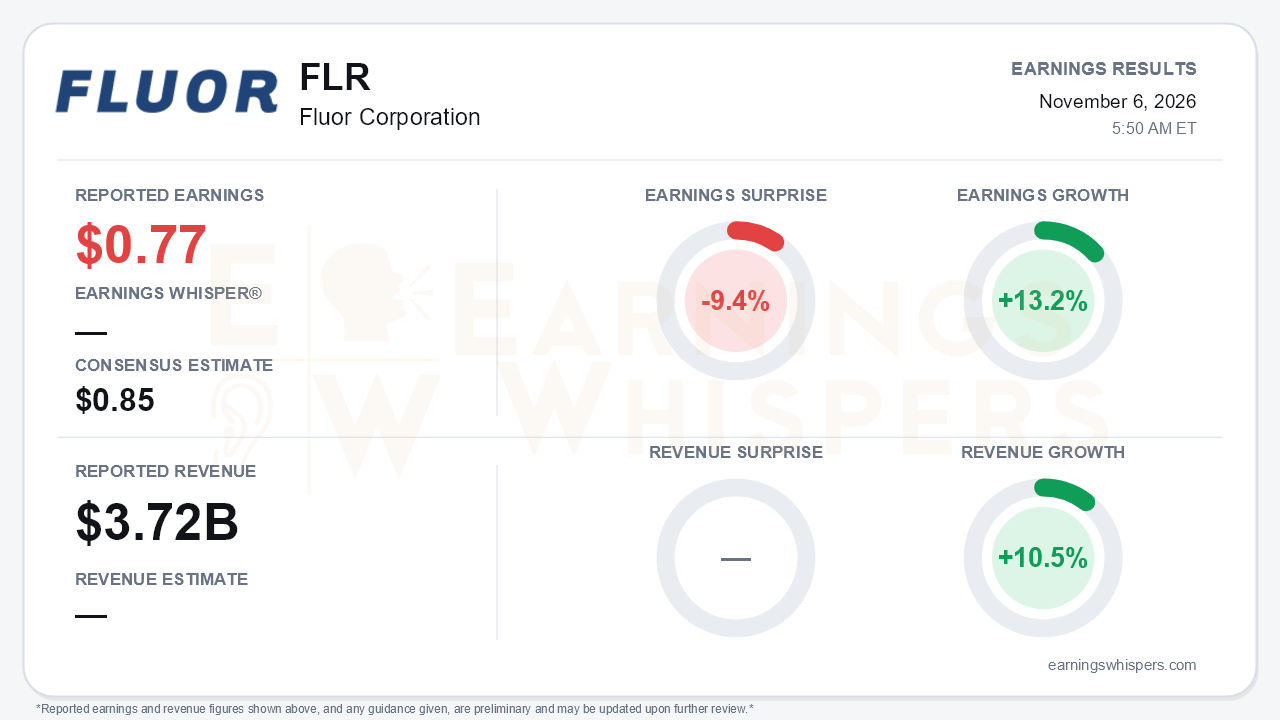
Fluor's third quarter split into two very different stories. Adjusted EPS of $0.77 missed the $0.85 consensus by 9.4%, even though it grew 13.2% from a year earlier on revenue of $3.72 billion, up 10.5%. Meanwhile, the company booked $10.9 billion in new awards, the highest quarterly total in its history. That pushed backlog up 21% to $34.3 billion with a 2.9x book-to-burn. That is the central tension. Fluor is filling its order book faster than at any point this decade, yet near-term earnings power is stuck in a trough. Management affirmed full-year adjusted EBITDA guidance of $500–$525 million rather than raising it.
The quality of the quarter deserves scrutiny. GAAP EPS of $1.16 compares with a $4.30 loss a year ago, but that swing is mostly accounting:
- Last year's quarter absorbed a $653 million revenue reversal from the Santos ruling.
- This year's quarter includes a $73 million pre-tax gain on the sale of the ICA-Fluor stake, which the call referred to as EcoFluor.
Strip out those items and the picture is softer. Adjusted EBITDA fell to $142 million from $161 million, and adjusted EBITDA margin slipped to 3.8% from 4.8%, though 80 basis points of the prior-year margin came from the Santos reversal. Adjusted net revenue, which excludes pass-through at-cost revenue, declined to $2.0 billion from $2.21 billion. The year-to-date view is also unflattering: adjusted EPS of $1.80 trails last year's $1.84.
Energy Solutions is where the headline masks the underlying trend. Reported segment profit of $93 million looks robust, but adjusted segment profit was just $20 million versus $120 million a year earlier. Management put the underlying segment margin at roughly 3% as mature projects roll off before new megaprojects ramp. The bright spots were elsewhere:
- **Mission Solutions:** profit rose to $55 million from $34 million on better award fees and nuclear contributions, even as revenue fell 6%.
- **Urban Solutions:** margin improved to 4.3% on milestone achievement and life sciences execution.
Urban also carried another $25 million charge on the troubled mining joint venture first hit in Q1, and that project's completion has now slipped to mid-2027. Management narrowed the full-year Urban margin guide to about 2.5%, down from 3–4% in the initial 2026 outlook. It also raised G&A guidance to $180–$190 million on incentive compensation tied to the higher stock price.
The call nonetheless preserved a credible growth story, and the forward metrics moved in the right direction:
- **Cash flow:** adjusted operating cash flow guidance rose to $430–$460 million from $300–$320 million.
- **Book-to-burn:** the outlook firmed to potentially approaching 1.4x.
- **Segment margins:** guidance lifted to 7% for Energy and 6.5% for Mission.
- **Tax rate:** guidance was trimmed to 25–27%.
Management said margins on new awards are better than assumed at the early-2025 investor day. It also described a pipeline of 25 megaprojects averaging $4.5 billion, mostly sole-source or negotiated. Near-term catalysts include:
- a TerraWolf data center award in the low single-digit billions expected in Q4;
- a multibillion-dollar South American copper project in Q4 or Q1;
- a second X-Energy SMR project at Hanford;
- pending gas power EPC work.
The first 2027 framing called for low-double-digit adjusted EBITDA growth.
Bears have legitimate ammunition, though. Full-year EBITDA guidance has been ratcheted down twice this year, from $525–$585 million to $525–$560 million to the current range, before being held this quarter. A reimbursable client's scope change could remove about $2 billion from backlog as early as Q4. The ICA-Fluor sale takes roughly $45 million of EBIT out of the 2027 base. Management also conceded that Q3 benefited from non-repeating closeouts and settlements and that megaproject earnings will not peak until 2028. The backlog mix is shifting as well, with reimbursable work down to 69% of backlog from 82% a year ago. That shift raises execution risk at a time when one fixed-price-style problem project keeps slipping.
Investor expectations entered the report on firmer footing. Earnings Whispers sentiment moved from slightly negative (-0.06) to moderately positive (+0.27), a meaningful improvement. Price action tells a more cautious story. Shares were $44.98 heading into the release, down 17.5% from the open after the August report and 8.9% below the 200-day moving average. The stock set a 52-week high of $58.35 on September 3 and has since given back nearly 23%. It sits only 5.4% above the October low of $42.68. The market had already de-rated the stock during the inter-earnings period even as sentiment warmed. In effect, much of the trough-earnings narrative was arguably priced before the miss arrived.
The bottom line is that Fluor's quarter was weak on current earnings quality and strong on future revenue visibility. The adjusted miss, declining adjusted EBITDA, and roughly 3% underlying Energy margin show a business in a transition trough. Record awards, a $34.3 billion backlog, raised cash flow guidance, and $1.1 billion in year-to-date buybacks give the long-term story real support. The investment case now rests on execution: converting LNG Canada and the coming data center and mining awards into the margin expansion management expects in 2027 and 2028, without further slippage on legacy and problem projects.
Read our earnings preview for Fluor Corporation: https://www.earningswhispers.com/article/FLR/22486
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 21 min | |
| 1 hour | |
| 1 hour | |
| 6 hours | |
| 7 hours | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-30 | |
| Oct-29 | |
| Oct-27 | |
| Oct-20 |
