Fidus Beats On NII Rebound And Lifts Its Payout, But A Flat Portfolio Puts The Burden On Q4 Deployment
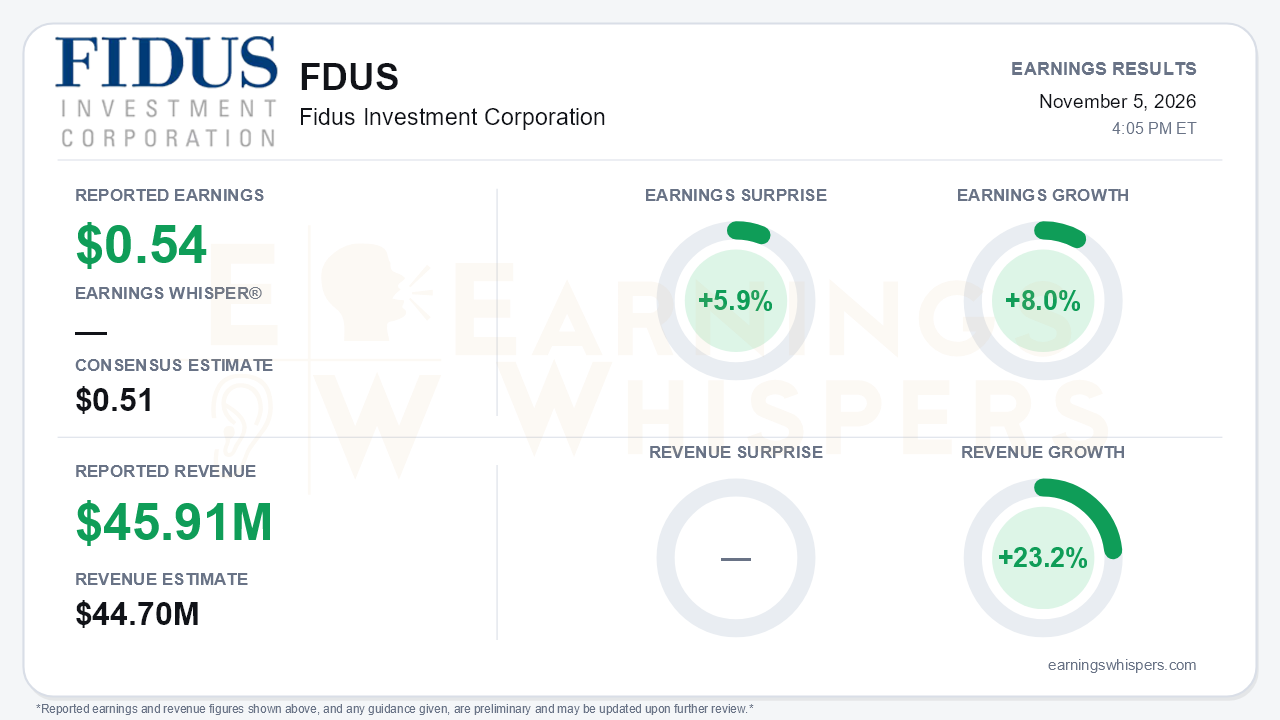
Fidus Investment Corporation (NASDAQ: FDUS) reported adjusted net investment income of $0.54 per share for the third quarter, topping the $0.51 consensus by 5.9%. Total investment income of $45.91 million beat the $44.7 million estimate by 2.7%. Revenue grew 23.2% year over year, while per-share earnings grew 8.0%. The gap between those two growth rates is the key to the quarter. Fidus is growing the business quickly in dollar terms, but equity issuance, rising financing costs and a stalled origination pace are absorbing much of that growth before it reaches shareholders. The beat was real and the dividend went up. The question now is whether a balance sheet loaded with fresh capacity can be put to work fast enough to sustain the run rate.
The quality of the beat holds up better than many BDC prints. Interest income, the core recurring driver, rose 27% to $39.1 million on higher average debt balances, more than offsetting a slightly lower weighted average yield. Including payment-in-kind income, total interest income rose about 24%, which matches the figure cited on the call. Fee income more than doubled to $3.0 million on prepayment and management services fees. That helped the quarter, but it is less dependable. Dividend income turned slightly negative and fell $0.9 million from Q2, a reminder that equity-related income is episodic. Expenses rose 24.6%, led by a $4.0 million jump in interest and financing costs. Adjusted NII dollars grew 18.4%, but a roughly 9% larger weighted share count held per-share growth to 8%. GAAP NII also came in at $0.54. Net increase in net assets slipped to $0.52 from $0.54 a year ago, because an $10.9 million realized loss, mostly on the Vertex exit, was largely offset by $10.3 million of unrealized appreciation.
Sequentially, the trajectory improved. Adjusted NII climbed from $0.50 in Q2 and sits above the $0.52 earned in Q4 2025, though it remains below Q1's fee-inflated $0.62. NAV per share held essentially flat at $19.47 versus $19.46 in Q2, despite the Vertex loss. The $35.5 million at-the-market raise, which management described as accretive, lifted total NAV to $774.4 million. Exiting Vertex also left Fidus with zero non-accruals, a clean credit slate that few lower-middle-market lenders can claim. The board responded by raising the Q4 supplemental dividend to $0.11 from $0.07, for a $0.54 total payout. Spillover income of $0.95 per share gives that payout a cushion even if earnings soften.
Originations are the weak link. Q3 investments of $51.8 million compared with $98 million in Q2, $118.7 million in Q1 and a record $213.7 million in Q4 2025. With repayments of $52.4 million, the portfolio did not grow at all. Management's tone nonetheless turned noticeably more constructive, moving from calling deal flow "picking up" last quarter to saying activity levels "really increased." It expects Q4 originations to exceed repayments and a more active 2027 if conditions hold. Early fourth-quarter activity lends some support: about $44 million was deployed into CasePoint and SnugZ, against a $22.5 million payoff from Green Cubes. The firepower is clearly there. SBA approval of a $250 million debenture limit adds $75 million of SBIC capacity, liquidity rose to about $248.5 million from $170.1 million, and leverage eased to 0.9x from 1.0x.
Bears still have legitimate ammunition. Equity realizations, a meaningful source of NAV growth and supplemental payouts, are now expected to be "very limited" in Q4 and pushed into 2027. Management described the geopolitical backdrop as more uncertain than in a long while. It sees spreads stable to slightly narrower amid competition for quality deals. Questions about software and AI disruption in the portfolio also have not gone away. Lower leverage and higher cash are prudent, but idle capital drags on earnings until it is deployed.
Investor sentiment shifted modestly, moving from slightly negative (-0.07) to modestly positive (0.12) heading into the report. Shares at $19.50 are down 3.5% from the open following the August report. They sit 2.8% above the 200-day moving average of $18.96 and essentially at NAV. That suggests the market has been pricing Fidus as a steady income vehicle rather than rewarding the year-over-year growth in investment income.
The bottom line is that Fidus delivered a clean, credible beat, with improving sequential earnings, zero non-accruals and a higher payout. However, the quarter's growth came from a portfolio that did not expand, and per-share gains continue to trail dollar growth because of dilution and rising funding costs. Management has the capital, the SBA capacity and an improving deal pipeline. Q4 deployment now has to validate the more upbeat tone, especially with equity gains deferred to 2027.
Read our earnings preview for Fidus Investment Corporation: https://www.earningswhispers.com/article/FDUS/22530
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-29 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-30 | |
| May-21 | |
| May-21 | |
| May-07 | |
| May-07 | |
| Apr-30 | |
| Mar-11 |
