Dauch Beats On Dowlais-Driven Sales, But Its First EBITDA Guidance Cut Since The Merger Defines The Quarter
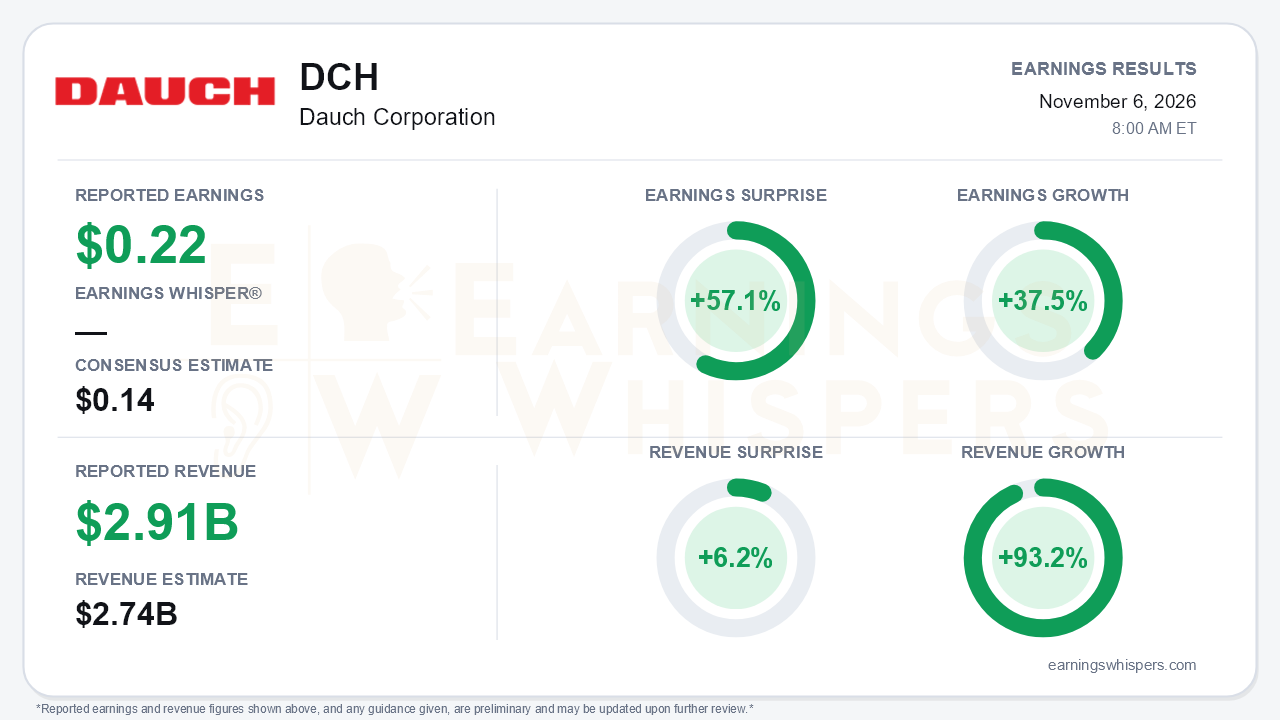
Dauch Corporation (NYSE: DCH) cleared a low bar with room to spare in the third quarter. Adjusted earnings of $0.22 per share beat the $0.14 consensus by 57.1%, and revenue of $2.909 billion topped the $2.74 billion estimate by 6.2%. On Earnings Whispers' normalized basis, earnings grew 37.5% year over year and revenue rose 93.2%. The headline beat is not the story, though. This was the first quarter since the Dowlais combination closed in February in which management cut its full-year Adjusted EBITDA outlook. That reversed the raises it delivered in the first and second quarters. The 'raised guidance' label applies only to sales, and that is the central tension: the top line is growing while profitability is moving the wrong way.
The quality of the beat deserves scrutiny. Revenue nearly doubled because Dowlais is now consolidated, so the growth rate says little about organic demand. Adjusted EBITDA of $358.5 million produced a 12.3% margin, down from 13.0% a year ago and from 13.2% in the second quarter. Adjusted EPS has now stepped down from $0.34 in Q1 to $0.32 in Q2 to $0.22. The company's own recast reconciliation also shows $0.30 of adjusted EPS in the year-ago quarter. That comparison conflicts with the normalized 37.5% growth figure and reflects a different prior-year basis. Either way, the sequential trend is clearly decelerating. On a GAAP basis, Dauch swung to a $45.3 million net loss ($0.19 per share) from $9.2 million of net income a year earlier. The loss was weighed down by $47.4 million of restructuring and acquisition costs, a $32.2 million mark-to-market hit on derivatives assumed in the deal, and interest expense that roughly doubled to $86.6 million.
The call explained why margins are slipping. North American production fell about 5% year over year after being flat in the second quarter. RAM heavy-duty volumes were down roughly 15%, Stellantis crossovers were weak, and GM's truck changeover caused downtime in September and October. Energy inflation was described as a minor few-million-dollar issue last quarter. It has now become a named driver of the cut: management expects about $10 million of additional fourth-quarter impact versus Q3 and sees inflation lingering into early 2027, with recovery lagging in a 2022-style pattern. Tier 2 and Tier 3 supplier distress cost another roughly $10 million in the quarter. The sales raise to $10.8-$10.875 billion leans partly on metal pass-throughs, which inflate revenue without adding much profit. Management's tone shifted accordingly, from an 'excellent quarter' in Q2 to a 'solid quarter' facing 'near-term industry headwinds.'
The deal thesis itself is holding up well. Run-rate synergies hit $100 million, up from $35 million in Q1 and $70 million in Q2, so the year-one target was effectively achieved early. The quarterly P&L benefit climbed to $25 million, and management hinted at upside to the $300 million total. Cash generation is also holding:
- Adjusted free cash flow was $126.7 million, versus $98.1 million a year ago.
- Full-year adjusted FCF guidance was narrowed to $270-$310 million with an essentially unchanged midpoint, helped by a roughly $50 million CapEx cut.
- The remaining 2028 notes were redeemed, leaving no significant maturities until 2029.
- Leverage held at 2.6x.
Commercially, Dauch won next-generation business on a European luxury SUV and a side shaft award on a military infantry squad vehicle. The next-generation GM full-size truck launch remains on track for 2027 with similar content and margin. Against that, bears have legitimate ammunition: steel contracts renew in 2027 in a tougher market, tariffs cost $20-$25 million this year, Chinese competition and European capacity cuts persist, and the CFO is changing on December 1. The November 17 Capital Markets Day now carries extra weight.
The market had already priced in a great deal of disappointment. Shares closed at $4.42 on November 5, down 28.8% from the $6.21 open after the August report and 27.5% below the 200-day moving average of $6.10. The stock had set a 52-week low of $4.41 that same day, 41.4% below its September 8 high of $7.55. Investor sentiment improved modestly, from 0.036 to 0.091, but remains close to neutral. That reads as tentative interest rather than conviction.
The bottom line is that Dauch delivered a clean beat against depressed expectations, strong cash flow and synergy capture that is running ahead of plan. Underneath, margins are compressing, sequential earnings are falling and EBITDA guidance has turned lower. The market setup is more complicated than the 57% surprise implies. With the stock sitting at its lows, synergy momentum and cash flow give management a credible defense. Until inflation and North American truck volumes stabilize, however, the burden of proof remains on margins.
Read our earnings preview for Dauch Corporation: https://www.earningswhispers.com/article/DCH/22549
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 6 hours | |
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Oct-12 | |
| Oct-11 | |
| Sep-04 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Jul-28 | |
| Jul-15 | |
| Jun-15 |
